Deem Finance is a UAE-based financial services company offering products for individuals and businesses, including credit cards, personal loans, merchant financing, and corporate deposit products.
Unlike the older descriptions sometimes found online, Deem is not a generic global financial technology model or cryptocurrency platform. It is an established finance company regulated by the Central Bank of the UAE and operates as part of the Gargash Group. For consumers, its current product range includes credit cards and personal lending.
Business customers can access products such as merchant finance and corporate deposits, subject to eligibility, current product terms, and approval. This guide explains seven important facts about Deem Finance, including its ownership, personal loans, credit cards, business products, application process, account management, fees, security, and important factors to review before applying.
If you are comparing borrowing more broadly, also review our personal loan guide, personal loan rates guide, and money-management guide.
Key Takeaways
- Deem is a UAE finance company regulated by the Central Bank of the UAE.
- The company is part of the Gargash Group.
- Its consumer products include personal loans and credit cards.
- Business products include merchant financing and corporate deposits.
- Actual rates, fees, limits, and approval depend on the specific product and applicant.
- Customers should review the applicable Key Facts Statement and Schedule of Fees before accepting a product.
- Official Deem channels should be used for applications, payments, support, and account management.
1. What Is Deem Finance?
Deem Finance is a financial services provider based in the United Arab Emirates. The company’s official information states that it is regulated by the Central Bank of the UAE and forms part of the UAE-based Gargash Group.  Deem was established in 2008 and was acquired by Gargash Group in 2021. Its product offering serves both individual consumers and businesses. Current company information can be reviewed on the official Deem About Us page.
Is Deem a bank?
Deem should not simply be described as a traditional retail bank. It operates as a regulated finance company offering selected financial products rather than the full range of deposit, checking, branch-banking, and other services associated with a conventional commercial bank.
Who owns Deem?
Deem Finance is part of the Gargash Group, a major UAE business group with interests across automotive, real estate, financial services, and other sectors.
Is Deem a fintech or cryptocurrency platform?
No. Although Deem uses digital technology for applications, account access, and servicing, it should not be confused with decentralized finance, cryptocurrency, or blockchain investment platforms. The older version of this article incorrectly treated the company as a broad global digital-finance concept. The company is better understood as a UAE-regulated financial services provider.
2. Deem Personal Loans
A major consumer product offered by Deem Finance is the personal loan. The company’s current website markets personal lending for needs ranging from home improvements to other personal expenses and currently states that salary transfer is not required for its standard personal-loan offering.  Actual eligibility, loan amount, pricing, repayment period, and documentation depend on the applicant and the current product terms. Visit the official Deem website for current product details.
How personal loan approval works
Approval should not be assumed merely because a product is advertised. A finance company may review information such as:
- income;
- employment;
- credit information;
- existing financial obligations;
- requested loan amount;
- and internal underwriting requirements.
Deem’s application documentation also authorizes access to relevant credit-bureau information as part of the credit assessment process.
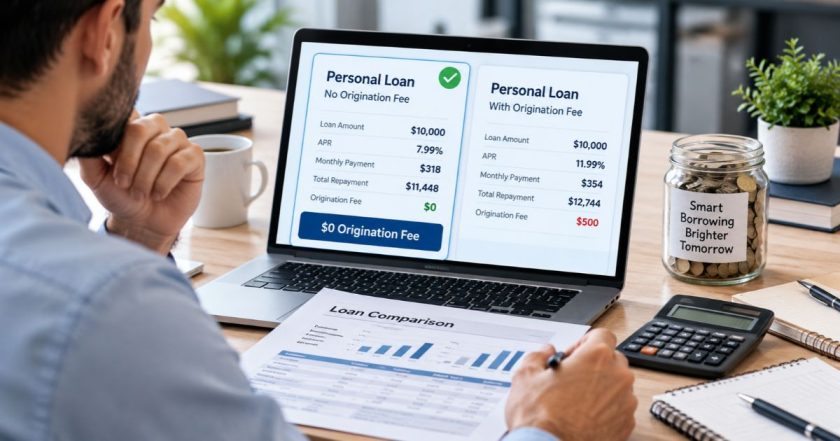
Compare the full cost of borrowing
Before accepting any Deem personal loan, review:
- principal amount;
- interest or profit rate where applicable;
- annual percentage rate or equivalent disclosed measure;
- processing fees;
- monthly installment;
- repayment period;
- late-payment consequences;
- early-settlement provisions;
- and total repayment.
For broader comparison, see our personal loan rates guide. Borrowers with weaker credit profiles can also review our personal loans for bad credit guide.
Secured vs unsecured borrowing
Consumers should understand whether a product requires collateral or is primarily approved using the applicant’s credit and income profile. Our secured vs unsecured loan guide explains the main differences. You can also read our secured personal loan guide for more information about collateral risk.
3. Deem Credit Cards
Deem Finance also offers consumer credit cards in the UAE. Its current card range includes different tiers with varying eligibility requirements, rewards, travel-related features, and lifestyle benefits. For example, Deem currently advertises Titanium and Platinum cards with different minimum-income criteria. Product terms and promotions can change, so always use the current official Deem credit-card page. 
Do not choose a card only for rewards
Reward points, travel benefits, discounts, or promotional offers can be useful, but they should not distract from borrowing costs. Review:
- annual fee;
- purchase interest rate;
- cash-advance charges;
- foreign-transaction costs;
- late-payment fees;
- minimum payment;
- and promotional conditions.
Interest can outweigh rewards
If you regularly carry a balance, finance charges can exceed the value of points or cashback. Our credit-card debt guide explains why revolving balances can become expensive. For a broader explanation of borrowing costs, see what a finance charge is.
Credit utilization and credit reports
Credit-card balances can also influence how lenders evaluate your overall borrowing profile. Our guide on how credit scores are calculated explains utilization, payment history, inquiries, and other factors.
4. Deem Business and Merchant Finance
Deem Finance also serves businesses. Its current product menu includes merchant lending, quick merchant finance, financial guarantees, salary-related business products, and corporate deposit products. 
Merchant loans
The company’s current website advertises merchant financing designed to support business funding requirements. Deem currently promotes a Quick Merchant Loan with financing of up to AED 200,000, subject to current eligibility and approval. Because business-finance terms can change, companies should rely on the applicable application documentation and official disclosures rather than assuming advertised maximums apply to every applicant.
Compare business financing carefully
Businesses should review:
- amount received;
- interest or financing cost;
- processing fees;
- repayment frequency;
- term;
- security requirements;
- guarantees;
- and impact on business cash flow.
Our business loans guide explains the main financing structures. See also:
- What Is Business Finance?
- How to Succeed in Business Finance
- Business Loan Interest Rates
- Business Loan Payment Calculator
- Unsecured Small Business Loans
5. Digital Account Access, Payments and Customer Support
Customers can use Deem Finance digital channels to access account information and manage certain services.
Web and mobile access
The company promotes an online portal for accessing account information and also provides mobile-based account functionality for eligible products. Use only official Deem websites, apps, and support channels when entering personal or financial information.
Payment options
Available payment methods depend on the product. Before making a loan or credit-card payment, verify:
- payment destination;
- processing time;
- minimum amount due;
- cutoff times;
- and any applicable payment fees.
Current details can be checked through the official Deem customer website.
Customer support
The company currently lists UAE customer-care channels including telephone, email, and online support. Because contact details can change, always confirm them directly through the official website rather than relying on an old blog post or social-media comment.
6. Fees, Key Facts Statements and Product Terms
Before accepting any product from Deem Finance, read the current disclosure documents.
Why the Key Facts Statement matters
A Key Facts Statement can help customers identify major product features, fees, risks, and obligations before signing. Do not rely only on promotional headlines such as “fast approval” or “easy installments.”
Review the Schedule of Fees and Charges
Possible costs can include:
- processing fees;
- annual card fees;
- late-payment fees;
- cash-advance charges;
- foreign-exchange fees;
- early-settlement costs;
- and other product-specific charges.
Only the current product disclosure should be treated as authoritative.
Loan agreements matter more than marketing
The company’s personal-loan agreement specifies that actual principal and contractual obligations are set out in the executed agreement. Consumers should read all terms before signing.
7. Is Deem Finance Safe and Regulated?
Deem Finance states that it is regulated by the Central Bank of the UAE. This is materially different from an unregulated online finance website or cryptocurrency platform.
Regulation does not eliminate financial risk
Regulatory oversight does not mean every financial product is suitable for every customer. You still need to understand:
- borrowing costs;
- payment obligations;
- fees;
- credit consequences;
- and the risk of over-borrowing.
Credit-bureau checks
Deem’s current credit-card application documentation authorizes the company to obtain relevant credit information from credit bureaus as part of its assessment and servicing processes.
Protect your personal information
Customers should avoid:
- sharing one-time passwords;
- sending account credentials by email;
- using unofficial payment links;
- giving banking information to unknown callers;
- and downloading financial apps from unverified sources.
Who May Consider Deem Personal Loans?
A Deem Finance personal loan may be worth comparing if you are eligible in the UAE and need structured installment financing. Possible uses might include:
- home-related expenses;
- education costs;
- planned purchases;
- consolidation of qualifying debts;
- or other personal needs permitted under the product.
However, approval does not mean borrowing is automatically a good idea. Compare the offer with your budget and alternatives. For general borrowing preparation, see our how to get a personal loan guide.
How to Compare a Deem Loan Offer
Step 1: Identify the amount you actually need
Borrowing more than necessary increases repayment costs.
Step 2: Check the monthly installment
The payment should fit your regular budget without depending on uncertain future income.
Step 3: Compare total repayment
Do not select a loan only because the monthly installment appears low. A longer term can reduce the monthly payment while increasing the total borrowing cost.
Step 4: Review fees
Check processing, settlement, late-payment, insurance, and any other applicable charges.
Step 5: Review credit consequences
Late or missed payments can create serious financial problems and may affect your future access to credit.
Step 6: Compare alternatives
Compare the offer with other regulated lenders before signing. Our loan-rate comparison guide explains the main factors to review.
Deem Credit Cards: Questions to Ask Before Applying
- What is the annual fee?
- What income requirement applies?
- What APR or finance rate applies to carried balances?
- What minimum payment is required?
- What foreign-transaction charges apply?
- How do cash advances work?
- What late fees apply?
- How does the rewards program work?
- When can rewards expire?
- Can the rewards structure change?
Deem Business Finance: Questions to Ask
- How much financing is actually available to my business?
- What are the financing charges?
- What documentation is required?
- Are collateral or guarantees required?
- What is the payment frequency?
- What happens after a late payment?
- Can the financing be settled early?
- What fees apply to early settlement?
Businesses can use our business loan payment calculator to model potential repayment scenarios.
Deem Finance vs Traditional Banks
| Feature | Deem Finance | Traditional Bank |
|---|---|---|
| Company Type | Regulated finance company | Banking institution |
| Personal Loans | Available | Commonly available |
| Credit Cards | Available | Commonly available |
| Business Finance | Selected products | Often broad product range |
| Digital Access | Yes | Usually yes |
| Full Bank Accounts | Not the same as a full-service retail bank | Generally available |
The better option depends on product availability, eligibility, rates, fees, and your specific financial needs.
Deem Finance and Auto Financing
Historical company financial reports have listed auto-finance activity among the company’s product portfolio. However, consumers looking specifically for vehicle finance should verify current availability directly because product menus can change. For general auto-finance research, use our:
- Auto Finance Calculator
- Auto Finance Options Guide
- Best Auto Finance Deals
- First-Time Auto Loan Guide
- Auto Loan Refinancing Guide
- Paying Off a Car Loan Early
Common Mistakes to Avoid
Assuming Deem is a cryptocurrency project
It is a regulated UAE finance company, not a DeFi token or cryptocurrency network.
Choosing a loan only by monthly payment
A low payment can result from a longer repayment term.
Ignoring fees
Processing, late, settlement, annual, cash-advance, or other charges can materially affect total cost.
Applying without checking affordability
Your approval limit is not necessarily the amount you can comfortably repay.
Using unofficial websites
Use official Deem channels for applications, account management, payment instructions, and customer support.
How Deem Fits Into a Personal Financial Plan
A financial product should support a wider plan rather than replace one. Before borrowing, consider:
- your monthly budget;
- emergency savings;
- existing debts;
- income stability;
- insurance;
- and long-term goals.
For broader financial planning, continue with our financial planning hub, top financial tips, and personal finance course guide.
Related Best Finance Live Guides
- How to Get a Personal Loan
- Personal Loan Rates
- Personal Loans for Bad Credit
- Secured Personal Loans
- Secured vs Unsecured Personal Loans
- Business Loans
- Unsecured Small Business Loans
- Business Loan Interest Rates
- Business Loan Payment Calculator
- Business Finance Guide
- Master Your Money
- How a Credit Score Is Calculated
Conclusion
Deem Finance is a regulated UAE financial services company offering products for consumers and businesses. Its current range includes credit cards, personal loans, merchant finance, and corporate financial products. The company should not be described as a generic global fintech model, decentralized-finance system, or cryptocurrency platform. It is an identifiable UAE financial institution operating within the country’s regulatory framework. Consumers considering a Deem loan or credit card should compare actual rates, fees, eligibility requirements, repayment obligations, and alternative products before applying. Businesses should apply the same discipline when evaluating merchant or corporate finance: compare total cost, cash-flow impact, guarantees, documentation, and repayment requirements. Most importantly, rely on the current official Deem Finance Key Facts Statement, Schedule of Fees, application documents, and product terms rather than old third-party articles because products and promotions can change.
Frequently Asked Questions