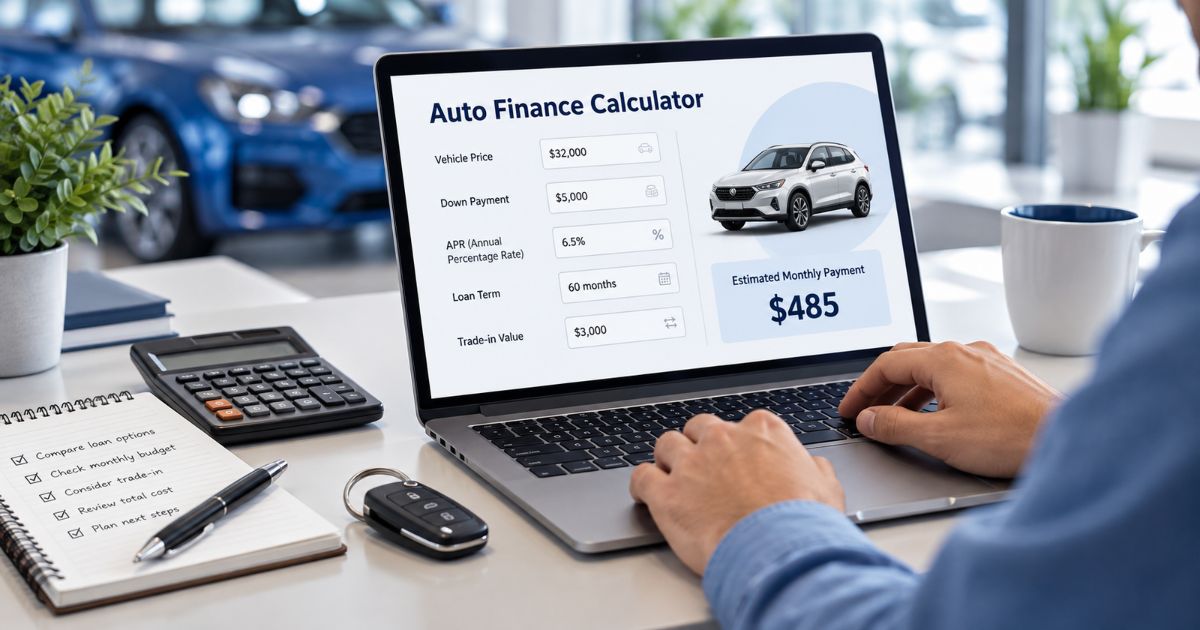
An auto finance calculator can help you estimate a vehicle loan payment before you visit a dealership or apply for financing. By changing the loan amount, APR, repayment term, down payment, and trade-in value, you can see how different financing choices may affect both your monthly budget and total borrowing cost.
A calculator is useful for planning, but its result is only an estimate. Your actual loan offer can differ because lenders use their own underwriting standards, rates, fees, vehicle requirements, and credit criteria.
This guide explains how to use an auto finance calculator, which numbers to enter, how payment calculations work, and what the calculator cannot tell you about a real loan offer.
If you are new to vehicle financing, start with our Auto Finance Center for a broader overview.
Key Takeaways
- An auto finance calculator estimates payments; it does not guarantee a lender’s rate or approval.
- The most important inputs include amount financed, APR, loan term, down payment, and trade-in value.
- A larger down payment generally reduces the amount you need to finance.
- A longer term can reduce the monthly payment but increase total interest.
- APR is more useful than the interest rate alone when comparing borrowing costs.
- Negative trade-in equity can increase the amount financed.
- Optional add-ons can raise both the loan balance and total financing cost.
- Always compare the calculator estimate with the lender’s final Truth in Lending disclosures.
What Is an Auto Finance Calculator?
An auto finance calculator is a planning tool that estimates how much a vehicle loan may cost based on information you enter.
A typical calculator may use:
- vehicle price;
- down payment;
- trade-in value;
- existing trade-in payoff;
- taxes and fees;
- loan amount;
- interest rate or APR;
- loan term; and
- sometimes optional products.
The result may show an estimated monthly payment, total interest, or total repayment amount.
However, a calculator cannot determine whether a lender will approve you or what exact APR you will receive.
The Consumer Financial Protection Bureau explains that an auto loan’s APR, amount financed, term, down payment, and other credit terms are important parts of evaluating vehicle financing.
Review the CFPB auto-loan key terms.
1. Start With the Correct Amount Financed
The first step when using an auto finance calculator is estimating how much money you will actually borrow.
This is not always the same as the advertised vehicle price.
Start with the purchase price
Use the negotiated price of the vehicle rather than focusing only on the monthly payment.
The FTC recommends obtaining a written out-the-door price before discussing financing. This makes it easier to identify taxes, fees, and add-ons and compare vehicles on a more consistent basis.
Read the FTC guidance on financing a vehicle.
Subtract your down payment
A cash down payment reduces the amount that needs to be financed.
For example, if the eligible amount before financing is $30,000 and you put down $5,000, the starting amount requiring financing would generally be lower than if you made no down payment.
Account for trade-in equity
If your trade-in is worth more than its loan payoff amount, that positive equity may reduce the amount you need to finance.
If you owe more than the vehicle is worth, the difference is negative equity.
Rolling negative equity into a new loan can increase the amount financed.
For more detail, see our guide on selling a financed car.
2. Enter a Realistic APR
An auto finance calculator is only as useful as the assumptions you enter.
Using an unrealistically low interest rate can make the estimated payment appear much more affordable than the financing you may actually receive.
APR and interest rate are not always the same
The CFPB explains that an interest rate reflects the cost of borrowing money, while APR is a broader annualized measure that also includes applicable fees required to obtain the loan.
For that reason, APR is particularly useful when comparing different offers.
Our guide to finance charges on a loan explains borrowing costs in more detail.
Where should you get the rate for your calculation?
Possible sources include:
- a bank quote;
- a credit-union quote;
- a lender preapproval;
- a dealer financing offer; or
- a reasonable estimated rate used only for scenario planning.
CFPB recommends obtaining financing quotes before visiting the dealer when practical because actual rates depend on your financial circumstances and lender underwriting. :chatgpt-content-reference{index=”2″}
Compare available offers using our auto finance deals guide.
3. Compare Several Auto Loan Terms
The repayment period has a major effect on the estimate produced by an auto finance calculator.
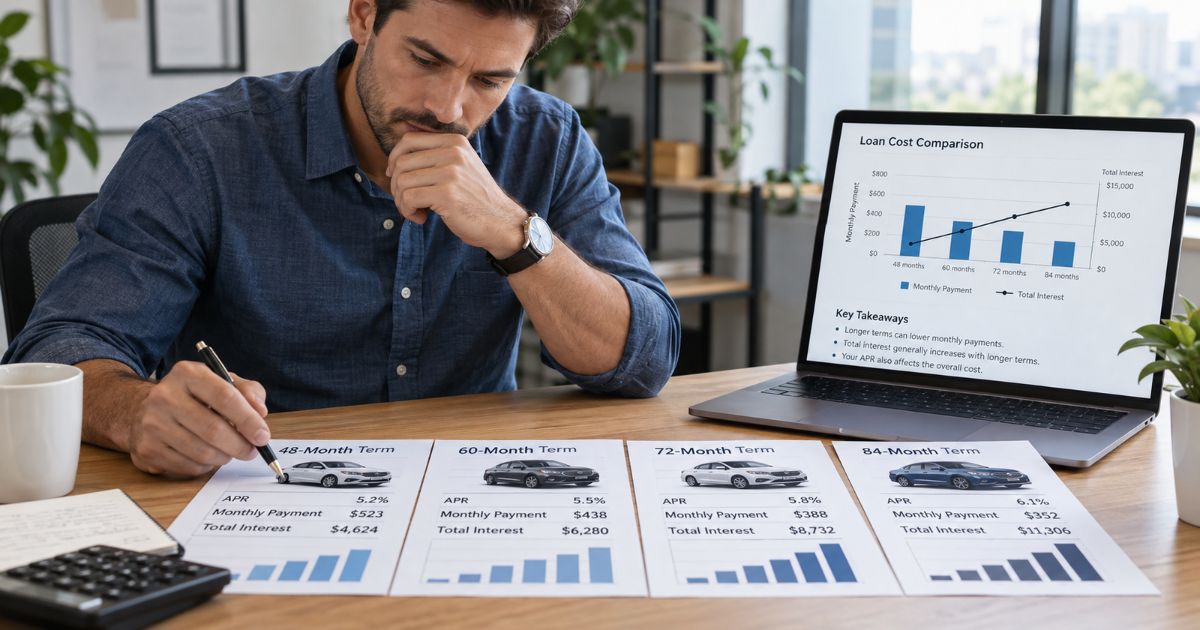
Instead of entering only one term, compare several possibilities such as:
- 36 months;
- 48 months;
- 60 months;
- 72 months;
- 84 months; and
- 96 months where available.
The actual terms available to you will depend on the lender, vehicle, and financing program.
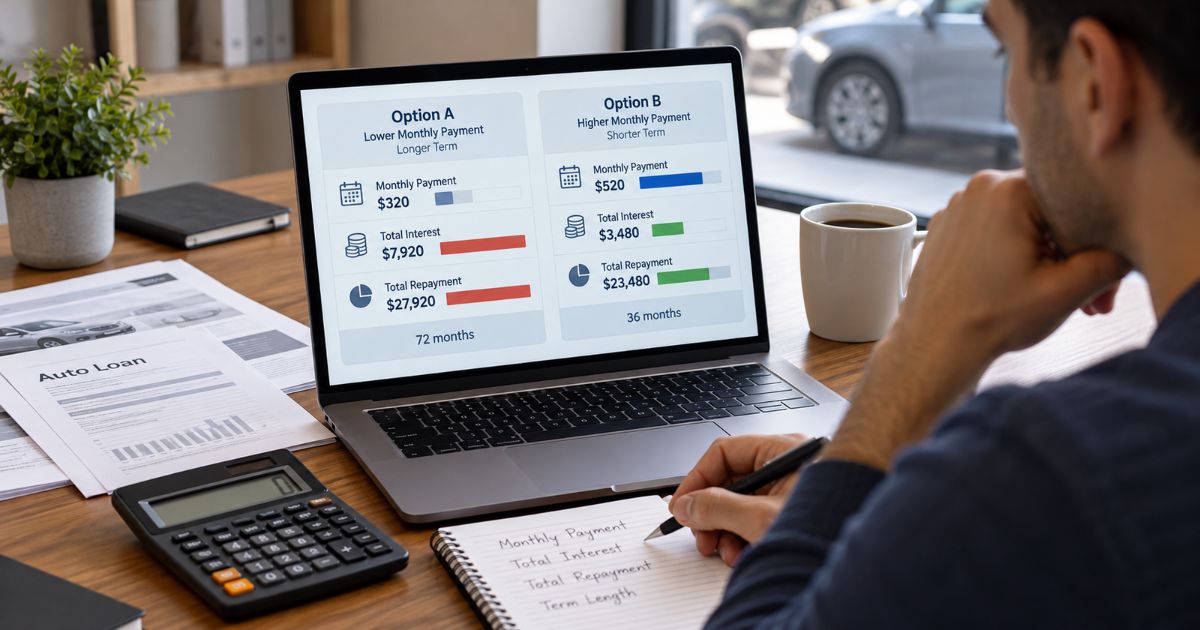
Shorter term
When the amount financed and interest rate remain equal, a shorter term generally produces:
- a higher monthly payment;
- faster principal repayment; and
- less total interest.
Longer term
A longer term generally produces:
- a lower monthly payment;
- slower payoff;
- more months of interest; and
- a longer period of potential negative-equity exposure.
CFPB notes that longer auto loans can reduce the monthly payment but increase total interest and negative-equity risk. :chatgpt-content-reference{index=”3″}
See our complete auto loan terms comparison.
4. Example: $30,000 Loan at 6% APR
The following example shows why testing several repayment periods is useful.
Assumptions: $30,000 financed, 6% annual rate, fixed monthly payments, no additional fees or optional products, and the same rate across every term.
These figures are illustrations only and are not current lender quotes.
| Term | Approx. Monthly Payment | Approx. Total Interest | Approx. Total Payments |
|---|---|---|---|
| 36 months | $912.66 | $2,855.69 | $32,855.69 |
| 48 months | $704.55 | $3,818.44 | $33,818.44 |
| 60 months | $579.98 | $4,799.04 | $34,799.04 |
| 72 months | $497.19 | $5,797.44 | $35,797.44 |
| 84 months | $438.26 | $6,813.56 | $36,813.56 |
| 96 months | $394.24 | $7,847.32 | $37,847.32 |
The example demonstrates why the lowest monthly payment does not necessarily represent the lowest-cost loan.
The FTC specifically advises consumers to compare total financing cost instead of focusing only on monthly payment. :chatgpt-content-reference{index=”4″}
For a deeper look at extended financing, see our 96 month auto loan guide.
5. Include Your Down Payment Correctly
A down payment can materially change the result produced by an auto finance calculator.
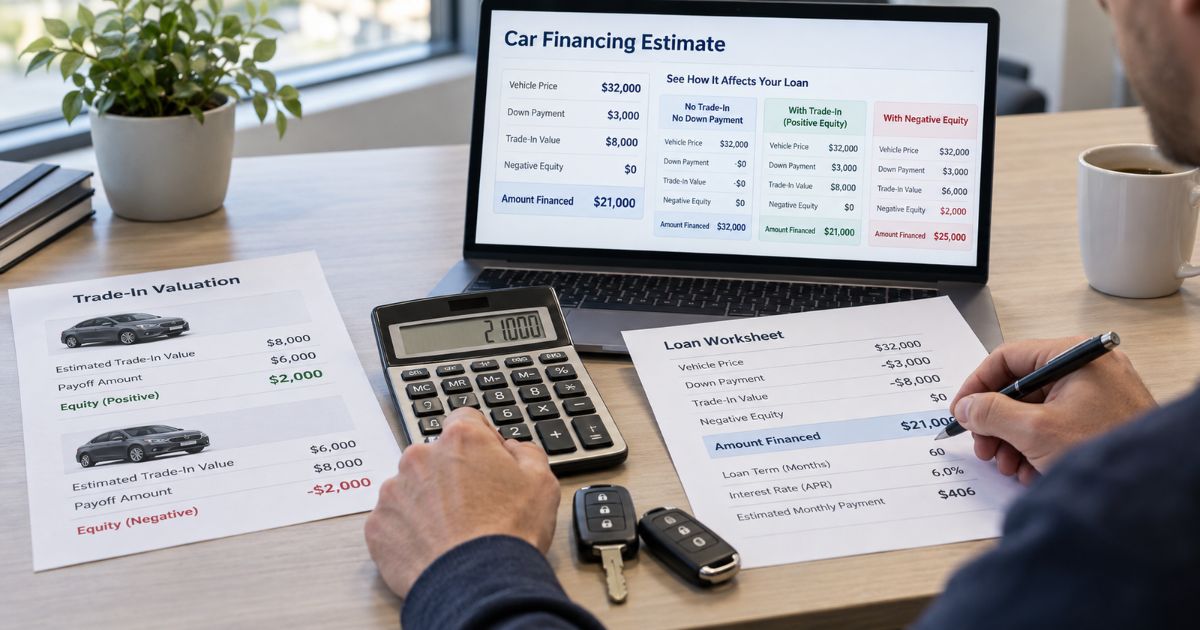
CFPB explains that a down payment reduces the amount borrowed and may reduce both the monthly payment and overall financing cost.
Example
Assume the amount before financing is $35,000.
- With no down payment, you may need to finance approximately $35,000 before considering other adjustments.
- With a $5,000 down payment, that amount could fall to approximately $30,000.
The exact amount financed depends on the transaction, taxes, fees, trade-in, payoff amounts, and optional products.
Do not drain all available cash
A larger down payment can reduce financing costs, but it should still fit your broader financial situation.
Consider maintaining cash for expenses such as:
- insurance;
- registration;
- maintenance;
- repairs; and
- other essential expenses.
Our affordable auto loans guide covers vehicle affordability in more detail.
6. Enter Trade-In Value and Payoff Separately
A common mistake when using an auto finance calculator is entering the trade-in value without considering how much is still owed on the old vehicle.
Positive equity
If your vehicle is worth $15,000 and the payoff is $10,000, there is approximately $5,000 of positive equity before considering other transaction details.
That equity may reduce the amount that needs to be financed.
Negative equity
If your vehicle is worth $10,000 but the loan payoff is $15,000, you have approximately $5,000 of negative equity.
If that balance is rolled into the next loan, the new amount financed can increase substantially.
The FTC warns that negative equity rolled into a new transaction can increase the amount borrowed, monthly payment, or financing period. :chatgpt-content-reference{index=”5″}
Used-car shoppers can also review our used car loan guide.
7. Include Taxes, Fees, and Optional Add-Ons
A simple calculator estimate may be too low if you enter only the advertised vehicle price.
Depending on the transaction, the amount financed may also include:
- applicable taxes;
- registration fees;
- dealer fees;
- service contracts;
- extended warranties;
- GAP products; and
- other agreed charges.
If these items are financed, the loan balance increases and interest may also be paid on those amounts.
Check add-ons separately
Do not assume an optional product is required simply because it appears in a financing discussion.
Ask for:
- the product price;
- whether it is optional;
- whether it is being financed;
- its cancellation terms; and
- how it changes the amount financed.
If promotional financing is being considered, also see our 0 APR car finance guide.
How Does an Auto Finance Calculator Calculate the Monthly Payment?
Many fixed-rate amortizing car-loan calculators use a standard installment-payment formula.
The basic formula is:
Monthly Payment = P × r ÷ [1 − (1 + r)−n]
Where:
- P = principal or amount financed;
- r = monthly interest rate; and
- n = total number of monthly payments.
Example of converting an annual rate
If the annual interest rate is 6%, a simplified monthly rate for a standard calculation is:
0.06 ÷ 12 = 0.005
That monthly rate is then used with the principal and number of payments to estimate the fixed monthly payment.
Actual loan contracts may have details that affect the final figures, so use the lender’s disclosures as the authoritative source for your transaction.
Monthly Payment vs Total Cost
One of the biggest benefits of an auto finance calculator is being able to see the difference between monthly affordability and total financing cost.
A smaller payment can be misleading
Suppose the dealer shows a payment that fits your target budget.
That payment might have been achieved by:
- extending the term;
- increasing the down payment;
- changing the amount financed;
- using a different APR; or
- a combination of these factors.
Always ask how the payment was calculated.
Compare total of payments
The total of payments shows how much the scheduled loan payments add up to over the term.
That figure can reveal a substantial difference between financing options that initially appear similar.
Our auto financing comparison guide provides additional comparison tips.
How Credit Can Affect Your Calculator Estimate
Your credit profile can influence the rate a lender is willing to offer, but there is no universal table that guarantees a particular APR for a particular credit score.
The CFPB explains that auto-loan interest rates can depend on several factors, including credit history and score, income, debts, amount borrowed, term, down payment, and whether the vehicle is new or used. :chatgpt-content-reference{index=”6″}
Avoid fixed credit-score promises
Do not assume that a score of 700, 750, or any other number automatically qualifies for a particular interest rate.
Different lenders can evaluate the same borrower differently.
Run several rate scenarios
If you do not yet have a lender quote, consider testing several hypothetical APRs.
This shows how sensitive your budget is to the rate you eventually receive.
First-time borrowers can review our first-time auto loan guide.
Preapproval and Auto Finance Calculators
A lender preapproval can make an auto finance calculator more useful because you may have a more realistic APR, maximum loan amount, or repayment term to enter.
However, preapproval does not necessarily guarantee final financing.
Final approval may still depend on the specific vehicle and verification of information.
Does preapproval lock your interest rate?
Not automatically.
Whether a rate is locked, how long it remains valid, and what conditions apply depends on the lender’s actual offer.
Do not assume that every preapproval includes a rate lock.
Shop within a focused period
CFPB explains that multiple auto-loan inquiries made within a rate-shopping period are generally treated as a single inquiry by common credit-scoring models, although the relevant window can vary from approximately 14 to 45 days. :chatgpt-content-reference{index=”7″}
For broader lender comparisons, see our top auto finance guide.
How to Use an Auto Finance Calculator Step by Step
- Enter the vehicle price. Use the negotiated or realistic purchase price rather than only the advertised payment.
- Add applicable taxes and fees. Include costs that will actually be financed.
- Subtract your cash down payment.
- Enter trade-in value.
- Account for any trade-in payoff or negative equity.
- Enter a realistic APR. Prefer an actual lender quote when available.
- Select the repayment term.
- Review the monthly payment.
- Review total interest and total repayment.
- Repeat with several scenarios.
Try changing one input at a time so you can understand which factor is driving the payment.
Auto Finance Calculator Scenarios Worth Testing
Scenario 1: Smaller vehicle price
Reduce the purchase price while keeping the down payment, APR, and term equal.
This shows how choosing a less expensive vehicle can affect the payment without increasing the financing period.
Scenario 2: Larger down payment
Increase the down payment and compare the new amount financed, monthly payment, and total interest.
Scenario 3: Different APRs
Run the same loan at several possible rates to see how borrowing cost changes.
Scenario 4: Different terms
Compare 48, 60, 72, and longer terms with the same amount financed and rate.
Our auto loan term guide provides a detailed term comparison.
Scenario 5: Positive versus negative trade-in equity
Compare a transaction with positive trade-in equity against one where an old loan balance is rolled into the new financing.
What an Auto Finance Calculator Cannot Tell You
An auto finance calculator is a planning tool, not a loan approval system.
It cannot reliably determine:
- whether you will be approved;
- your final APR;
- which lender will accept your application;
- all lender-specific fees;
- whether a particular vehicle meets lender requirements;
- your exact tax treatment;
- final trade-in value;
- the future market value of the vehicle; or
- whether refinancing will be available later.
Always compare estimates with the actual lender disclosures.
Review the Truth in Lending Disclosure Before Signing
The federal Truth in Lending Act requires important credit terms to be disclosed before you become legally obligated on the loan.
Important figures can include:
- APR;
- finance charge;
- amount financed;
- payment schedule; and
- total of payments.
Compare those figures with the assumptions you entered into your calculator.
If the actual payment is materially different, determine why before signing.
Our car financing options guide explains how dealership and outside financing can differ.
Common Auto Finance Calculator Mistakes
- Using the advertised vehicle price only: Taxes, fees, negative equity, or add-ons may increase the financed amount.
- Using an unrealistic APR: The estimate may look better than your actual financing.
- Ignoring the loan term: A lower payment may simply come from borrowing for more years.
- Ignoring negative equity: An old loan balance can materially increase the new loan.
- Using a lender approval as your personal budget: The amount a lender is willing to finance may exceed what you can comfortably afford.
- Ignoring ownership expenses: Insurance, fuel, maintenance, and repairs remain separate from the loan payment.
- Treating the calculator result as a guaranteed quote: The final loan can differ.
Frequently Asked Questions
What is an auto finance calculator?
An auto finance calculator estimates car-loan payments and borrowing costs using inputs such as the amount financed, interest rate or APR, loan term, down payment, and trade-in value.
How accurate is an auto finance calculator?
It can accurately calculate the mathematical result of the assumptions you enter, but the estimate is only as realistic as those assumptions. Your actual loan may have a different APR, fees, amount financed, or term.
What information do I need for a car payment calculation?
Useful inputs include vehicle price, down payment, trade-in value, existing trade-in payoff, applicable taxes and fees, APR, and loan term.
Does a longer car loan lower the monthly payment?
Generally, yes, when the amount financed and rate remain equal. However, the longer term usually means the borrower pays interest for more months.
Does a down payment reduce car-loan interest?
A down payment reduces the amount financed. With other loan factors unchanged, borrowing less generally reduces the amount of interest paid.
Should I use APR or interest rate in a calculator?
Use the input requested by the specific calculator. When comparing real loan offers, APR is especially useful because it provides a broader measure of borrowing cost that includes applicable fees.
Can a calculator tell me what APR I qualify for?
No. Your actual rate depends on lender underwriting and factors such as your credit profile, income, existing debts, vehicle, amount borrowed, and repayment term.
Does preapproval guarantee my car-loan rate?
No universal rule applies. A lender may provide specific terms for a limited period, but conditions and rate-lock policies vary. Read the lender’s actual preapproval terms.
Should I choose the loan with the lowest monthly payment?
Not automatically. Compare the APR, amount financed, repayment term, finance charge, total payments, and complete vehicle ownership cost.
Conclusion
An auto finance calculator is most useful when you use realistic numbers and compare several financing scenarios instead of searching only for the smallest monthly payment.
Start with the real vehicle price, account for your down payment and trade-in position, enter a realistic APR, and compare several loan terms.
Then review both the monthly payment and total borrowing cost.
Before signing, compare your estimate with the lender’s actual APR, finance charge, amount financed, payment schedule, and total of payments.
Continue with our guides to auto financing, auto loan terms, auto finance deals, and affordable auto loans.