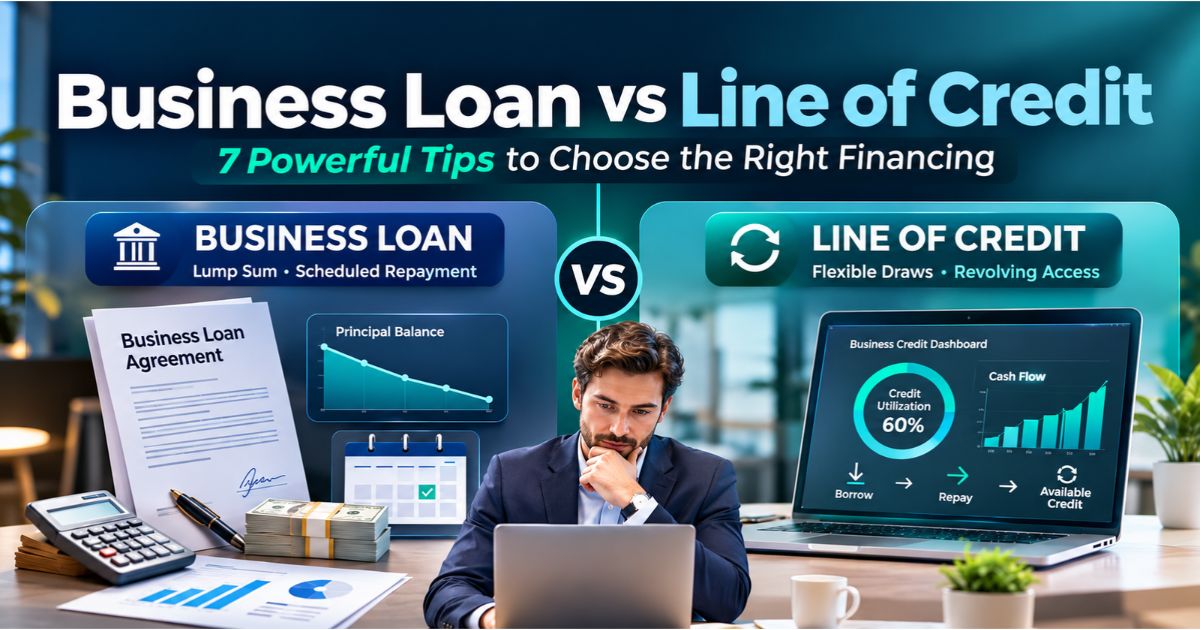
A traditional business term loan generally provides a lump sum for a defined purpose, such as purchasing equipment, expanding operations, or acquiring commercial property. A business line of credit typically allows qualified borrowers to access funds repeatedly within an approved credit limit, subject to the lender’s conditions.
Neither product is automatically better. A term loan may provide a suitable repayment structure for a one-time investment, while a revolving credit facility may be useful for managing seasonal revenue fluctuations, inventory purchases, or temporary operating expenses.
Before making a business loan vs line of credit decision, compare total borrowing costs, available credit, interest calculations, collateral requirements, personal guarantees, and the company’s ability to repay during slower business periods.
This 2026 guide explains seven essential comparison steps, practical financing examples, lender requirements, repayment calculations, and common mistakes to avoid.
For additional background, explore our complete business loans guide and business finance fundamentals.
Key Takeaways
- Business term loans generally provide a lump sum for specific investments or business purposes.
- Lines of credit provide access to funds up to an approved limit, subject to draw and repayment conditions.
- Term loans can have fixed or variable interest rates.
- Lines of credit commonly charge interest on outstanding drawn balances, although other fees may apply.
- Repayment schedules differ by lender and financing product.
- Working capital needs and long-term investments may require different financing structures.
- Collateral and personal guarantees can create financial risks for business owners.
- SBA-backed financing includes certain term loans and revolving credit arrangements.
- Total borrowing costs matter more than advertised interest rates alone.
- Business owners should review written lender offers before accepting financing.
1. Business Loan vs Line of Credit: Understanding the Differences
The first step in comparing a business loan vs line of credit is understanding how each financing structure provides funds and requires repayment.
What is a business term loan?
A business term loan provides an agreed principal amount that the borrower repays according to a loan contract.
Depending on the lender, financing may have a fixed or variable interest rate, monthly installments, or another scheduled repayment structure.
Business term loans are commonly used for:
- Commercial equipment purchases.
- Business expansion.
- Property improvements.
- Acquiring inventory for a major project.
- Eligible debt refinancing.
- Purchasing or expanding business operations.
A defined repayment schedule can help management forecast upcoming financial obligations.
What is a business line of credit?
A business line of credit gives qualified borrowers access to financing up to an approved limit.
For example, a company with a $40,000 credit line may draw $10,000 for inventory, repay the outstanding amount, and potentially access available funds again.
However, redraw privileges depend on the contract. Some facilities are revolving, while others contain limitations, renewal requirements, or defined draw periods.
How does a revolving credit limit work?
A revolving credit limit establishes the maximum permitted outstanding balance, subject to the financial institution’s conditions.
When the borrower uses part of the approved facility, the available borrowing capacity decreases.
Repaying principal can restore borrowing capacity under a revolving arrangement.
Interest is commonly calculated on the outstanding drawn balance rather than the entire approved limit, but unused-line, maintenance, and other fees may still apply.
Business loan versus line of credit comparison table
| Feature | Business Term Loan | Business Line of Credit |
|---|---|---|
| Funding | Generally a lump sum | Draws within approved limit |
| Typical Purpose | Defined purchases or projects | Recurring short-term cash needs |
| Interest | Usually on outstanding principal | Usually on drawn balance |
| Rate Structure | Fixed or variable | Often variable, sometimes fixed arrangements |
| Repayment | Agreed repayment schedule | Depends on draw and facility terms |
| Borrowing Again | Usually requires new financing | May permit repeated draws |
| Collateral | May be required | May be required |
| Main Risk | Scheduled debt obligations | Variable costs and repeated borrowing |
These differences are general characteristics. The final contract determines the actual obligations.
For an overview of financing structures, see our first-time business loan guide and unsecured business financing comparison.
2. Compare How Term Loans and Revolving Credit Actually Work
Understanding the mechanics of each product can help you make a better business loan vs line of credit choice.
How a term loan repayment schedule works
A term loan repayment schedule establishes when the borrower must make payments and how those payments are calculated.
For a conventional amortizing loan, each installment typically covers interest and reduces outstanding principal.
The interest portion generally decreases as the balance falls, assuming the rate remains constant.
However, some business loans have balloon payments, interest-only periods, variable rates, or different amortization structures.
Term loan example
Suppose a business borrows $50,000 at a hypothetical fixed annual interest rate of 10% over 60 months.
With standard monthly amortization and no additional fees, the payment would be approximately $1,062 per month.
Over five years, the borrower would pay approximately $63,741 in total, including about $13,741 in interest.
These figures are illustrative and do not represent a lender quotation.
How a line of credit works
Suppose a company has an approved $50,000 revolving facility.
The business withdraws $12,000 to purchase inventory. The remaining available capacity would generally be $38,000, assuming no other adjustments.
The lender calculates financing charges according to the outstanding amount and applicable terms.
If principal is repaid, available credit may increase again.
Interest calculation example
Assume a company maintains an outstanding credit-line balance of $12,000 for 30 days at a hypothetical 12% annual simple interest rate.
Using a 365-day calculation:
Interest = $12,000 × 12% × 30 ÷ 365
The estimated interest would be $118.36.
This simplified calculation excludes account fees, balance changes, rate adjustments, and other contractual conditions.
Why repayment structures matter
A company receiving a lump sum may begin paying interest on the outstanding principal even if some of the borrowed proceeds remain unused.
With a revolving facility, a borrower may avoid interest on undrawn funds but still incur annual or maintenance charges.
Review our business loan payment calculator guide for repayment calculations and business loan interest rate comparison for additional cost considerations.
When evaluating a business loan vs line of credit, compare actual borrowing behavior rather than assuming the same amount will remain outstanding under both options.
3. Match the Financing Product to Your Business Funding Needs
The most appropriate borrowing structure depends on the timing, duration, and purpose of the expense.
Use a term loan for planned equipment purchases
Major equipment investments often require a defined amount of capital at the time of purchase.
Examples include manufacturing machinery, construction equipment, commercial vehicles, and specialized technology.
A financing term that reasonably matches the asset’s useful life may help reduce the risk of paying for equipment long after it becomes obsolete.
Use a term loan for business expansion
Opening another location, expanding production capacity, or renovating commercial property can require substantial upfront spending.
A term loan may provide a suitable structure when the expected investment and repayment source are clearly defined.
However, projected growth should be based on realistic business assumptions.
Use a line of credit for working capital
Working capital financing supports day-to-day operating needs rather than a single long-term project.
Examples include:
- Purchasing seasonal inventory.
- Managing delayed customer invoices.
- Paying suppliers before revenue arrives.
- Financing temporary production expenses.
- Addressing short-term cash timing gaps.
A credit line may be useful when the company expects to repay borrowed amounts from incoming operating receipts.
Separate temporary gaps from recurring losses
A company that consistently spends more cash than it generates may not solve its problems by repeatedly drawing on credit.
In such situations, management should examine pricing, operating expenses, collection practices, and profitability.
When combining both products may work
Some companies use a term loan for a long-term purchase while maintaining a revolving facility for short-term operations.
For example, a manufacturer might finance machinery through an installment loan and use a credit line to purchase raw materials.
This can be reasonable when the business has sufficient cash flow to service both obligations.
Funding purpose comparison
| Business Need | Potential Financing Approach |
|---|---|
| Equipment Purchase | Term loan or equipment financing |
| Warehouse Expansion | Term loan |
| Seasonal Inventory | Line of credit |
| Temporary Invoice Delay | Line of credit or receivables financing |
| Commercial Property | Appropriate long-term financing |
| Ongoing Operating Losses | Financial restructuring assessment |
For broader planning, see our emergency business loans guide and business financial success strategies.
Choosing the right financing structure begins with a realistic understanding of how the funds will be used.
4. Evaluate Cash Flow and Repayment Capacity
Good cash flow management helps business owners determine whether a financing commitment is sustainable.
Review operating income and expenses
Begin with reliable records of incoming revenue and outgoing operating expenses.
Include payroll, rent, insurance, supplier payments, taxes, and existing debt obligations.
Revenue alone is not sufficient evidence of repayment ability.
Understand cash flow versus profit
A profitable business can experience a cash shortage if customers pay invoices late or if inventory requires substantial upfront investment.
Accounting profit and available cash are different measures.
Companies should evaluate both when borrowing.
Prepare monthly cash flow projections
Forecast expected customer receipts, operating expenses, capital purchases, and required financing payments.
Include seasonality and known large payments.
A useful forecast considers more than a single optimistic revenue scenario.
Calculate debt service coverage
The debt service coverage ratio measures cash flow available for debt service relative to required payments under a specified calculation approach.
DSCR = Cash Flow Available for Debt Service ÷ Required Debt Service
If a company has $120,000 available for annual debt service and required annual debt payments of $90,000, its DSCR is approximately 1.33.
Lenders use different definitions and acceptable thresholds.
Compare repayment during slower months
A fixed monthly installment can create pressure when business revenue declines.
However, a revolving credit facility is not automatically safer. Some credit lines require periodic principal reductions, minimum payments, or full repayment at maturity.
Evaluate a revenue decline scenario
Estimate how your company would manage borrowing obligations if sales declined by 15% or 20% for several months.
Consider whether cash reserves and operating margins would remain sufficient.
Recognize financial warning signs
- Borrowing repeatedly to cover ordinary payroll.
- Missing payments to existing creditors.
- Declining profit margins.
- Increasing overdue customer invoices.
- Insufficient funds for taxes.
- Frequent dependence on expensive short-term advances.
These warning signs may indicate that additional borrowing requires careful financial review.
Our business cash flow fundamentals, cash flow improvement strategies, and repayment planning calculator guide provide additional context.
Before deciding on a business loan vs line of credit, evaluate whether the company can reasonably meet its financial obligations during both strong and weak trading periods.
5. Compare Interest Rates, Fees, and Total Borrowing Costs
The lowest advertised interest rate does not necessarily represent the least expensive financing arrangement.
Fixed interest rates
A fixed interest rate remains unchanged under the agreed terms.
For a fully amortizing fixed-rate loan, this generally supports predictable scheduled payments.
However, a loan may include other charges that affect its overall cost.
Variable interest rates
A variable interest rate changes according to the contract and its applicable benchmark.
Business owners should evaluate whether payments would remain affordable if rates increase.
Origination fees
Some lenders charge fees when establishing a loan.
These charges may be paid upfront, deducted from proceeds, or financed according to the agreement.
Annual and maintenance fees
A line of credit may involve recurring fees for maintaining access to the facility.
Such charges can apply even if the borrower uses little or none of the available credit.
Draw fees
Some credit facilities charge a fee whenever the business withdraws funds.
Multiple small draws may therefore create additional expenses.
Late-payment charges
Both financing products may impose charges for missed or returned payments, subject to their agreements and applicable laws.
Prepayment provisions
Some loans permit early repayment without additional charges.
Others may include prepayment penalties, minimum interest requirements, or other restrictions.
APR and commercial financing disclosures
When a comparable APR is provided, it can help evaluate borrowing costs.
However, business-purpose financing does not always follow standardized consumer-style APR disclosure requirements.
Some commercial products use factor rates, fees, or other pricing methods.
In those cases, compare net proceeds, total repayment, payment timing, and the effective cost of capital.
Cost comparison checklist
| Cost Factor | What to Review |
|---|---|
| Interest Rate | Fixed or variable pricing |
| Origination Fee | Initial financing cost |
| Annual Fee | Recurring credit facility charges |
| Draw Fee | Charges for accessing funds |
| Repayment Frequency | Monthly, weekly, or other schedule |
| Prepayment Charges | Cost of early repayment |
| Total Repayment | All expected financing payments |
For further comparisons, review our business borrowing rates and fees guide, loan payment calculation guide, and unsecured borrowing costs article.
A meaningful business loan vs line of credit comparison should account for the full cost of the funds actually used.
6. Review Lender Eligibility, Collateral, and Personal Guarantees
Financial institutions assess eligibility according to their own underwriting policies and the type of financing requested.
Personal credit history
Some lenders examine the personal credit profile of business owners, especially when the company is relatively new or when a personal guarantee is required.
Business credit history
Established companies may have separate business credit reports that reflect trade accounts, financing obligations, and payment history.
Time in business
Some lenders prefer companies with several years of operating history.
Other providers may consider newer businesses, although documentation and pricing requirements can differ.
Business revenue
Lenders may require a minimum amount of monthly or annual revenue.
They may also consider revenue stability, industry characteristics, and operating margins.
Collateral requirements
Secured financing involves assets pledged to support the debt.
Collateral may include inventory, equipment, receivables, property, or other eligible assets.
If the business defaults, the lender may have rights to recover pledged assets under the contract and applicable law.
Unsecured financing
Some business loans and credit facilities do not require a specifically pledged asset.
However, unsecured financing is not automatically free of personal guarantees or other legal obligations.
Personal guarantees
A personal guarantee can make a business owner responsible for specified financial obligations if the business does not pay.
The scope of liability depends on the agreement.
Business liens
A lender may require a security interest in identified business assets.
Some agreements include broad security provisions covering multiple categories of property.
Comparison of secured and unsecured financing
| Feature | Secured Financing | Unsecured Financing |
|---|---|---|
| Specific Collateral | Usually required | Not necessarily required |
| Asset Recovery Risk | Applies to pledged assets | Other collection remedies may apply |
| Interest Rates | Depend on underwriting | Depend on underwriting |
| Personal Guarantee | May be required | May be required |
| Approval | Subject to lender assessment | Subject to lender assessment |
For additional information, see our business loan eligibility with bad credit guide, unsecured financing risks guide, and first-time borrower requirements.
When choosing between a business loan vs line of credit, understand the financial and legal consequences of missed payments before signing.
7. Choose the Right Financing Structure and Compare SBA Options
The final comparison should reflect the company’s purpose, repayment capacity, and eligibility for available financial products.
Choose a term loan for a defined investment
A conventional installment loan may be a suitable starting point when the company needs a known amount for a major investment.
Predictable repayment arrangements can support capital budgeting.
Choose a credit line for repeated short-term expenses
A revolving facility may be appropriate when a business regularly experiences temporary differences between outgoing payments and incoming receipts.
However, a credit line should not become a permanent substitute for profitable operations.
Consider equipment-specific financing
Equipment financing may be a useful alternative when the borrowed money will purchase machinery or other productive assets.
Consider invoice financing
Companies with qualifying unpaid commercial invoices may evaluate receivables financing or factoring.
Review fees, recourse provisions, and customer collection arrangements.
Understand SBA 7(a) financing
The U.S. Small Business Administration’s 7(a) program supports eligible business financing through participating lenders.
Depending on current program and lender rules, qualifying financing can support equipment, eligible working capital, and other permitted purposes.
The maximum standard 7(a) loan amount is generally $5 million, but approval amounts depend on eligibility and underwriting.
Review the official SBA 7(a) loan program for current information.
Can SBA financing include a line of credit?
Yes. Certain SBA-backed arrangements support revolving financing, including the 7(a) Working Capital Pilot and other eligible programs.
Availability depends on the specific program, participating lender, and applicant requirements.
Understand the SBA Working Capital Pilot
The 7(a) Working Capital Pilot is designed to support qualifying businesses with monitored credit facilities for working capital needs.
Depending on eligibility and program rules, these arrangements may help eligible companies finance receivables, inventory, domestic operations, or qualifying transactions.
The product is not automatically available to every borrower.
Review program terms carefully
SBA-backed financing still requires approval, documentation, and repayment.
Participating lenders assess creditworthiness and the ability to repay.
For additional official information, consult the SBA lending program and lender guidance.
Illustrative financing decision table
| Situation | Potential Starting Point |
|---|---|
| Purchasing expensive machinery | Term loan or equipment financing |
| Seasonal inventory needs | Business line of credit |
| Expanding commercial premises | Appropriate long-term financing |
| Delayed B2B customer invoices | Credit line or receivables financing |
| New business with limited history | Startup financing assessment |
| Recurring operating losses | Financial restructuring review |
For related guidance, review our small business loan application steps, startup business financing options, and business funding overview.
Choosing between a business loan vs line of credit should reflect real financing needs rather than the assumption that one product is universally cheaper.
How to Compare Written Offers Before Applying
Request complete financing information from the lenders you are considering.
Prepare financial documents
Depending on the lender, required documents may include:
- Recent business tax returns.
- Profit-and-loss statements.
- Business balance sheets.
- Cash-flow statements.
- Business bank statements.
- Ownership information.
- Existing debt records.
- Details of available collateral.
- Business plans or financial forecasts.
Compare the amount actually received
Confirm whether fees will be deducted from the approved principal.
The net amount received may be lower than the stated financing amount.
Review the repayment schedule
Compare payment frequency, maturity, possible balloon payments, and the effect of variable rates.
Check draw restrictions
For revolving financing, determine when funds can be withdrawn, the minimum draw size, and whether credit availability can change.
Understand renewal conditions
Some credit facilities are subject to periodic review or renewal.
Do not assume that available credit will remain unchanged indefinitely.
Review default provisions
Understand what constitutes default and whether the lender can demand accelerated repayment under specified circumstances.
Compare written offers
Ask lenders to provide information about:
- Total borrowing costs.
- Interest or pricing methods.
- Origination charges.
- Credit-line maintenance fees.
- Payment frequency.
- Prepayment terms.
- Collateral and guarantees.
- Draw restrictions.
- Renewal requirements.
- Default conditions.
For application preparation, review our business loan application checklist and commercial interest rate comparison guide.
Managing Business Financing After Approval
Receiving financing is only one part of responsible borrowing.
Maintain a repayment calendar
Record payment dates and amounts to reduce the likelihood of accidental missed installments.
Track credit-line draws
Monitor withdrawals, repayments, outstanding balances, and available credit.
Repeated borrowing can become difficult to manage if a company does not maintain accurate records.
Separate financing from operating income
Loan proceeds are not ordinary business revenue.
Record borrowed funds and related liabilities correctly in accounting reports.
Monitor interest and fees
Review statements regularly to confirm charges and payment allocations.
Maintain appropriate cash reserves
Accessible reserves may help cover necessary expenses during slower revenue periods.
The appropriate amount varies according to industry, seasonality, and operating obligations.
Review financial performance
Compare actual cash flow with earlier forecasts and update repayment plans when conditions change.
Contact lenders early during financial difficulty
If a company expects to miss a payment, contact the lender before the due date whenever possible.
Financial institutions may offer arrangements under specific circumstances, but approval is not guaranteed.
Evaluate refinancing carefully
Replacing existing financing can change repayment terms and borrowing costs.
However, lower monthly payments do not necessarily mean lower total financing expenses.
For ongoing financial planning, review our business financial management strategies and marketing and finance planning guide.
Common Business Financing Mistakes to Avoid
Borrowing more than necessary
Excessive borrowing can create additional interest charges and repayment pressure.
Ignoring total costs
Advertised rates may not include all financing fees.
Assuming all term loans have fixed rates
Some business term loans have variable rates or other payment structures.
Assuming credit lines have no unused-balance costs
Annual fees, maintenance charges, and other contractual costs may apply even when a borrower has not drawn the full facility.
Using revolving credit to cover continuing losses
Borrowing repeatedly to fund unsustainable operations may worsen financial problems.
Ignoring collateral risks
Business assets pledged as security can be exposed to lender recovery actions following qualifying default.
Overlooking personal guarantees
Business owners may accept significant personal financial obligations through guarantee agreements.
Failing to compare multiple offers
Financing conditions can differ significantly between institutions and products.
Neglecting cash-flow forecasts
Current account balances do not show whether future obligations will be affordable.
Relying on optimistic growth assumptions
Financial projections should include reasonable downside scenarios.
Before making a business loan vs line of credit decision, review the potential consequences of taking on debt during uncertain business conditions.
Business Financing Comparison Checklist
- Identify the exact funding purpose.
- Calculate the amount required.
- Determine when funds are needed.
- Review the expected useful life of the investment.
- Prepare cash-flow forecasts.
- Calculate existing debt obligations.
- Review personal and business credit information.
- Compare term financing and revolving credit.
- Check SBA-backed financing eligibility.
- Request written lender offers.
- Compare interest and fees.
- Review repayment frequency.
- Calculate total repayment costs.
- Check collateral conditions.
- Review personal guarantees.
- Understand revolving draw rules.
- Confirm renewal requirements.
- Review default conditions.
- Evaluate a lower-revenue scenario.
- Maintain an appropriate cash reserve.
- Check application documentation.
- Confirm the actual net amount received.
- Keep copies of financial agreements.
- Review financing suitability regularly.
Related Best Finance Live Guides
- Business Loans: Types, Requirements and Costs
- First-Time Business Loan Guide
- Business Loan Payment Calculator
Conclusion
A business loan vs line of credit comparison should begin with the reason your company needs financing and its ability to meet future repayment obligations.
A term loan generally provides a suitable structure for a clearly defined investment, while a revolving facility may support recurring short-term working capital needs.
However, financing products differ in interest rates, repayment structures, collateral requirements, personal guarantees, and other contractual conditions.
Business owners should evaluate total borrowing costs, compare lender offers, and prepare realistic financial forecasts before signing an agreement.
Companies should also consider equipment financing, receivables financing, SBA-backed programs, or non-debt alternatives when appropriate.
Ultimately, choosing the right funding solution means matching borrowing obligations with business cash flow and long-term operational goals rather than selecting a product based only on convenience.