American First Finance provides alternative payment solutions for consumers who may not qualify easily for traditional prime credit. Its current products include consumer installment loans through FinWise Bank, Retail Installment Sale Agreements, and lease-to-own arrangements offered through participating merchants.
The company uses the phrase “No Credit Needed,” but that does not mean credit is never checked. AFF states that approval may be possible without a credit score or credit history, while credit reports and other verification data may still be reviewed.
This updated guide explains how American First Finance works in 2026, what its payment options actually are, how applications are reviewed, what costs consumers should examine, how early payoff works, and what to know before signing an agreement.
If you are comparing other borrowing options, also see our personal loan guide, personal loan rates guide, and finance charge guide.
Key Takeaways
- AFF offers several different payment products rather than one universal loan.
- Some consumer installment loans are originated by FinWise Bank and serviced by AFF.
- A Retail Installment Sale Agreement is not the same as a bank loan.
- A lease-to-own agreement is not a credit transaction or traditional loan.
- “No Credit Needed” does not mean “no credit check.”
- Full-term costs can be substantially higher than the original retail purchase price.
- Early payoff or early buyout options may reduce total finance or lease charges when completed within the applicable period.
1. What Is American First Finance?
American First Finance is a U.S. payment-solutions company founded in 2013.
The company says it works with more than 20,000 businesses across over 30 industries and provides payment solutions in all 50 states, Washington, D.C., and Puerto Rico, subject to product availability and legal requirements.
AFF is backed by FirstCash Holdings and focuses heavily on point-of-sale payment options for consumers shopping at participating merchants.
You can review current company information on the official AFF About page.
What does AFF actually provide?
The company currently describes three major payment structures:
- consumer installment loans originated by FinWise Bank;
- Retail Installment Sale Agreements;
- and lease-to-own agreements.
These products are legally and financially different, so consumers should not treat every AFF transaction as the same type of loan.
2. How American First Finance Works
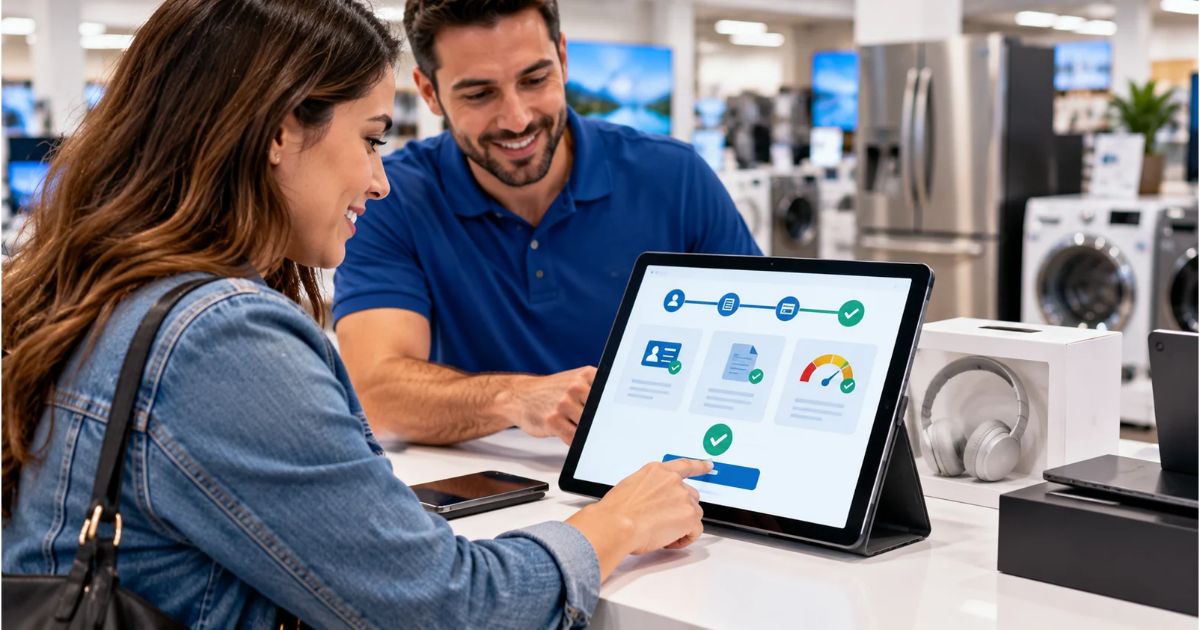
The process generally begins at a participating merchant or through an eligible online application flow.
Application
An applicant provides information requested for identity, banking, income, credit, or other eligibility checks.
American First Finance states that applications may be evaluated using information such as:
- identity verification;
- bank verification;
- third-party information;
- credit-reporting agency data;
- and prior experience with AFF.
Approval is not guaranteed
The company’s current disclosures explicitly state that application amount, cost, and approval remain subject to review.
Consumers should therefore avoid interpreting “No Credit Needed” as guaranteed approval.
Decision timing
Some applications may receive a fast response, but AFF also states that decisioning can take additional time and may require more information.
It is therefore more accurate to describe the process as potentially fast rather than guaranteed instant approval.
3. What Does “No Credit Needed” Mean?
American First Finance uses “No Credit Needed” to explain that a consumer may potentially qualify without an established credit score or traditional credit history.
However, the company states that credit may still be checked as part of the application.
A hard inquiry may be used in some applications and can affect a consumer’s credit score.
That distinction is important:
- No credit needed can mean a score is not the only qualification factor.
- No credit check would mean credit is not reviewed at all.
AFF does not currently claim that every application avoids a credit check.
If you want to understand how inquiries can affect credit, see our credit score calculation guide.
4. FinWise Bank Consumer Installment Loans
One current payment option associated with American First Finance is a consumer installment loan originated by FinWise Bank, a Utah-chartered Member FDIC bank.
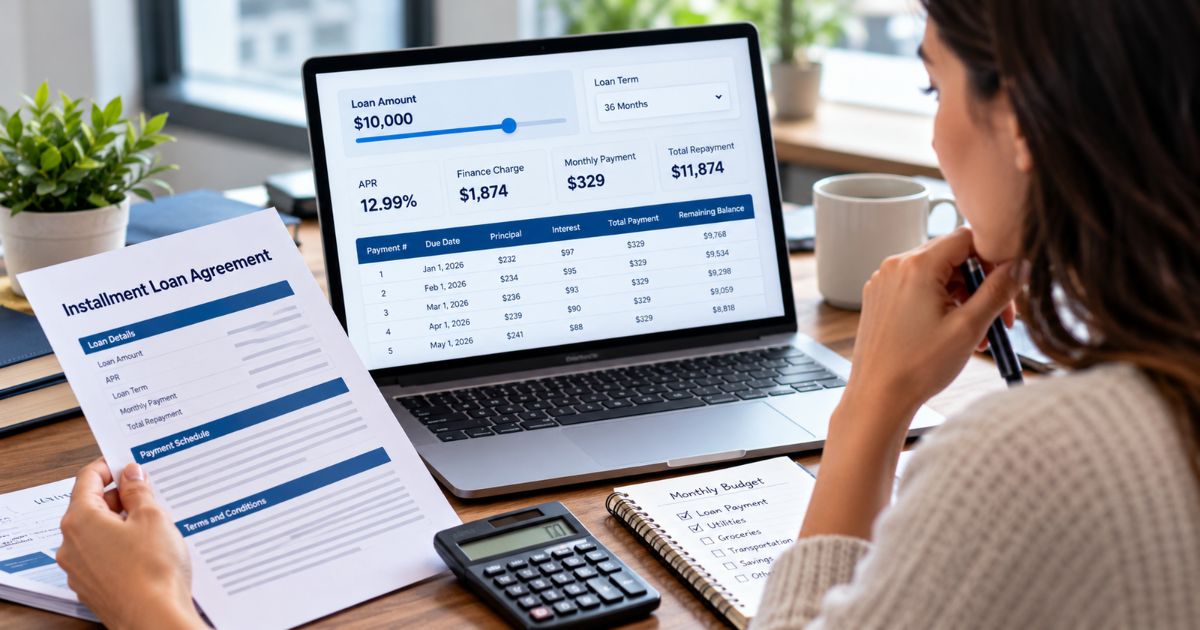
Who actually issues the loan?
For this product, FinWise Bank is the originating lender while AFF sub-services the account.
Funds may be sent to the merchant to pay for the approved goods or services.
In certain situations involving returning customers, the bank may fund an eligible loan directly to the customer’s checking account for personal, family, or household use.
Read the loan agreement carefully
Before accepting any consumer installment loan, review:
- amount financed;
- APR;
- finance charge;
- payment frequency;
- number of payments;
- late-payment provisions;
- and total repayment.
Our personal loan rates guide explains why APR and total repayment matter more than payment size alone.
5. Retail Installment Sale Agreements
A Retail Installment Sale Agreement, often called a RISA, is another product associated with AFF.
A RISA is not a traditional loan.
The consumer enters into an installment agreement with the merchant to purchase goods or services, and AFF may later purchase that agreement from the merchant.
RISA costs can be high
AFF’s current disclosure provides an example of a $1,000 purchase with a $50 down payment and an APR of 169.53% over a 12-month biweekly schedule.
In that example, total repayment is approximately $1,944.81 with full and timely payments over the full term.
This illustrates why consumers should never evaluate an alternative-finance product only by whether the regular payment appears affordable.
Review the official AFF installment disclosure for current examples and terms.
6. Lease-to-Own Through American First Finance
American First Finance also offers lease-to-own arrangements through participating merchants.
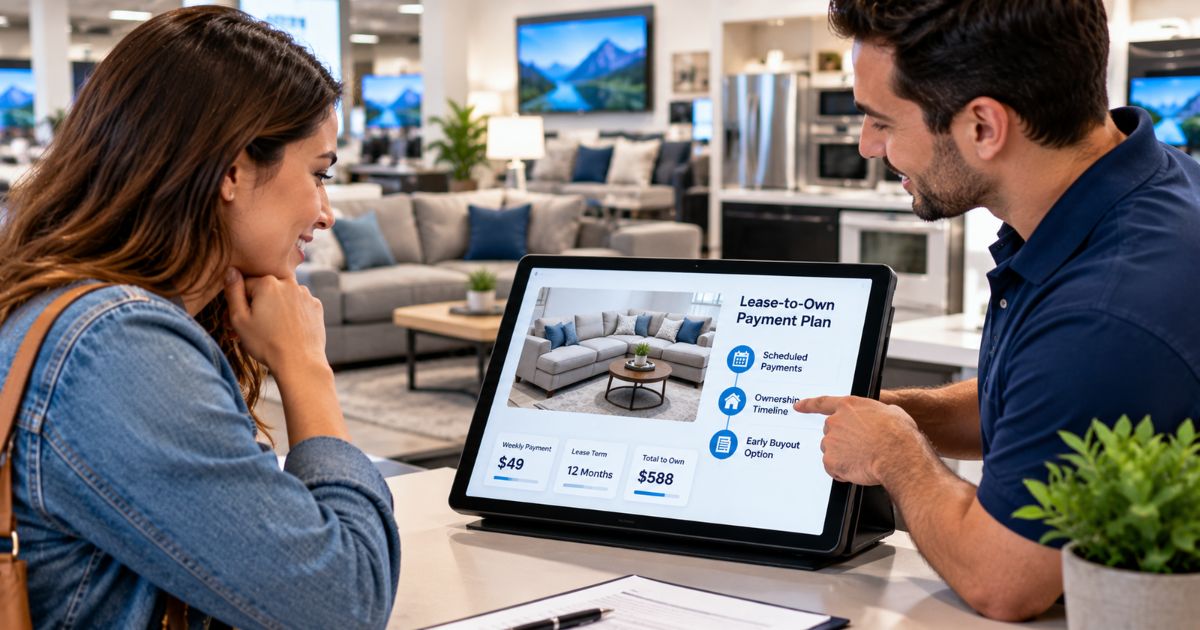
A lease is not a loan or conventional credit transaction.
How lease-to-own works
The consumer chooses eligible merchandise from a participating merchant.
AFF purchases the merchandise and leases it to the consumer.
AFF retains ownership until the consumer completes the required payments or exercises an eligible buyout option.
Potential lease costs
The company’s current disclosures warn that full-term lease payments may total more than double the original retail price.
AFF currently gives an example where a $1,000 item with a $50 processing fee can result in total lease payments of approximately $2,452.21 over a 12-month weekly schedule.
Consumers should examine:
- initial payment;
- weekly or other scheduled rental payments;
- late fees;
- non-sufficient-funds fees;
- delivery charges;
- optional liability-damage-waiver fees;
- early buyout amount;
- and total full-term lease cost.
Can you cancel a lease?
AFF states that a lease can be terminated without penalty by contacting the company and following applicable return requirements.
Always confirm the exact terms in the individual lease agreement.
7. Early Payoff Discount and Early Buyout
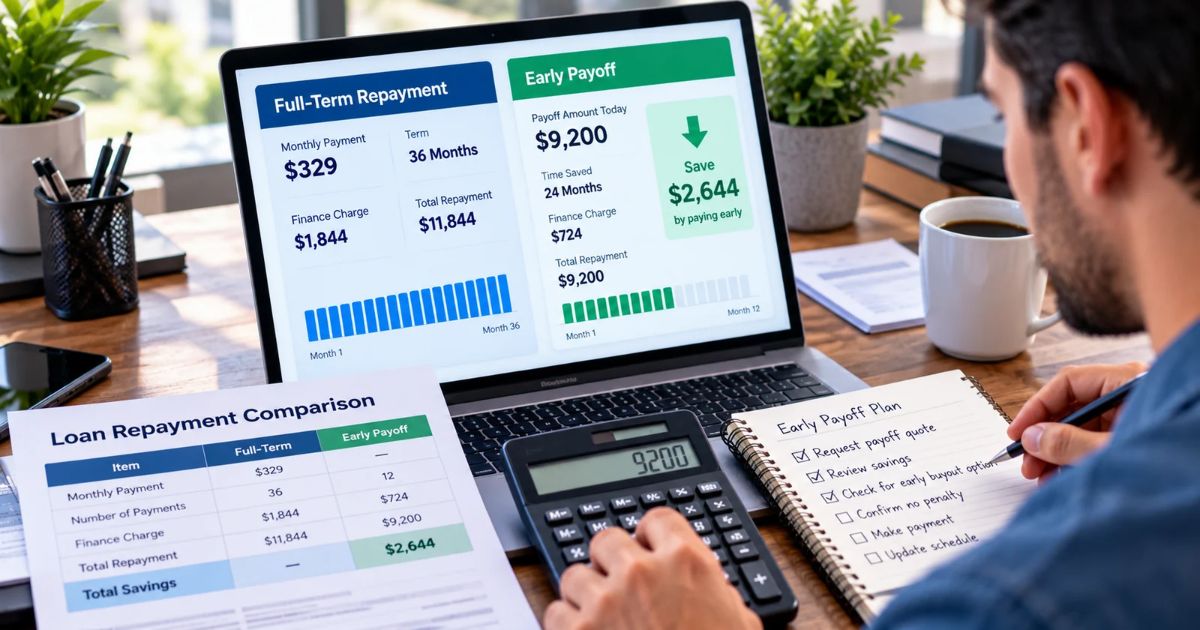
One of the most important features to understand with American First Finance is the possibility of reducing costs through an Early Payoff Discount or Early Buyout Option.
Early Payoff Discount
Some loan or installment products may include an Early Payoff Discount period.
If the consumer pays the required discounted amount before the applicable expiration date, total interest or finance charges may be reduced.
Early Buyout Option
A lease may include an Early Buyout Option.
Exercising it within the applicable period can reduce lease costs compared with continuing regular payments through the full lease term.
Regular automatic payments may not complete the discount automatically
AFF states that consumers generally need to make payments above the normal scheduled amounts to satisfy an Early Payoff Discount or Early Buyout amount before the deadline.
Extra payments can be made through the customer portal or with customer service.
Review the official AFF payments and billing page for current servicing information.
How Expensive Can American First Finance Be?
American First Finance can provide access to payment options for consumers who have difficulty qualifying for prime financing, but convenience can come at a substantial cost.
The company’s own examples demonstrate that full-term repayment can approach or exceed twice the original retail price under certain products.
Do not focus only on payment size
A weekly payment can appear small while the cumulative cost is much larger.
Always calculate:
- cash price;
- down payment or processing fee;
- scheduled payment;
- number of payments;
- total repayment;
- early payoff amount;
- and full-term cost.
Compare alternatives before signing
Depending on your credit profile and purchase, alternatives may include:
- cash savings;
- a traditional bank or credit-union loan;
- a lower-cost personal loan;
- a retailer promotional financing offer;
- a secured loan;
- or delaying the purchase.
See our secured vs unsecured personal loan guide.
Does AFF Report Payments to Credit Bureaus?
Credit reporting depends on the specific account and when it was opened.
AFF currently states that it reports to credit bureaus for most accounts, but new lease-to-own accounts opened on or after January 1, 2024 generally are not reported.
The company also notes state-specific differences and changes affecting Retail Installment Sale Agreement reporting.
Therefore, consumers should not assume every AFF account will build credit.
Check the current AFF credit-reporting FAQ for the rules applicable to your account.
What Products and Services Can Be Purchased?
The company works with merchants across many industries.
Depending on participating retailer and product availability, purchases may involve categories such as:
- furniture;
- mattresses;
- appliances;
- electronics;
- automotive products and services;
- tires and wheels;
- home-improvement products;
- jewelry;
- and certain healthcare-related purchases.
Not every product is available through every merchant or in every jurisdiction.
Benefits for Participating Merchants

Merchants may use American First Finance to provide alternative payment options to customers who cannot or do not want to pay the full price upfront.
Potential merchant advantages
- additional payment choices;
- higher potential conversion rates;
- access to consumers with varied credit profiles;
- point-of-sale application tools;
- and merchant support.
AFF says it currently works with more than 20,000 businesses.
Merchant participation does not make every purchase affordable
Retailers and consumers should still pay attention to responsible financing.
An approval should not automatically be treated as evidence that a payment plan fits the customer’s budget.
American First Finance vs Traditional Personal Loans
| Feature | AFF Payment Products | Traditional Personal Loan |
|---|---|---|
| Credit Profile | May consider applicants without established credit scores | Often more dependent on traditional credit underwriting |
| Product Types | Bank loan, RISA, lease-to-own | Loan |
| Merchant Connection | Often point-of-sale | Funds may be used more broadly |
| Costs | Can be high | Varies significantly by borrower and lender |
| Ownership | Lease merchandise may remain owned by AFF until purchase conditions are met | Borrower normally purchases item directly |
Consumers with stronger credit should generally compare other financing before committing to a high-cost alternative product.
Use our how to get a personal loan guide and bad-credit personal loan guide for comparison.
Questions to Ask Before Signing
- Is this a bank loan, RISA, or lease?
- Who is the legal lender or owner of the agreement?
- What is the cash price of the merchandise?
- How much is due upfront?
- What is the APR if applicable?
- What is the total full-term repayment?
- What fees may apply?
- How frequently are payments due?
- Is there an Early Payoff Discount?
- Is there an Early Buyout Option?
- When does the early payoff period expire?
- Will this specific account be reported to credit bureaus?
- What happens if I miss a payment?
- Can I cancel or return leased merchandise?
- Who should I contact during financial hardship?
Common Mistakes to Avoid
Assuming no credit needed means no credit check
AFF states that credit may still be checked.
Assuming approval is guaranteed
Application approval, amount, and cost remain subject to review.
Ignoring total repayment
The regular payment can make a costly contract appear more affordable than it really is.
Missing the early payoff deadline
Failing to complete the required discounted payoff within the applicable period can substantially increase total cost.
Assuming every account builds credit
Credit-reporting treatment varies by product, opening date, and jurisdiction.
Confusing a lease with a loan
Lease-to-own contracts involve different ownership and cost rules.
What to Do If You Experience Payment Hardship
If you are having difficulty making payments, contact the servicer early.
AFF currently provides customer-service and hardship resources through its payment-support channels.
Do not wait until several payments are missed before seeking information.
Keep records
Save copies of:
- your agreement;
- payment confirmations;
- early payoff quotes;
- customer-service communications;
- and account statements.
Related Best Finance Live Guides
- How to Get a Personal Loan
- Personal Loan Rates
- Personal Loans for Bad Credit
- Secured Personal Loans
- Secured vs Unsecured Personal Loans
- Finance Charges Explained
- How Is a Credit Score Calculated?
- Highest Credit Score Guide
- Average Credit Card Debt
- Master Your Money
- Top Financial Tips
- Complete Personal Finance Guide
- Auto Finance Calculator
- New vs Used Car Interest Rates
- First-Time Auto Loan
- Refinance Auto Loan
- Business Loans Guide
- First Time Business Loan
- Business Loan Interest Rates
- Business Loan Payment Calculator
Conclusion
American First Finance provides alternative payment solutions for consumers who may have limited traditional credit options, but its products should be evaluated carefully.
The company currently supports FinWise Bank installment loans, Retail Installment Sale Agreements, and lease-to-own arrangements. These products have different legal structures, ownership rules, fees, and costs.
“No Credit Needed” does not mean that credit is never checked, and approval is not guaranteed.
Full-term repayment can also be expensive. AFF’s own disclosures show examples where a $1,000 purchase can ultimately cost close to or more than twice the original price when payments continue for the full term.
For that reason, consumers should compare the cash price, APR where applicable, full repayment amount, fees, Early Payoff Discount or Early Buyout Option, credit-reporting treatment, and alternative financing before signing.
The best financing choice is not simply the option that approves you fastest. It is the payment structure you understand fully and can repay without creating unnecessary long-term financial pressure.