Good financial decisions usually come from a combination of planning, discipline, risk awareness, and reliable information. These top financial tips cover both personal investing and business financial management while keeping an important distinction between the two.
An investment portfolio has different goals and risks from a company’s operating cash. Likewise, money needed for payroll, taxes, or short-term expenses generally should not be treated the same way as long-term investment capital.
The following top financial tips explain how to set clearer goals, manage cash flow, diversify investments, maintain financial records, evaluate risk, reinvest thoughtfully, and make decisions with a longer-term perspective.
If you are primarily focused on running a company, our finance tips for entrepreneurs provide a more business-specific guide.
Key Takeaways
- Define financial goals before choosing investments or business spending priorities.
- Keep short-term cash needs separate from long-term investments.
- Diversification can help manage investment risk but cannot eliminate it.
- Track business cash flow separately from accounting profit.
- There is no universal emergency-fund amount suitable for every household or business.
- Maintain reliable records before making important financial decisions.
- Understand investment fees, liquidity, risk, and time horizon.
- Reinvest profits only after considering liquidity, taxes, debt, and other obligations.
- Avoid making major decisions solely because of short-term market movements.
- Review financial plans periodically as circumstances change.
1. Start With Clear Financial Goals
The first of our top financial tips is to decide what the money is intended to accomplish before choosing an investment, funding strategy, or business expense.
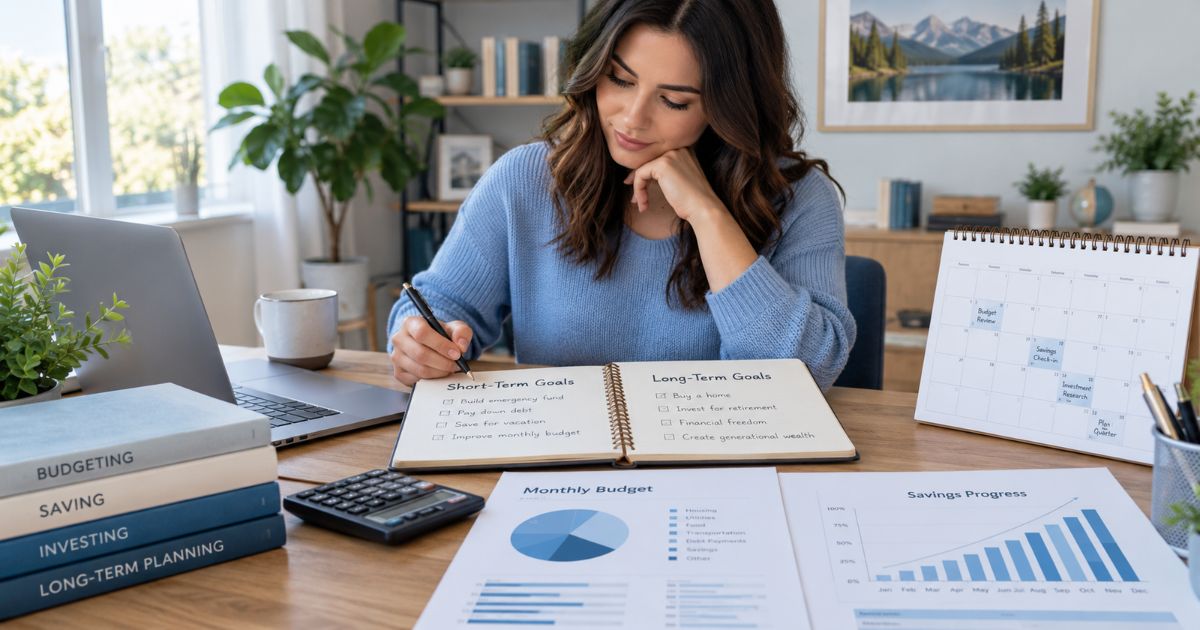
Different goals require different approaches.
For example:
- an emergency fund may need high liquidity;
- a long-term investment portfolio may tolerate more market volatility;
- a business payroll account requires predictable access to cash;
- a growth project may require capital over several years; and
- retirement or other long-term goals may involve a much longer investment horizon.
Make goals measurable
Instead of saying “I want to save more,” define:
- the amount you want to accumulate;
- the purpose of the money;
- the target date;
- how much you can reasonably contribute; and
- how much risk you are willing and able to accept.
Investor.gov emphasizes that investment choices should reflect goals, time horizon, and risk tolerance rather than a universal strategy.
Read Investor.gov’s guidance on asset allocation and diversification.
For broader goal-setting principles, see our strategies for financial success.
2. Keep Short-Term Savings and Long-Term Investments Separate
One of the most practical top financial tips is to avoid treating every dollar as investment capital.
Money needed soon should generally be evaluated differently from money intended for long-term growth.
Short-term money
Funds needed for bills, taxes, emergencies, or near-term purchases usually require easier access and lower volatility.
Long-term money
Money that will not be needed for many years may have more time to recover from market fluctuations, although all investments involve risk.
Investor.gov notes that savings accounts may be appropriate for short-term goals or emergency funds, while investing involves accepting risk in pursuit of potential returns over time.
See Investor.gov’s introduction to saving and investing.
For household-level planning, our personal finance complete guide covers budgeting, saving, and money management in more detail.
3. Diversify Investments Based on Your Goals and Risk
Diversification is an important part of many lists of top financial tips, but it should not be reduced to a fixed formula that everyone should follow.
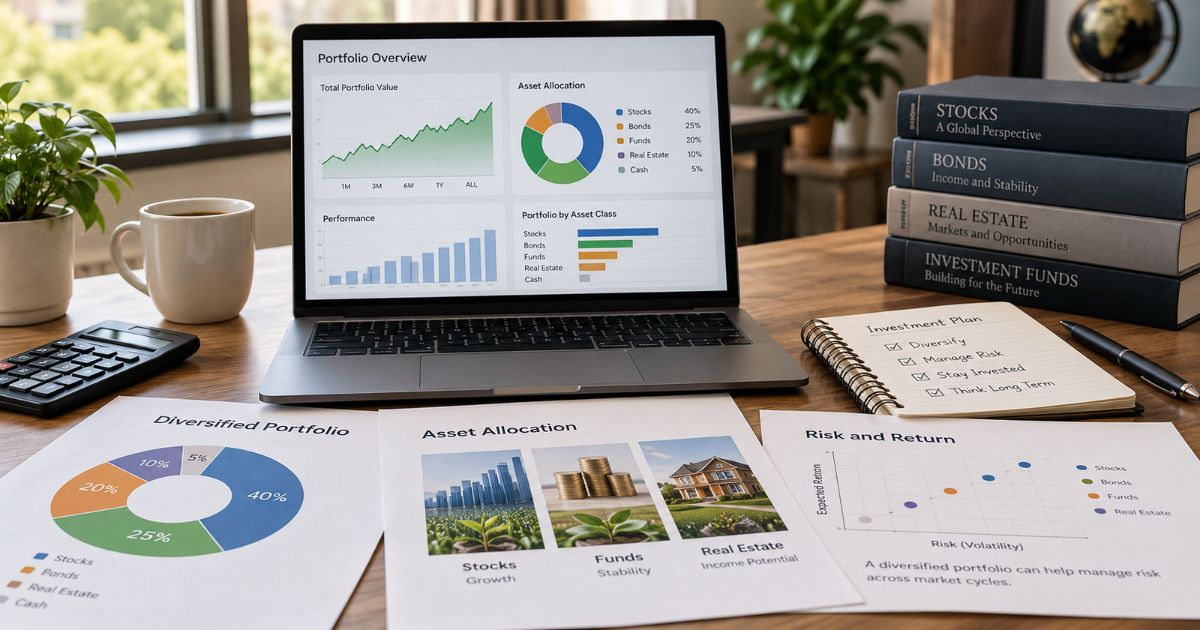
Investor.gov defines diversification as spreading money among different investments to reduce the risk associated with relying too heavily on one investment or asset category.
Diversification can occur at several levels
An investor may diversify:
- across asset classes;
- across companies;
- across industries;
- across geographic markets; or
- through diversified funds where appropriate.
However, owning several investments does not automatically mean a portfolio is well diversified. Several funds can hold many of the same companies or concentrate on the same sector.
Investor.gov explains diversification and investment risk.
Do not assume diversification prevents losses
Diversification can help manage risk, but it cannot guarantee profits or protect against every market decline.
Investment choices should also account for:
- time horizon;
- risk tolerance;
- liquidity needs;
- fees;
- financial goals; and
- personal circumstances.
Readers building financial knowledge can also explore our guide to the best personal finance books.
4. Understand Investment Costs Before Chasing Returns
Another of the top financial tips is to evaluate what an investment costs rather than focusing only on potential returns.
Investor.gov notes that fees and expenses can affect an investment portfolio over time.
Before investing, understand potential costs such as:
- fund expense ratios;
- advisory fees;
- trading costs;
- account fees;
- sales charges where applicable;
- withdrawal restrictions; and
- other product-specific costs.
Risk and return are connected
Promises of unusually high returns with little or no risk should be treated cautiously.
Every legitimate investment carries some form of risk, including market risk, inflation risk, liquidity risk, credit risk, or the possibility of losing money.
Investor.gov’s investment-product guidance recommends understanding risk, fees, diversification, and liquidity before selecting an investment.
Review Investor.gov’s investment product guidance.
5. Monitor Business Cash Flow Carefully
For business owners, one of the most important top financial tips is to track cash flow rather than looking only at revenue or accounting profit.
A business may generate sales and report a profit while still having difficulty paying immediate obligations if customers have not yet paid or cash is tied up elsewhere.
Track cash coming in
Monitor:
- customer payments;
- accounts receivable;
- financing proceeds;
- investment capital; and
- other operating inflows.
Track cash going out
Monitor:
- payroll;
- supplier payments;
- rent;
- taxes;
- debt payments;
- inventory;
- insurance; and
- other operating costs.
A cash-flow forecast can help identify future periods when expected expenses may exceed expected receipts.
Our guide on how to succeed in business finance covers cash-flow planning and financial reviews in greater detail.
6. Maintain Reliable Financial Records
Good records are another foundation of the top financial tips for business owners.
The IRS explains that records can help businesses monitor their progress, prepare financial statements, identify sources of income, track expenses, prepare tax returns, and support information reported on tax returns.
Read the IRS guidance on business recordkeeping.
Review financial statements
Business owners should understand the purpose of:
- income statements;
- balance sheets; and
- cash-flow information.
Each provides a different view of financial performance.
Accurate records also make it easier to compare actual results with budgets and forecasts.
Our business finance guide explains these financial concepts in more detail.
7. Build an Emergency or Liquidity Buffer That Fits Your Situation
Emergency savings are frequently included among top financial tips, but there is no universal reserve amount that works for every person or business.
The right amount depends on your circumstances.
For personal finances
Consider factors such as:
- income stability;
- essential expenses;
- insurance coverage;
- household responsibilities;
- existing debt; and
- access to other liquid resources.
For a business
Consider:
- payroll;
- fixed expenses;
- revenue stability;
- seasonality;
- customer concentration;
- debt obligations;
- inventory needs;
- available credit; and
- how quickly costs can be reduced.
A seasonal business may require a very different liquidity strategy from a company with predictable recurring revenue.
Entrepreneurs can review our entrepreneur finance guide for more business-specific planning.
8. Reinvest Profits With a Clear Purpose
Reinvestment can support growth, but another of our top financial tips is to avoid automatically reinvesting every available dollar.
Before reinvesting business profits, consider:
- current cash reserves;
- tax obligations;
- debt payments;
- upcoming operating expenses;
- expected return;
- business risk;
- alternative uses of capital; and
- how quickly the investment may produce benefits.
Possible reinvestment uses
A business may consider investing in:
- equipment;
- technology;
- employee development;
- inventory;
- marketing;
- product development;
- new locations; or
- other expansion opportunities.
Reinvestment should support a defined business objective rather than simply increasing spending.
Businesses considering outside capital should also review our business loans guide and business loan interest rates guide.
9. Understand Debt Before Borrowing
Debt can be useful, but borrowing deserves its own place among the top financial tips.
Before accepting financing, understand:
- interest rate;
- APR where applicable;
- fees;
- payment amount;
- repayment term;
- total amount repaid;
- collateral requirements;
- personal guarantees;
- late-payment consequences; and
- how payments affect cash flow.
A lower monthly payment is not automatically cheaper
A longer repayment term can reduce the monthly payment while increasing the length of time interest accrues.
Compare financing based on the complete cost and obligations rather than payment size alone.
Our guide explaining finance charges on a loan covers borrowing costs in more detail.
If personal borrowing is being considered, our secured personal loan guide discusses collateral and borrowing risks.
10. Think Long Term but Review the Plan Regularly
The final item in these top financial tips is to combine long-term thinking with regular review.
Long-term goals can help prevent emotional decisions based only on short-term market movements or temporary business results.
However, “long term” should not mean ignoring new information.
Review investments
Periodically check whether your:
- asset allocation still fits your goals;
- risk tolerance has changed;
- time horizon has changed;
- fees remain appropriate; and
- portfolio has become concentrated.
Investor.gov notes that portfolios may need rebalancing over time as different investments gain or lose value.
Review business finances
Business owners should compare:
- actual revenue versus forecast;
- actual spending versus budget;
- cash balance versus expected cash;
- debt obligations;
- profit margins;
- receivables;
- financial risks; and
- progress toward business goals.
For additional financial planning principles, see our financial success strategies.
Top Financial Tips for Managing Taxes
Taxes can affect both investments and business decisions, but tax rules vary significantly based on location, transaction type, business structure, income, and individual circumstances.
Do not assume that choosing an LLC, corporation, or another structure automatically creates a tax advantage.
Entity selection can have legal, tax, administrative, and liability consequences.
For decisions involving your specific circumstances, use current official guidance and consider working with an appropriately qualified tax or legal professional.
Top Financial Tips for Using Technology
Financial technology can make budgeting, accounting, expense tracking, invoicing, investment monitoring, and forecasting easier, but software should support financial decisions rather than replace judgment.
When choosing a tool, consider:
- security;
- cost;
- data portability;
- available integrations;
- reporting quality;
- backup options; and
- whether the software actually fits your needs.
Review automated reports and transaction classifications rather than assuming every software-generated result is correct.
Common Financial Mistakes to Avoid
- Investing money needed soon: Market volatility can create problems when money must be withdrawn at an unfavorable time.
- Using one portfolio formula for everyone: Goals, risk tolerance, and time horizons differ.
- Ignoring investment fees: Costs can reduce returns over time.
- Confusing business profit with cash: A profitable business can still experience liquidity problems.
- Using arbitrary emergency-fund targets: Reserve needs vary significantly.
- Reinvesting without a plan: More spending does not automatically create more growth.
- Borrowing based only on monthly payment: Term, APR, fees, and total repayment also matter.
- Ignoring financial records: Poor data can lead to poor decisions.
- Making decisions solely from market headlines: Short-term movements may not align with long-term goals.
- Treating general information as personalized advice: Individual circumstances can materially change the right course of action.
For additional personal money-management ideas, see our complete personal finance guide.
Frequently Asked Questions
What are the top financial tips for beginners?
Some useful top financial tips for beginners include defining clear goals, maintaining emergency savings appropriate to your situation, understanding debt, separating short-term savings from long-term investments, diversifying investments where appropriate, and reviewing financial progress regularly.
Is diversification always a good investment strategy?
Diversification is widely used to manage investment risk, but the appropriate asset allocation depends on goals, risk tolerance, time horizon, liquidity needs, and personal circumstances. Diversification does not guarantee against losses.
How much emergency savings should I keep?
There is no single amount suitable for everyone. Consider essential expenses, income stability, debt, insurance, household or business obligations, and access to other liquid resources.
Should business owners reinvest all their profits?
Not automatically. Businesses should consider cash flow, reserves, taxes, debt, operating obligations, expected returns, and alternative uses of capital before reinvesting profits.
Is a lower monthly loan payment always better?
No. A lower payment may result from a longer repayment term and may increase total borrowing cost. Compare APR, fees, term, total payments, and other conditions.
What is the difference between saving and investing?
Saving generally prioritizes accessibility and capital preservation for shorter-term needs, while investing involves accepting risk in pursuit of potential returns over a longer period.
How often should I review my financial plan?
There is no universal schedule. Review your plan when circumstances materially change and at reasonable intervals to confirm that goals, cash needs, risk exposure, and assumptions remain appropriate.
Conclusion
The most useful top financial tips are not shortcuts or promises of guaranteed returns. Strong financial management involves understanding your goals, cash needs, risks, costs, and available alternatives.
For investors, that means understanding time horizon, diversification, risk, fees, and liquidity. For business owners, it means maintaining reliable records, monitoring cash flow, managing debt carefully, and investing capital with a defined purpose.
Financial circumstances change over time, so plans should be reviewed rather than followed blindly.
Continue learning with our guides to finance tips for entrepreneurs, business finance, business financial management, and personal finance books.