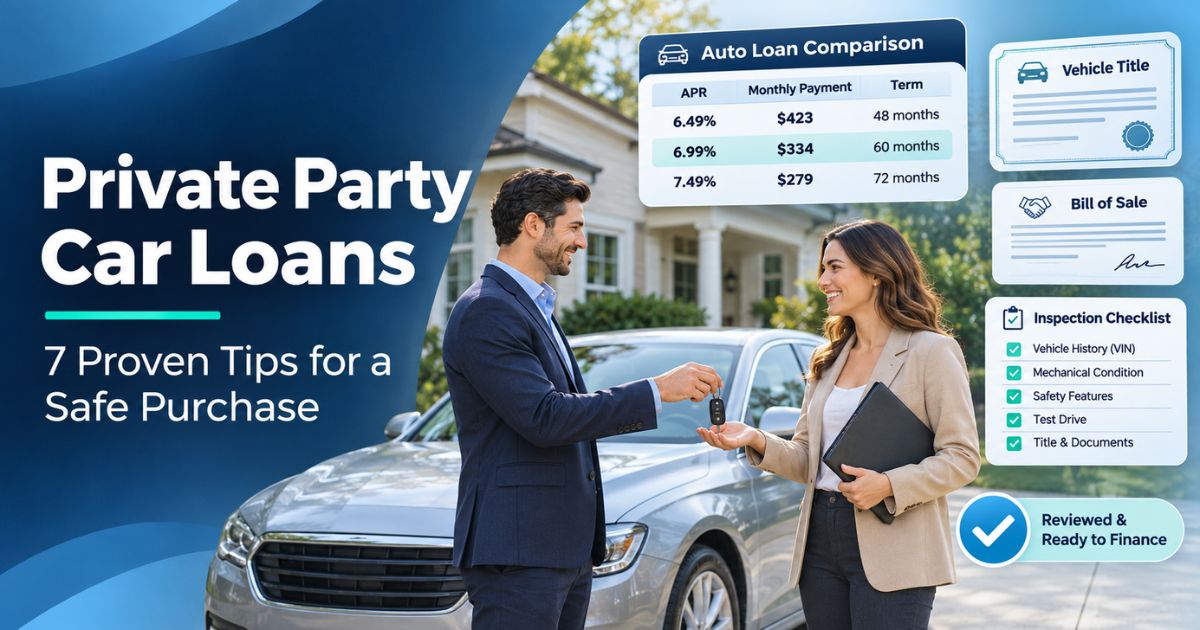
Unlike dealership transactions, private vehicle purchases usually involve direct communication among the buyer, seller, lender, and state motor vehicle agency. The lender may have specific requirements concerning vehicle age, mileage, title status, and market value.
Understanding private party car loans before making an offer can help you avoid unexpected financing costs, title problems, and unsafe payment arrangements.
This guide explains seven proven steps for comparing lenders, obtaining preapproval, inspecting a vehicle, verifying ownership, and completing a secure private-party purchase.
You can also review our auto finance calculator, car loan APR guide, and selling a financed vehicle guide.
Key Takeaways
- Not all lenders finance vehicles purchased from private sellers.
- Compare APR, loan terms, fees, and total repayment before borrowing.
- Verify the seller’s identity and legal ownership.
- Check the vehicle identification number and title history.
- Arrange an independent pre-purchase inspection.
- Confirm existing liens before sending payment.
- Follow your state’s requirements for transferring title and registration.
- Keep signed copies of all purchase and financing documents.
1. How Private Party Car Loans Work
Private party car loans are commonly used when purchasing a vehicle from an individual seller through a classified advertisement, online marketplace, or personal connection.
What makes private sales different?
When purchasing from a dealership, staff often coordinate financing applications, title paperwork, registration, and payment.
With a private sale, the buyer generally takes greater responsibility for verifying the vehicle’s condition, confirming ownership, and ensuring proper documentation.
How the financing process works
A typical private-party purchase involves the following process:
- Find a lender that supports private-party purchases.
- Apply for financing or request preapproval.
- Identify the vehicle and verify its eligibility.
- Arrange a vehicle inspection.
- Agree on a purchase price with the seller.
- Submit the required documents to the lender.
- Complete payment and title-transfer procedures.
The order may vary depending on the financial institution and state requirements.
Who receives the loan funds?
The lender may issue payment directly to the seller, provide a cashier’s check, or pay an existing lienholder first.
Do not assume you will receive the funds personally. Ask how the lender handles disbursement before agreeing to a transaction.
Private sale vs dealership financing
| Feature | Private Seller | Dealership |
|---|---|---|
| Financing | Buyer usually arranges | Dealer may arrange |
| Vehicle Inspection | Buyer coordinates | Buyer should still verify |
| Title Processing | Buyer and seller coordinate | Dealer commonly assists |
| Price Negotiation | Directly with seller | With dealership |
| Loan Availability | Depends on lender | Often more financing channels |
Advantages and disadvantages
A private purchase may offer more direct negotiation and different vehicle choices. However, it can require additional paperwork, verification, and coordination.
For comparison, read our car finance options guide and auto finance deals guide.
2. Confirm Vehicle Eligibility Before Applying
Before applying for private party car loans, determine whether the financial institution will finance the specific vehicle you intend to purchase.
Vehicle age restrictions
Some lenders impose maximum vehicle age requirements.
Older cars may not qualify for conventional secured auto financing because lenders consider collateral value and resale risks.
Mileage restrictions
Financial institutions may also set mileage limits.
These rules vary and can depend on the vehicle’s year, condition, make, and expected value.
Title requirements
Lenders may reject vehicles with certain branded titles, unresolved ownership issues, or undocumented liens.
Ask specifically about rebuilt, salvage, flood-damaged, and other nonstandard title classifications.
Understanding loan-to-value ratio
The loan-to-value ratio, commonly abbreviated LTV, compares the loan amount with the lender’s accepted vehicle value.
LTV = Loan Amount / Vehicle Value × 100
Loan-to-value example
Suppose a lender values a used vehicle at $20,000 and you request $18,000 in financing.
The LTV would be 90%.
If the lender values the same vehicle at $16,000, the requested $18,000 would represent an LTV of 112.5%.
The second situation may require a larger down payment or a lower negotiated price.
How vehicle condition affects approval
Major mechanical damage, unusual mileage, or an uncertain title history may create additional underwriting concerns.
Some lenders request an appraisal or inspection before releasing funds.
Ask about seller restrictions
Certain institutions may restrict transactions involving family members, vehicles purchased through particular marketplaces, or sales outside approved geographic areas.
Confirm these requirements before investing money in inspections or financing applications.
For private party car loans, vehicle eligibility can be just as important as borrower creditworthiness.
Explore our new versus used car interest rate guide and car down payment guide.
3. Compare Private Party Auto Loan Rates and Costs
The interest rate you receive depends on several factors, including your credit history, income, requested financing amount, loan term, and vehicle characteristics.
When comparing private party car loans, consider credit unions, banks, and eligible online lenders.
Credit union financing
Some credit unions provide financing for privately purchased vehicles.
Membership requirements, vehicle restrictions, and loan terms differ among institutions.
Credit unions are worth including in a comparison, but they do not always offer the lowest APR.
Traditional banks
Some banks finance private-party purchases, while others focus primarily on dealer-originated transactions.
Ask whether the institution provides secured used-car loans for individual-seller transactions.
Online lenders
Some online financial institutions offer private-party financing or unsecured personal loans that can be used for vehicle purchases.
These products may differ substantially in APR, funding procedures, and collateral requirements.
Compare APR instead of interest rate alone
The annual percentage rate reflects the cost of credit, including certain finance charges.
It provides a useful basis for comparing loan offers with similar terms.
The Consumer Financial Protection Bureau’s auto financing guidance explains direct lending and dealer-arranged financing, along with key loan disclosures.
Example: Comparing loan terms
Assume you borrow $15,000 at an 8% fixed annual interest rate with monthly amortizing payments and no additional fees.
| Loan Term | Approx. Monthly Payment | Approx. Total Interest |
|---|---|---|
| 36 Months | $470.05 | $1,921.64 |
| 48 Months | $366.19 | $2,577.74 |
| 60 Months | $304.15 | $3,249.88 |
These figures are educational estimates rather than actual loan offers. Exact amounts depend on the contract, payment rounding, and financing costs.
Why longer loans cost more
Extending the term reduces the scheduled payment but generally increases total interest when the principal and interest rate remain unchanged.
Choose a monthly payment that fits your budget without ignoring the total amount owed.
Include all purchase expenses
Your budget may need to cover:
- Vehicle purchase price.
- Sales tax.
- Title-transfer fees.
- Registration charges.
- Independent vehicle inspection.
- Insurance.
- Loan-related fees.
- Initial repairs and maintenance.
Our auto loan calculator, average car payments guide, and finance charges guide can help with cost comparisons.
4. Obtain Preapproval Before Negotiating
Preapproval can help buyers understand their likely borrowing capacity before negotiating with a private seller.
However, an initial offer is not necessarily a final commitment to finance a particular vehicle.
Information required for preapproval
Depending on the lender, you may need:
- Government-issued identification.
- Residential address.
- Proof of income.
- Employment details.
- Existing monthly debt obligations.
- Requested loan amount.
- Permission for a credit review.
Understand credit inquiry types
Some financial institutions offer preliminary estimates based on soft credit inquiries.
Others may conduct a hard inquiry during the application process.
A soft inquiry does not lower your credit score. A hard inquiry may affect it temporarily.
For more information, read our credit prequalification guide and credit score calculation guide.
Check the approved amount
The lender may approve a maximum amount, but this does not mean every vehicle priced below that amount qualifies.
The specific car must usually satisfy eligibility and valuation requirements.
Review APR and repayment length
Compare the offered APR, scheduled payments, financing charges, and total repayment.
Ask whether the stated terms are conditional on identifying an eligible vehicle.
Check the expiration date
Preapproval letters and rate estimates may expire.
Do not assume an offer remains available indefinitely or that the lender will honor it without updated information.
Confirm seller payment procedures
For private party car loans, ask whether payment must be completed at a bank branch, through a cashier’s check, or using another approved method.
Determine whether the seller must attend the transaction in person.
Preapproval vs final approval
Final funding commonly requires verification of the vehicle identification number, title status, insurance, value, and signed purchase documentation.
The lender can change or decline the financing if required conditions are not satisfied.
5. Verify the Seller and Vehicle History
A private vehicle sale can carry risks that are not eliminated by obtaining financing.
Even if the lender approves a car, you should independently check the seller’s identity, title information, and vehicle condition.
Confirm the seller’s identity
Compare the seller’s government-issued identification with the ownership information shown on the title.
If the names do not match, request an explanation and verify whether the person has legal authority to sell the vehicle.
Check the VIN
The vehicle identification number should match across the vehicle, title, registration records, and financing documents.
Investigate any unexplained mismatch before proceeding.
Review title history
Look for salvage branding, flood damage, reported theft, odometer issues, and other significant title concerns.
A vehicle history report can provide helpful information, although it may not include every accident or mechanical problem.
Get an independent inspection
Arrange an inspection by a qualified mechanic who is independent of the seller.
Ask for a written report documenting mechanical condition, safety concerns, and estimated repair costs.
The Federal Trade Commission’s used-car guidance recommends reviewing vehicle history and arranging an independent inspection.
Check for recalls
Use the vehicle’s VIN to investigate outstanding safety recalls through appropriate official resources.
An open recall should be evaluated before completing the purchase.
Test-drive the car
Where legal and practical, drive the vehicle under ordinary road conditions.
Pay attention to braking, steering, transmission operation, warning lights, and unusual noises.
Compare the asking price with vehicle value
Review comparable listings and valuation information.
A vehicle priced well above its lender-assessed value can require a larger personal contribution.
When using private party car loans, independent research helps reduce the risk of financing a vehicle with undisclosed problems.
6. Prepare the Purchase Agreement and Required Documents
Good documentation is essential when purchasing a vehicle directly from an individual seller.
Requirements vary by state, so follow the relevant motor vehicle agency’s current instructions.
Buyer documents
The buyer may need identification, proof of residence, income verification, insurance documentation, and a completed credit application.
Seller documents
The seller generally needs appropriate ownership records and other documents required for a lawful transfer.
These may include the existing title, identification, lien information, and a bill of sale.
Vehicle information
Lenders commonly request:
- Vehicle identification number.
- Year, make, and model.
- Current mileage.
- Agreed purchase price.
- Seller information.
- Title status.
- Existing lien details.
Prepare a written purchase agreement
A purchase agreement should identify the parties, the vehicle, the sale price, and the agreed payment arrangement.
It may also document inspection conditions, financing contingencies, and known vehicle defects.
What should a bill of sale include?
Depending on state requirements, a bill of sale may need:
- Buyer and seller names.
- Vehicle identification number.
- Vehicle description.
- Purchase price.
- Transaction date.
- Odometer information.
- Required signatures.
Odometer disclosures
Federal and state rules may require specific mileage disclosures when ownership changes.
Do not rely on an informal mileage statement if an official disclosure is required.
Document checklist
| Document | Purpose |
|---|---|
| Photo Identification | Verify identity |
| Vehicle Title | Establish ownership and liens |
| Bill of Sale | Record transaction details |
| Purchase Agreement | Document negotiated terms |
| Insurance Evidence | Meet coverage requirements |
| Lien Release | Document prior lien satisfaction |
Before finalizing private party car loans, confirm the lender has received all required documents.
7. Complete Payment, Lien Payoff, and Title Transfer
The final transaction requires careful coordination because payment and legal ownership must be transferred correctly.
When the seller owns the vehicle outright
If the seller has a transferable title without outstanding liens, the transaction may be relatively straightforward.
Still, follow the lender’s payment and title procedures.
When the seller has an outstanding loan
If the seller still owes money, the existing lienholder generally must be paid before its security interest can be released.
The buyer’s lender may coordinate payment to that lienholder.
Example of an existing lien payoff
| Transaction Detail | Amount |
|---|---|
| Agreed Vehicle Price | $18,000 |
| Seller’s Existing Loan Payoff | $7,000 |
| Remaining Proceeds to Seller | $11,000 |
This is a simplified example before taxes, lender fees, buyer down payment, and other possible adjustments.
Confirm the lien release
The old lender may issue an electronic or physical lien release after receiving the required payoff.
The release process and timing depend on the lender and jurisdiction.
Record the new lender’s lien
If the purchase is financed with a secured auto loan, the new lender typically records a security interest in the vehicle under applicable title rules.
Transfer the title correctly
Title transfer requirements differ between states.
Some transactions require notarized signatures, special forms, taxes, or electronic lien processing.
Contact your state motor vehicle department for the applicable procedure.
Understand registration deadlines
State requirements determine when buyers must register a newly purchased vehicle and what documents are needed.
Do not assume deadlines used in another state apply to your transaction.
Verify insurance coverage
Your lender may require comprehensive and collision insurance while the vehicle is financed.
Confirm that coverage begins at the appropriate time before taking possession.
Keep transaction records
Retain copies of:
- Loan documents.
- Purchase agreement.
- Bill of sale.
- Payment confirmation.
- Lien payoff records.
- Title documentation.
- Registration receipts.
- Insurance documents.
With private party car loans, accurate records provide important evidence if payment, lien, or ownership questions arise later.
Common Private Vehicle Financing Mistakes
Paying before verifying ownership
Do not send substantial funds before confirming the seller’s legal authority and understanding the required title transfer.
Skipping a professional inspection
Financing a vehicle with hidden mechanical problems may leave you paying for both loan installments and expensive repairs.
Assuming every lender supports private sales
Some auto loan programs are restricted to dealership purchases.
Ignoring loan-to-value restrictions
A lender may approve your credit application but decline the specific vehicle or limit the financing amount.
Failing to verify existing liens
An unpaid lien can delay or prevent a clear title transfer.
Comparing only monthly payments
A longer term may lower the payment while increasing total interest.
Accepting unusual payment demands
Be skeptical of sellers who insist on rushed payments, refuse inspection, or demand irreversible transfers without reliable documentation.
Forgetting ownership costs
Insurance, registration, maintenance, repairs, and other operating expenses belong in the purchase budget.
Careful preparation reduces risks when arranging private party car loans for used vehicles.
Alternatives to Private Party Car Financing
Paying cash
A cash purchase avoids loan interest and financing approval requirements.
However, it may significantly reduce available savings.
Unsecured personal loans
Some buyers use unsecured personal loans for vehicle purchases when permitted by the lender.
These loans may offer more flexibility but can carry different rates and repayment conditions.
Read our personal loan comparison guide.
Buying through a dealership
Dealership purchases may simplify the financing and title process.
However, buyers should still compare rates, fees, and total costs.
Seller financing
In a seller-financed transaction, the private seller agrees to receive payments over time instead of receiving the full price immediately.
This arrangement requires careful legal documentation concerning interest, payment schedule, title, security interests, and default rights.
State-specific legal advice may be appropriate.
Postponing the purchase
If financing is expensive or the vehicle’s ownership history is unclear, waiting may be safer than accepting an unsuitable deal.
Use the additional time to improve credit, save a larger down payment, or research other vehicles.
Review our credit improvement guide and first-time auto loan guide.
Final Private Party Vehicle Purchase Checklist
- Confirm the lender supports private vehicle sales.
- Review vehicle age and mileage eligibility.
- Compare written financing offers.
- Calculate APR and total repayment.
- Confirm the down payment requirement.
- Review vehicle valuation.
- Verify the seller’s identity.
- Match the VIN to the vehicle title.
- Review the vehicle history.
- Check for outstanding liens.
- Arrange an independent inspection.
- Complete a written purchase agreement.
- Prepare a valid bill of sale.
- Confirm the payment method.
- Arrange insurance coverage.
- Complete title and registration requirements.
- Keep copies of all final documents.
Related Best Finance Live Guides
- Auto Finance Calculator
- What Is a Good Car Loan APR?
- New vs Used Car Interest Rates
- Average Car Payment 2026
- How Much Down Payment for a Car?
- First-Time Auto Loan
- Affordable Auto Loans
- Best Auto Finance Deals
- Car Financing Options
- Auto Loan Refinancing
- How to Sell a Financed Car
- Negative Equity Car Loans
- 96-Month Auto Loan Guide
- Subprime Auto Loans
- Paying Off a Car Loan Early
Conclusion
Private party car loans provide an alternative to dealership financing for eligible buyers purchasing used vehicles directly from individuals.
However, the process requires careful coordination among the buyer, seller, lender, and state motor vehicle agency.
Before signing, compare APR, financing fees, loan terms, and total borrowing costs. Verify the vehicle’s condition, legal ownership, title status, and existing liens.
Arrange an independent inspection and document all negotiated terms in writing.
Successful private party car loans depend on more than receiving approval. Secure payment procedures, accurate title records, appropriate insurance, and a realistic budget are equally important.
Taking time to verify these details can help you avoid unnecessary financial and legal complications.