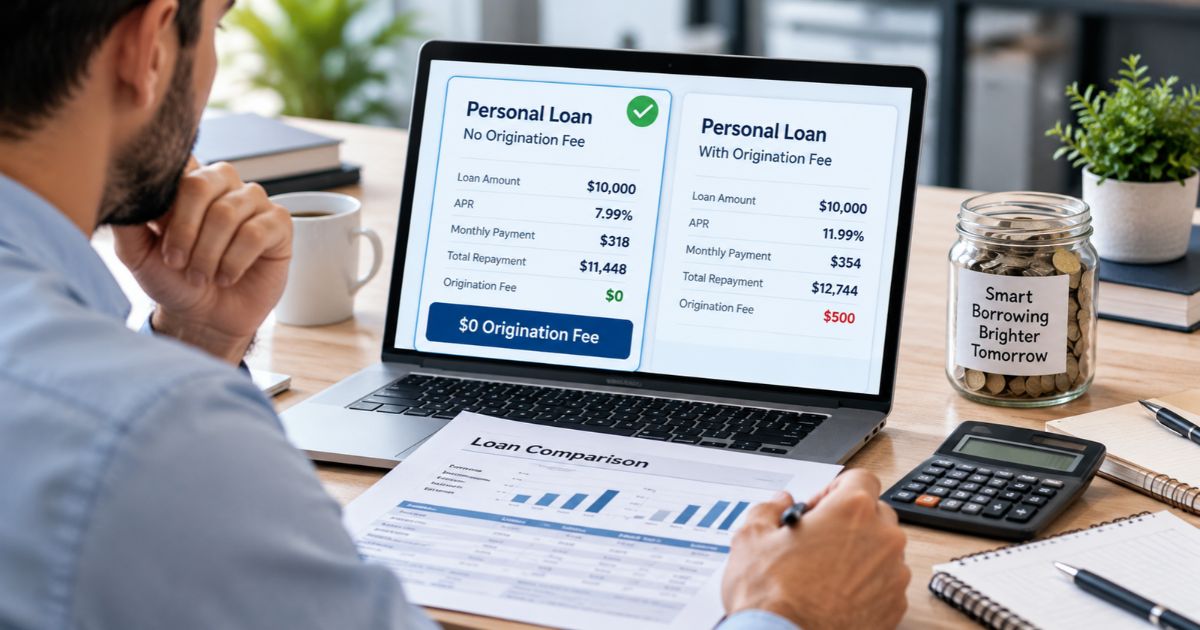
A personal loan with no origination fee can be attractive because the lender does not deduct an upfront origination charge from your loan proceeds. But a zero origination fee does not automatically make a loan inexpensive.
The interest rate, annual percentage rate, repayment term, monthly payment, late fees, credit requirements, optional products, and total repayment can matter just as much.
When comparing a personal loan with no origination fee, look at the complete borrowing cost rather than one missing fee. A loan with no upfront charge but a substantially higher APR can ultimately cost more than an alternative that charges a modest fee.
This guide explains seven checks to make before accepting an offer, including APR, loan proceeds, monthly payments, eligibility, prequalification, debt consolidation, lender reliability, and final loan documents.
For broader borrowing guidance, also review our personal loan guide, personal loan rates guide, and secured vs unsecured personal loans comparison.
Key Takeaways
- No origination fee does not mean no borrowing costs.
- APR can be more useful than the stated interest rate when comparing similar loan offers.
- Check the amount you actually receive and the total amount you will repay.
- Review late fees, returned-payment fees, optional products, and other lender charges.
- Prequalification may use a soft inquiry, but lender processes vary.
- Debt consolidation only helps if the new loan improves your overall repayment position.
- The final loan agreement matters more than an advertisement or comparison-site estimate.
What Does a Personal Loan With No Origination Fee Mean?
A personal loan with no origination fee generally means the lender does not charge an origination fee for making the loan.
An origination fee is one possible cost associated with processing and funding a personal installment loan. Depending on the lender, other charges may still apply.
The Consumer Financial Protection Bureau notes that personal installment loans can involve fees such as origination fees, documentation fees, optional credit or disability insurance, non-filing insurance on certain secured loans, and late fees.
See the official CFPB personal installment loan fee guidance.
Why borrowers like zero origination fees
If there is no origination charge deducted from the proceeds, a borrower may receive the full approved loan amount.
For example, if you need exactly $10,000 for a project, receiving the full $10,000 may be more convenient than having a fee deducted before disbursement.
Why zero fees do not guarantee the cheapest loan
A lender can offer a personal loan with no origination fee while charging a higher interest rate than another lender.
Over several years, additional interest can outweigh the value of avoiding an upfront fee.
This is why APR and total repayment should be part of every comparison.
1. Compare APR, Not Just the Origination Fee
The first step when comparing a personal loan with no origination fee is checking the annual percentage rate.
What is APR?
The annual percentage rate, or APR, measures the annualized cost of credit and includes the interest rate plus certain finance charges associated with making the loan.
The CFPB explains that the interest rate is the price charged for borrowing principal, while APR incorporates the interest rate plus additional lender fees that are included in the APR calculation.
Review the official CFPB explanation of interest rate vs APR.
Why APR makes comparisons easier
Suppose two lenders offer the same loan amount and term:
| Feature | Offer A | Offer B |
|---|---|---|
| Origination Fee | $0 | $400 |
| Interest Rate | Higher | Lower |
| APR | 12.5% | 10.8% |
| Best Choice? | Depends on total repayment and your actual terms | |
The no-fee option is not automatically cheaper simply because the upfront fee is zero.
APR does not include every possible future cost
A personal loan with no origination fee may still involve charges that are not part of the APR in every circumstance.
Examples can include:
- late-payment fees;
- returned-payment fees;
- optional insurance products;
- or other conditional costs.
Read the actual disclosures and agreement rather than relying on the headline APR alone.
2. Calculate Monthly Payment and Total Repayment
The second check for a personal loan with no origination fee is whether both the monthly payment and total repayment make financial sense.
Monthly payment is only one number
A lender can make a payment appear more affordable by extending the repayment term.
For example, a five-year loan usually has a lower monthly payment than a three-year loan with the same principal and APR.
However, keeping the debt outstanding longer can increase total interest.
Compare identical loan amounts
When comparing offers, keep the requested amount consistent.
Record:
- loan amount;
- net proceeds;
- APR;
- term;
- monthly payment;
- total number of payments;
- and total repayment.
Example
| Feature | Offer A | Offer B |
|---|---|---|
| Loan Amount | $10,000 | $10,000 |
| Origination Fee | $0 | $0 |
| Term | 36 months | 60 months |
| APR | 10% | 12% |
| Monthly Payment | Higher | Lower |
| Total Interest | Lower | Higher |
This illustrates why a lower monthly payment can still create a more expensive loan.
For more on repayment structures, see our personal loan rates and repayment guide.
3. Review Other Personal Loan Fees
Even a personal loan with no origination fee can have other costs.
Late-payment fees
Check whether the lender charges a fee when a scheduled payment is not received by the required date.
Review any grace period and the exact amount or calculation method.
Returned-payment fees
A failed bank withdrawal or returned check can result in another charge depending on the lender and applicable law.
Documentation or administrative charges
CFPB guidance notes that documentation fees can exist on personal installment loans.
If a lender advertises no origination fee, verify whether any other required processing or documentation charges are still imposed.
Optional products
Products such as credit insurance may be optional rather than required.
Determine:
- whether the product is optional;
- how much it costs;
- whether it is financed into the loan;
- and how cancellation works.
Prepayment provisions
Review the contract to determine whether there is any cost associated with repaying the balance early.
Do not assume all lenders follow identical policies.
4. Review Loan Term, Funding Speed, and Flexibility
A personal loan with no origination fee should also fit your timing and cash-flow needs.
Funding speed
Some lenders advertise fast funding, but actual timing may depend on:
- identity verification;
- income verification;
- bank information;
- credit review;
- and when the application is completed.
Do not make a time-sensitive financial commitment based solely on an advertised “same-day” claim.
Fixed monthly payments
Many personal installment loans use fixed scheduled payments.
A predictable payment can make budgeting easier, but affordability should still be tested against your existing obligations.
Payment-date flexibility
Some lenders allow eligible borrowers to change a payment due date; others do not.
Check the policy before assuming this flexibility exists.
Hardship assistance
If losing income would make repayment difficult, ask whether the lender maintains any hardship options.
Availability and eligibility can vary substantially.
For broader budgeting guidance, read our Master Your Money guide.
5. Check Eligibility Before a Full Application
Another important consideration when shopping for a personal loan with no origination fee is how the application affects your credit.
Credit score requirements differ
There is no single minimum credit score that applies to every personal lender.
Lenders can also consider:
- income;
- existing debt;
- credit history;
- recent applications;
- employment or income stability;
- and other underwriting criteria.
Read our credit score calculation guide for background on common scoring factors.
Soft inquiry vs hard inquiry
The CFPB explains that a hard inquiry usually occurs when you formally apply for new credit and can affect your credit score.
A soft inquiry does not affect your credit score.
See the official CFPB credit inquiry guidance.
Prequalification can help comparison shopping
Some lenders allow consumers to explore potential terms using a soft inquiry.
However, the words “prequalified” and “preapproved” are not used consistently across every lender.
A preliminary result is not the same as a guaranteed final approval.
Confirm the inquiry type before proceeding
Before entering sensitive information, ask:
- Will this step create a soft inquiry?
- Will a hard inquiry occur?
- At what stage is the hard inquiry performed?
A lender typically runs a hard credit check when you formally apply for consumer credit.
6. Decide Whether Debt Consolidation Actually Saves Money
A personal loan with no origination fee can be used for debt consolidation if permitted by the lender.
But moving several balances into one loan only helps when the numbers improve your overall position.
Calculate your existing cost
List each existing debt and record:
- balance;
- APR;
- minimum payment;
- estimated payoff period;
- and current monthly payment.
Compare the new loan
Then compare the proposed consolidation loan’s:
- APR;
- term;
- monthly payment;
- fees;
- and total repayment.
Watch for a longer term
A lower payment may simply mean the debt has been extended over more years.
For example, moving credit-card debt into a five-year installment loan may improve monthly cash flow but still cost more if the new term is substantially longer.
Avoid rebuilding card balances
Debt consolidation becomes less effective if paid-off credit cards are immediately used to accumulate new balances.
For context on revolving balances, see our average credit card debt guide.
7. Verify the Lender and Read the Final Agreement
Before accepting a personal loan with no origination fee, confirm that you are dealing with a legitimate lender and understand the final contract.
Check the lender’s identity
Verify:
- official company website;
- physical or registered address;
- customer-service contact details;
- and applicable state registration or licensing information.
Read Truth in Lending disclosures
Federal Regulation Z implements the Truth in Lending Act for covered consumer credit, including installment loans.
Important disclosures can include information such as APR and finance charges.
See the official CFPB Regulation Z resource.
Beware of guaranteed-approval scams
The Federal Trade Commission warns consumers about advance-fee loan scams in which someone promises credit regardless of credit history and then demands payment before delivering the loan.
A legitimate lender may have lawful application-related charges in some contexts, but paying someone simply because they promise guaranteed credit is a major warning sign.
Review the FTC advance-fee loan scam guidance.
Watch for unexpected loan texts
The FTC has also warned in 2026 about fake loan text messages claiming that an application or approval already exists.
If you did not apply, do not provide Social Security numbers, bank details, or other personal information in response.
How to Compare a Personal Loan With No Origination Fee
The easiest way to compare a personal loan with no origination fee is to create a simple side-by-side table.
| Factor | Lender A | Lender B | Lender C |
|---|---|---|---|
| Loan Amount | Compare | Compare | Compare |
| Origination Fee | $0 | $0 | Compare |
| APR | Compare | Compare | Compare |
| Term | Compare | Compare | Compare |
| Monthly Payment | Compare | Compare | Compare |
| Total Repayment | Compare | Compare | Compare |
| Other Fees | Compare | Compare | Compare |
| Net Proceeds | Compare | Compare | Compare |
This prevents one attractive feature from dominating the decision.
Using Personal Loan Comparison Sites Carefully
Comparison websites can help you discover potential lenders, but they do not all operate the same way.
Determine what the website actually is
A site may be:
- a direct lender;
- a broker;
- a marketplace;
- or a lead-generation service.
These differences affect who receives your information and who ultimately makes the loan.
Read privacy policies
Before entering your phone number, email, income, or other sensitive information, determine whether your information may be shared with multiple companies.
Verify terms on the lender’s official site
A comparison site may display an estimate or “rates from” figure.
Your final offer may change after underwriting.
The official loan documents—not a search result—control the actual agreement.
When a No-Origination-Fee Loan May Be a Good Choice
A personal loan with no origination fee may be particularly attractive when:
- its APR is competitive;
- you need the full approved amount;
- the repayment term fits your budget;
- there are no problematic additional fees;
- and the total repayment compares favorably with alternatives.
When Another Loan Could Be Better
A loan that charges an origination fee could still be financially preferable if its APR and total repayment are substantially lower.
Consider the complete transaction rather than rejecting every lender that charges a fee.
Personal Loan vs Secured Loan
Most standard personal loans are unsecured, meaning the borrower does not pledge a specific asset as collateral.
A secured loan may require collateral but can have different pricing or eligibility criteria.
See our secured personal loan guide and secured vs unsecured comparison.
Personal Loan vs Credit Card
A personal loan with no origination fee can have a fixed repayment schedule, while a credit card generally provides revolving credit.
Personal installment loan
- Fixed borrowing amount.
- Defined repayment period.
- Typically fixed scheduled payments.
- Account generally closes when repaid.
Credit card
- Revolving credit limit.
- Balance can be repeatedly borrowed and repaid.
- Payment varies with balance and account terms.
- Rates may be variable.
Neither option is automatically better. Compare the actual APR, fees, payment structure, and intended use.
Questions to Ask Before Accepting a Personal Loan
- Is there an origination fee?
- What is the APR?
- What is the stated interest rate?
- What amount will I actually receive?
- What is my monthly payment?
- How many payments will I make?
- What is the total repayment?
- Are there late-payment fees?
- Are there returned-payment fees?
- Does early repayment create any charge?
- Are optional insurance products included?
- Can I change my payment date?
- Does the lender offer hardship assistance?
- Will prequalification affect my credit score?
- When will a hard inquiry occur?
- How quickly are funds normally delivered?
- Does the final agreement match the advertised terms?
Common Mistakes to Avoid
Assuming no origination fee means free borrowing
Interest remains a borrowing cost even when the origination charge is zero.
Choosing only by monthly payment
A long term can hide a much higher total repayment amount.
Ignoring APR
Compare APR along with the interest rate and other disclosed costs.
Submitting applications without understanding credit inquiries
Determine whether you are requesting a preliminary estimate or completing a formal credit application.
Ignoring loan documents
An advertisement does not replace the final contract.
Paying a scammer for guaranteed approval
Do not send money simply because someone promises that a loan is guaranteed regardless of your credit history.
Related Best Finance Live Guides
- How to Get a Personal Loan
- Personal Loan Rates
- Personal Loans for Bad Credit
- Secured Personal Loans
- Secured vs Unsecured Personal Loans
- Personal Loan for Moving Expenses
- What Is a Finance Charge?
- How Is a Credit Score Calculated?
- Highest Credit Score Guide
- Average Credit Card Debt
- Master Your Money
- Complete Personal Finance Guide
- Top Financial Tips
- Personal Finance Course
- Best Finance Live Guide
- Business Loans Guide
- Business Loan Interest Rates
- Business Loan Payment Calculator
- First Time Business Loan
- Unsecured Small Business Loans
- What Is Business Finance?
Conclusion
A personal loan with no origination fee can be a strong option when its APR, repayment term, monthly payment, and total cost are competitive.
However, the absence of one upfront charge does not prove that the loan is cheaper than every alternative.
Compare APR, net proceeds, monthly payments, total repayment, late and returned-payment fees, credit requirements, funding time, and contract flexibility.
If you plan to use a personal loan with no origination fee for debt consolidation, calculate whether the new APR and repayment schedule actually improve your financial position rather than simply lowering the monthly payment.
Finally, verify the lender and read the Truth in Lending disclosures and final agreement before signing. The strongest loan is the one whose full cost and repayment obligations fit your budget—not simply the offer with the most attractive marketing label.