Learning how to Master Your Money is one of the most valuable financial skills you can develop. Whether you are starting your first job, building a family, managing debt, increasing your income, or preparing for retirement, better money management can help you make more confident financial decisions.
To Master Your Money, you do not need a perfect income or a complicated investment strategy. You need a practical system for budgeting, saving, borrowing, investing, and reviewing your financial goals as your life changes.
The right personal finance tips can help you understand where your money goes, prepare for emergencies, reduce unnecessary debt, and build long-term financial security. If you want a broader introduction, start with our complete personal finance guide.
This guide explains how to Master Your Money during every major stage of adult life and shows which financial priorities deserve attention as your responsibilities evolve.
7 Core Steps to Master Your Money
Before looking at different life stages, focus on seven principles that can help you Master Your Money throughout adulthood.
- Create a realistic spending plan.
- Build an emergency reserve.
- Use credit and debt carefully.
- Protect your credit history.
- Save and invest consistently when possible.
- Protect your income and assets with appropriate insurance.
- Review your financial plan regularly.
These principles form the foundation of effective money management. Your priorities may change, but these seven areas remain relevant throughout most stages of financial life.
Why It Is Important to Master Your Money
When you learn to Master Your Money, you gain more control over decisions involving housing, transportation, borrowing, savings, retirement, insurance, and major purchases.
A strong financial system can help you:
- understand your income and expenses;
- reduce financial surprises;
- prepare for unexpected costs;
- avoid unnecessary high-interest debt;
- work toward short- and long-term goals;
- save for retirement;
- and make major financial decisions more carefully.
The Consumer Financial Protection Bureau provides educational tools for budgeting, saving, credit, and financial planning. You can explore the CFPB consumer financial resources for additional guidance.
Building financial confidence does not happen overnight. The goal is to develop habits that make it easier to Master Your Money over time.
Stage 1: Master Your Money in Early Adulthood
Early adulthood is often the first stage where you manage your own rent, transportation, credit cards, student debt, insurance, and savings.
This stage is an important opportunity to Master Your Money before financial responsibilities become more complex.
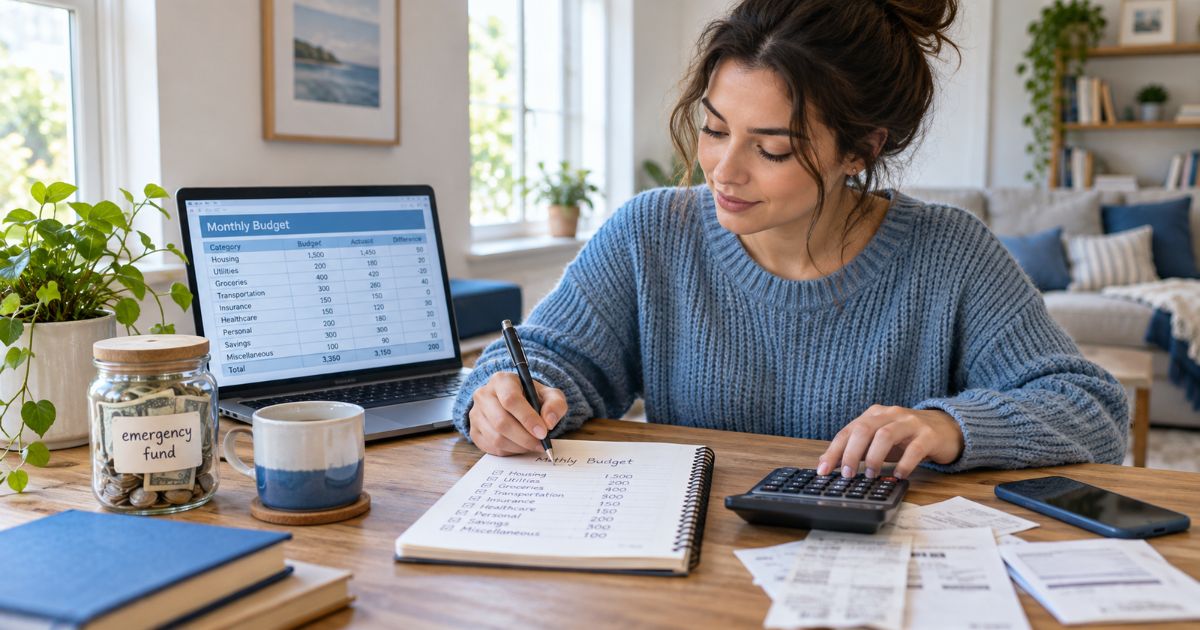
Create a monthly budget
Start by listing your after-tax income and separating spending into essential expenses, flexible expenses, debt payments, and savings.
Typical categories include:
- rent or housing;
- utilities;
- food;
- transportation;
- insurance;
- minimum debt payments;
- subscriptions;
- personal spending;
- and savings.
A good budget does not eliminate every enjoyable purchase. Instead, it helps you understand whether your spending supports your goals.
For additional budgeting ideas, review our top financial tips and personal finance course guide.
Build an emergency fund
An emergency fund can help you Master Your Money by reducing the need to rely on expensive credit when an unexpected expense occurs.
Emergency savings may be useful for:
- urgent car repairs;
- temporary job loss;
- medical expenses;
- home repairs;
- unexpected travel;
- or an unplanned move.
There is no single emergency-fund target that works for everyone. Your goal should reflect your monthly expenses, job stability, insurance coverage, household responsibilities, and access to other financial resources.
Learn how credit works
Using credit carefully is another important part of learning to Master Your Money.
Before taking out a loan or using a credit card balance, understand:
- interest rate;
- APR;
- fees;
- minimum payment;
- repayment term;
- and total borrowing cost.
Our guide on finance charges on loans explains how interest and fees affect the real cost of borrowing.
You can review your credit reports through AnnualCreditReport.com.
Start retirement saving when practical
Starting early can give retirement savings more time to potentially grow. However, your contribution level should fit your actual budget, debt situation, emergency savings, and employer benefits.
If your employer offers a retirement plan, review whether matching contributions are available.
Contribution limits can change, so use current IRS retirement plan guidance rather than relying on old limits.
Stage 2: Master Your Money During Career and Family Growth
As your career progresses, your income may increase, but your financial responsibilities may increase as well.
Marriage, children, housing, transportation, healthcare, and larger financial goals can all make it more important to Master Your Money with a structured plan.
Update your budget after major life changes
Review your budget when you experience changes such as:
- a new job;
- a raise;
- marriage;
- having children;
- moving;
- buying a home;
- or taking on new debt.
If relocation creates a short-term cash problem, read our guide on using a personal loan for moving expenses before deciding whether borrowing makes sense.
Control lifestyle inflation
One challenge during higher-income years is allowing expenses to rise as quickly as income.
A salary increase can be used not only to improve your lifestyle but also to increase savings, repay debt, and work toward important goals.
Learning to Master Your Money means deciding intentionally how additional income will be used instead of automatically increasing spending.
Compare personal loans carefully
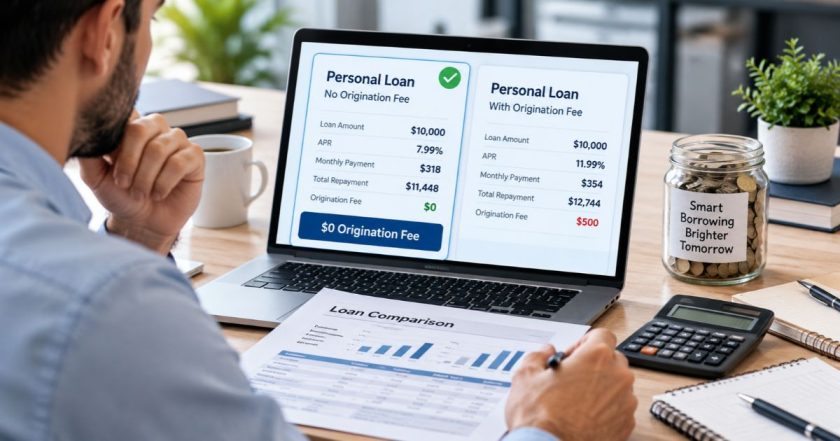
If you need financing, do not select a personal loan based only on the monthly payment.
Review:
- APR;
- interest rate;
- fees;
- loan term;
- monthly payment;
- and total repayment.
Our guide on how to get a personal loan explains the application process, while our personal loan rates guide covers important comparison factors.
If your credit profile is challenging, also review personal loans for bad credit.
Review insurance coverage
Protecting against large financial losses is another part of learning to Master Your Money.
Depending on your situation, review:
- health insurance;
- auto insurance;
- homeowners or renters insurance;
- life insurance;
- disability coverage;
- and liability protection.
Insurance needs can change when other people depend on your income.
Set measurable financial goals
Instead of saying “I want to save more,” choose specific goals.
Examples include:
- building a defined emergency fund;
- paying off a specific credit-card balance;
- saving toward a home;
- increasing retirement contributions;
- building education savings;
- or creating business startup capital.
Specific goals make it easier to measure whether your efforts to Master Your Money are actually producing results.
Stage 3: Master Your Money During Peak Earning Years
Your 40s and 50s may include some of your strongest earning years, but this stage can also bring high expenses.
You may be balancing mortgage payments, children, education, healthcare, aging parents, debt, and retirement planning.
Increase retirement planning
Review your retirement accounts and ask whether your current savings rate still supports your goals.
Consider:
- current retirement account balances;
- years until retirement;
- expected living expenses;
- Social Security estimates;
- pensions;
- and investment allocation.
Current retirement contribution and catch-up rules are available through the IRS retirement plans section.
Diversify investments
Learning to Master Your Money also means understanding that investment returns are not guaranteed.
Diversification can reduce some investment risks by spreading money across different assets rather than depending too heavily on one company, industry, or asset type.
Investor.gov provides educational guidance on asset allocation and diversification.
Reduce expensive debt
High-interest debt can consume money that could otherwise support savings or retirement goals.
Review debts according to:
- interest rate;
- remaining balance;
- minimum payment;
- repayment term;
- and whether collateral is involved.
If you are considering secured borrowing, read our secured personal loan guide to understand collateral risk.
Review estate planning
Estate planning may include:
- a will;
- beneficiary designations;
- power of attorney;
- healthcare directives;
- trust arrangements;
- and account ownership.
As your assets and family responsibilities increase, estate planning can become an important part of efforts to Master Your Money.
Stage 4: Master Your Money Before Retirement
As retirement approaches, financial planning begins to shift from primarily accumulating assets to understanding income, withdrawals, healthcare, taxes, and investment risk.
Estimate retirement spending
Estimate likely retirement costs rather than assuming your expenses will automatically fall.
Include:
- housing;
- food;
- transportation;
- healthcare;
- insurance;
- travel;
- taxes;
- home maintenance;
- and family support.
This calculation helps you Master Your Money by showing whether projected retirement resources are consistent with your expected lifestyle.
Understand Social Security claiming decisions
The age at which Social Security retirement benefits are claimed can affect the monthly benefit amount.
Waiting longer may increase monthly benefits up to the applicable maximum delayed-retirement age, but waiting is not automatically the best choice for everyone.
Use official Social Security Administration retirement resources to review current rules and estimates.
Prepare for healthcare costs
Healthcare can represent a significant retirement expense.
Review Medicare enrollment periods, premiums, deductibles, coverage options, and out-of-pocket costs through Medicare.gov.
Review investment risk
Approaching retirement does not automatically mean eliminating investment exposure.
Instead, determine how much volatility your plan can tolerate while still maintaining enough growth potential for a retirement that may last many years.
Stage 5: Master Your Money During Retirement
Retirement creates a new money-management challenge because employment income may be replaced by several different income sources.
These may include Social Security, pensions, retirement accounts, investment accounts, savings, and other income.
Create a sustainable withdrawal plan
Learning to Master Your Money in retirement means balancing current spending with the need to preserve resources for future years.
Your withdrawal strategy may depend on:
- portfolio value;
- investment returns;
- inflation;
- retirement duration;
- taxes;
- healthcare costs;
- and other income sources.
The commonly discussed 4% rule may provide a planning reference, but it is not a guarantee that savings will last for every retiree.
Monitor spending
Track essential and discretionary spending throughout retirement.
A retirement budget should support your quality of life while helping prevent withdrawals from becoming unsustainable.
Continue reviewing investments
Some retirees may still need investment growth to help maintain purchasing power during a long retirement.
Investment allocation should be reviewed alongside withdrawal needs, not as a completely separate decision.
Keep estate documents updated
Review beneficiaries, wills, powers of attorney, trusts, and healthcare documents after major family or financial changes.
Keeping these documents current is another important way to Master Your Money during later life.
Master Your Money by Managing Debt Carefully
Debt can be useful when it supports a necessary purchase and the repayment fits comfortably within your budget. However, borrowing can also become expensive when the interest rate or repayment period is high.
To Master Your Money, compare every loan using:
- loan amount;
- APR;
- interest rate;
- fees;
- monthly payment;
- repayment term;
- total repayment;
- and collateral requirements.
For additional information, read our guides on getting a personal loan, personal loan rates, and secured personal loans.
Master Your Money Before Major Purchases
Major purchases can affect your monthly cash flow for years, particularly when financing is involved.
Vehicle financing is a good example. A lower monthly payment may look attractive, but a longer repayment term can increase total borrowing costs.
Use our auto finance calculator guide to understand estimated vehicle payments.
If you are purchasing your first financed vehicle, review our first-time auto loan guide.
If you already have a vehicle loan, our refinance auto loan guide explains when refinancing may or may not help.
Borrowers considering very long vehicle terms should also read our guide to a 96-month auto loan.
Master Your Money When Starting or Running a Business
Business decisions can affect personal financial security, especially when personal savings or guarantees are involved.
Entrepreneurs should separate business and household finances as much as practical and carefully evaluate borrowing costs.
Start with our business finance guide and how to succeed in business finance.
If your business needs financing, compare different business loan options and review business loan interest rates.
New business owners with limited cash should also understand the risks discussed in our guide on startup business loans with no money.
Common Mistakes That Make It Harder to Master Your Money
Not tracking spending
You cannot easily improve financial habits if you do not know where your money is going.
Increasing spending every time income rises
Higher income can create opportunities to increase savings and reduce debt, but those opportunities disappear when every raise immediately becomes higher spending.
Ignoring emergency savings
Without available cash, even a relatively small emergency may need to be financed through high-cost credit.
Choosing loans based only on monthly payment
A low monthly payment can hide a longer repayment term and higher total interest.
Following investment hype
Do not make investment decisions solely because an asset is popular on social media or because someone promises unusually high returns.
Never reviewing your plan
Your financial needs change. To Master Your Money successfully, review your plan after major life events and periodically even when nothing dramatic has changed.
Annual Checklist to Master Your Money
A simple yearly financial review can help you stay organized.
At least once each year, consider checking:
- your monthly budget;
- emergency savings;
- credit reports;
- high-interest debt;
- retirement contributions;
- investment allocation;
- insurance coverage;
- beneficiary designations;
- tax planning needs;
- financial goals;
- and major upcoming expenses.
Continuing your financial education can also make it easier to Master Your Money. Explore our personal finance course guide, personal finance books, and financial freedom guide.
Final Thoughts: Master Your Money One Decision at a Time
You do not need to fix every financial issue at once. The most effective way to Master Your Money is to make consistent improvements over time.
Start by understanding your spending and cash flow. Build emergency savings where possible, use credit carefully, review borrowing costs before taking on debt, and save toward future goals.
As your life changes, your financial priorities should change too. Early adulthood may focus on budgeting, credit, and emergency savings. Career-building years may involve housing, family protection, and larger goals. Peak earning years may place greater emphasis on retirement and debt reduction, while retirement requires careful income and withdrawal management.
Learning to Master Your Money is not about becoming perfect with finances. It is about creating a flexible system that helps you make better decisions today while protecting your options for tomorrow.
For more guidance, continue with our complete personal finance guide, financial tips guide, or personal finance course guide.