Driveway Finance can help vehicle shoppers arrange financing online and manage an existing auto loan through Driveway’s digital tools. However, it is important to understand the difference between Driveway, the vehicle-shopping platform, and Driveway Finance Corporation, commonly called DFC.
Driveway Finance Corporation is an indirect auto lender based in Southern Oregon and serves as the primary lender for Lithia Motors and Lithia-owned dealer groups. Driveway itself can also present financing offers from lending partners when a customer applies while purchasing a vehicle.
This updated guide explains how Driveway Finance works, what prequalification means, how credit affects financing, how DFC customers make payments, which online account tools are available, and what borrowers should check before signing an auto loan.
For broader vehicle-finance guidance, also see our car finance options guide, auto finance calculator, and good car loan APR guide.
Key Takeaways
- Driveway Finance Corporation is an indirect auto lender and the primary lender for Lithia and Driveway.
- Driveway can also present financing offers from multiple lending partners during the vehicle-buying process.
- Prequalification can provide an estimated borrowing range without affecting your credit score.
- A full credit application is different from prequalification and can involve lender underwriting.
- My Driveway provides online loan-management and payment tools for eligible DFC customers.
- Credit score is only one factor lenders can consider.
- Borrowers should compare APR, term, amount financed, monthly payment and total cost before signing.
1. What Is Driveway Finance?
Driveway Finance is commonly used to describe vehicle financing available through the Driveway ecosystem.
There are two closely related concepts consumers should understand:
- Driveway is an online and dealership-connected vehicle shopping platform.
- Driveway Finance Corporation is an indirect auto finance company that provides vehicle loans.
DFC’s official website identifies it as the primary lender for Lithia Motors and Lithia-owned dealer groups.
The company was originally established in 2012 as Southern Cascades Finance Corporation and later became Driveway Finance Corporation.
For current company information, see the official Driveway Finance Corporation website.
Is Driveway Finance a lender?
Driveway Finance Corporation is a lender.
Driveway’s broader vehicle-shopping platform can also work with lending partners to present customers with financing offers.
This distinction matters because the creditor named in your final retail installment contract controls the actual loan terms.
2. How Driveway Vehicle Financing Works
Vehicle buyers using Driveway can select a vehicle and apply for financing online.
Driveway’s current financing information says customers may receive multiple personalized offers from lending partners after completing the relevant application process.
Step 1: Find a vehicle
Start by selecting a vehicle that fits your budget rather than simply focusing on the maximum amount a lender may approve.
Compare:
- vehicle price;
- taxes and registration;
- delivery or dealer charges;
- insurance;
- maintenance;
- and expected financing cost.
Step 2: Review prequalification
Driveway currently offers a prequalification option intended to help shoppers estimate how much they may be able to borrow.
The company states that this prequalification process does not affect the customer’s credit score.
Step 3: Submit a full credit application
After selecting a vehicle, customers can complete the financing application and provide the information required by participating lenders.
Step 4: Review financing offers
Driveway states that customers may receive multiple personalized offers from lending partners.
Compare each offer using the same vehicle transaction.
Step 5: Review the final contract
Before accepting financing, confirm:
- creditor name;
- APR;
- interest rate;
- amount financed;
- finance charge;
- term;
- monthly payment;
- total of payments;
- and any optional products.
Our finance charge guide explains these cost figures in more detail.
3. Driveway Finance Prequalification
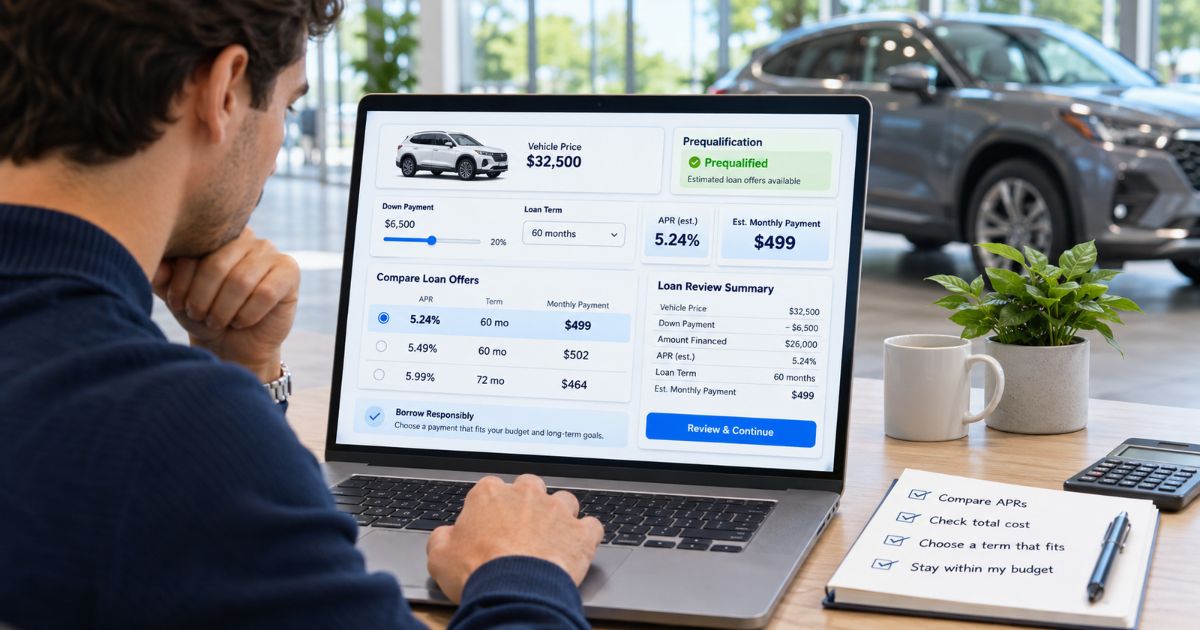
Prequalification is one of the more useful Driveway Finance tools for shoppers who want an estimated financing range before committing to a vehicle.
What prequalification can show
Driveway says prequalification can provide a general idea of:
- potential borrowing amount;
- possible financing terms;
- estimated rates;
- and expected monthly-payment range.
Does prequalification hurt your credit?
Driveway currently states that its prequalification process does not affect your credit score.
This is different from a formal credit application.
Prequalification is not final approval
A preliminary result does not guarantee that a lender will approve the final application under identical terms.
Final underwriting can depend on:
- income verification;
- credit information;
- existing debt;
- vehicle details;
- amount financed;
- and lender-specific requirements.
See Driveway’s official Driveway Finance Corporation information page for current prequalification information.
4. Credit Scores and Driveway Auto Financing
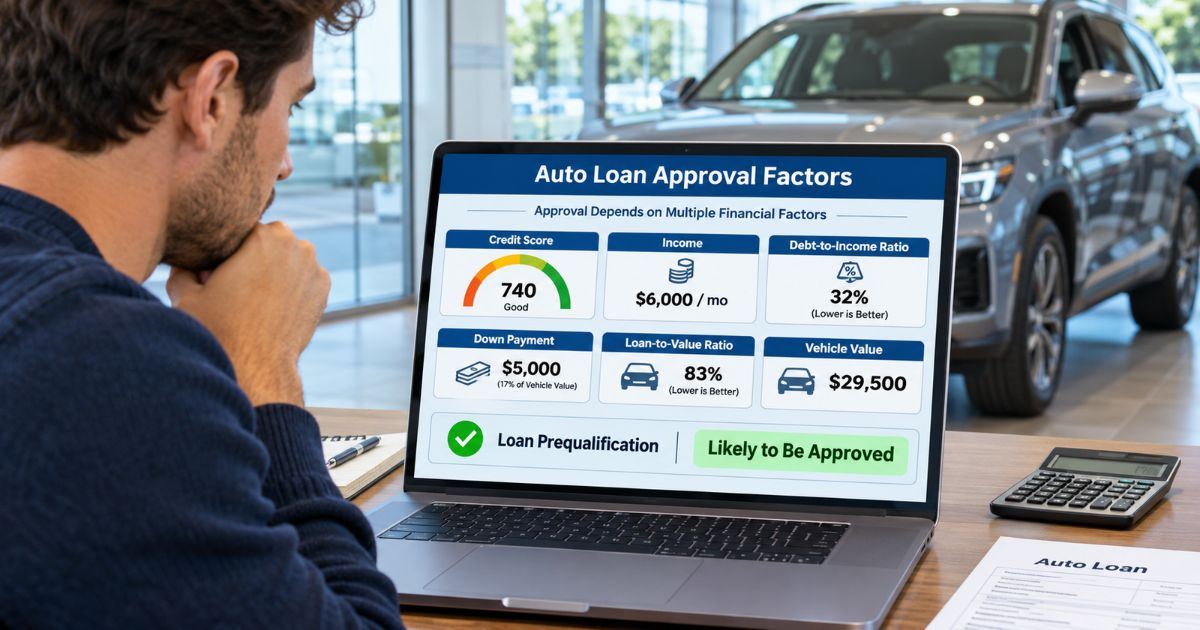
Credit history can influence Driveway Finance approval and pricing, but credit score is not the only factor lenders may consider.
Driveway states that customers are not restricted from submitting a credit application simply because of a particular score.
Factors lenders may review
Depending on the lender, underwriting may consider:
- credit score;
- payment history;
- income;
- employment;
- existing debts;
- housing costs;
- down payment;
- vehicle value;
- and loan-to-value ratio.
There is no universal minimum credit score
Do not assume a specific number automatically guarantees approval or rejection.
Driveway’s current information specifically says its lending partners consider multiple factors and review individual situations.
For more information, see our credit score calculation guide, credit score range guide, and credit improvement guide.
5. Driveway Finance Interest Rates and APR
There is no single Driveway Finance APR that applies to every borrower.
Driveway Finance Corporation describes its programs as competitive, but actual pricing depends on the specific application and loan.
What affects an auto loan APR?
Potential factors include:
- credit profile;
- vehicle age;
- new versus used status;
- loan term;
- down payment;
- amount financed;
- loan-to-value ratio;
- and lender pricing.
Compare APR, not just the monthly payment
A long loan term can make an expensive loan appear affordable.
For example:
| Feature | Shorter Loan | Longer Loan |
|---|---|---|
| Monthly Payment | Higher | Lower |
| Total Interest | Usually lower | Usually higher |
| Time in Debt | Shorter | Longer |
| Negative Equity Risk | Generally lower | Generally higher |
Use our good APR for a car loan guide, new vs used car rate guide, and long-term auto loan guide when comparing terms.
6. Down Payment and Amount Financed
A down payment can reduce the amount you need to borrow.
Potential benefits of a larger down payment
- Lower amount financed.
- Lower monthly payment.
- Less total interest if other terms stay the same.
- Lower loan-to-value ratio.
- Lower negative-equity risk.
Zero down is not universally guaranteed
The previous version of this article suggested that Driveway financing could routinely range from zero down to large down payments.
A more accurate approach is to review the terms of the actual financing offers presented to you.
Down-payment requirements vary according to the transaction and lender.
Keep emergency savings
A larger down payment can improve a loan structure, but do not leave yourself unable to cover:
- insurance deductibles;
- repairs;
- maintenance;
- registration;
- or household emergencies.
Our money-management guide can help with this tradeoff.
7. Managing a Driveway Finance Corporation Loan
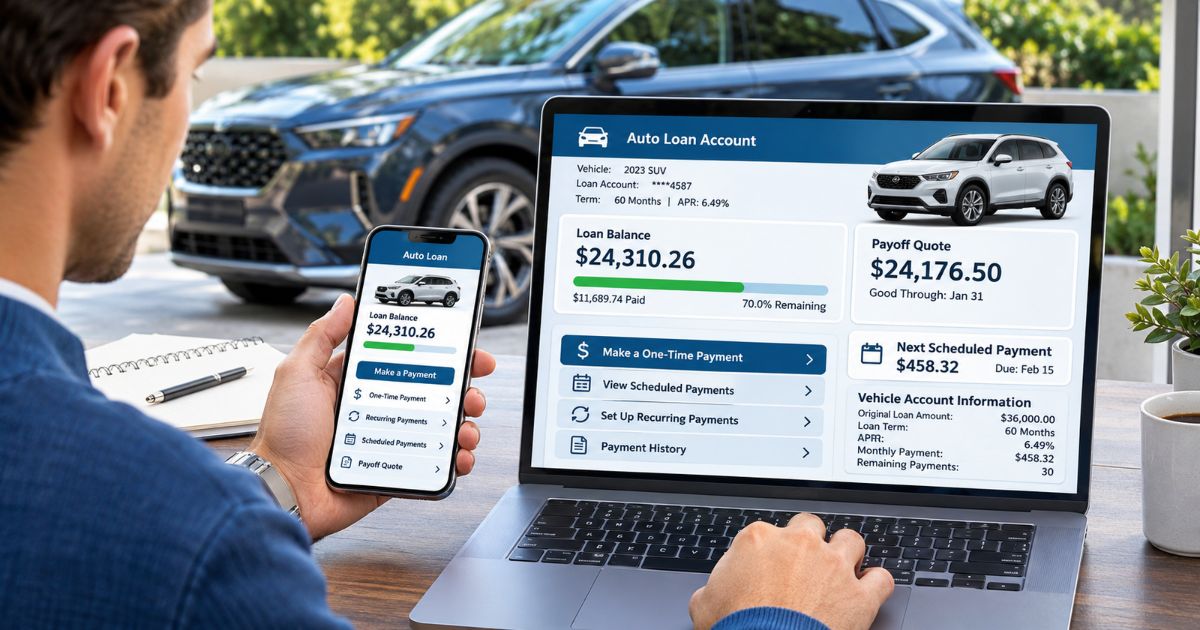
Existing Driveway Finance Corporation customers can manage eligible loan functions through My Driveway.
Driveway currently describes My Driveway as an all-in-one vehicle ownership and loan-management platform.
Current account-management features
The official Driveway site lists features including:
- secure account login;
- Single Sign-On technology;
- Multi-Factor Authentication;
- one-time payments;
- scheduled payments;
- recurring payments;
- balance tracking;
- payoff quote downloads;
- personal-information management;
- vehicle information;
- service-center access;
- maintenance scheduling;
- protection-plan information;
- and vehicle trade or sale tools.
My Driveway is more than a payment portal
The platform connects vehicle ownership and account-management tools in one account experience.
This is different from the previous article’s broad claim that every part of financing, refinancing, leasing, and specialty loans was necessarily offered through the same system.
How to Make a Driveway Finance Payment
Driveway currently lists two core payment methods for a DFC loan.
1. My Driveway
Customers can make an online payment through their My Driveway account.
2. Mail
DFC also accepts qualifying mailed payments using a cashier’s check, money order, or personal check with the payment coupon from the monthly statement.
Use the current official instructions on Driveway’s payment FAQ before mailing money because payment addresses can change.
ACH payments
Driveway Finance Corporation also publishes ACH payment terms for electronic bank-account debits.
Make sure sufficient funds are available because returned or failed payments can have consequences under the account terms.
Driveway Finance Recurring Payments
My Driveway currently supports one-time, scheduled, and recurring payment options.
Benefits of recurring payments
Automatic recurring payments can reduce the risk of forgetting a due date.
However, you should still:
- review statements;
- confirm payments were processed;
- keep sufficient funds available;
- and monitor the account for changes.
Do not rely on autopay without checking
A changed bank account, insufficient balance, or processing problem can result in a failed transaction.
Always verify successful payment posting.
Driveway Finance Payment History
Borrowers sometimes need a formal payment-history document for financial records or another lender.
Driveway currently states that a DFC representative can generate payment history and send it by email or postal mail upon request.
This means customers should not assume every historical document is automatically downloadable from the portal.
Use Driveway’s current payment-history guidance for instructions.
Driveway Finance Payoff Quote
My Driveway currently includes a payoff-quote feature.
Why a payoff quote matters
The account balance shown on a normal statement may not always equal the exact amount needed to satisfy the loan on a particular date.
A payoff quote can account for:
- remaining principal;
- accrued interest;
- date-specific calculations;
- and other applicable contractual amounts.
Use payoff information when selling or refinancing
If you plan to sell, trade, or refinance the vehicle, obtain a current payoff figure first.
See our selling a financed car guide, refinance auto loan guide, and early payoff guide.
Does Driveway Finance Offer Refinancing?
The previous article stated broadly that Driveway Finance automatically allows refinancing through its platform.
That claim should not be made without a current specific refinance product or offer.
If you already have a DFC loan and want different terms, obtain your current payoff quote and compare lenders that specifically offer auto refinancing.
Potential reasons to refinance elsewhere
- Your credit improved.
- Your income became more stable.
- Market rates declined.
- Your debt-to-income ratio improved.
- Your current APR is high compared with available alternatives.
Always compare the new term and total remaining cost—not just the new monthly payment.
Does Driveway Finance Offer Balloon Loans?
The old article described balloon-payment loans as a standard Driveway product.
Current public Driveway and DFC information reviewed for this update does not support presenting balloon financing as a standard universal product.
Only describe a balloon payment if it actually appears in the specific financing agreement being offered to you.
Does Driveway Offer Green Auto Loans?
The previous article also described special “green loans” with favorable rates for electric and hybrid vehicles.
Current public DFC information does not support treating a dedicated green-loan program as a standard Driveway Finance feature.
Electric or hybrid vehicles may still be eligible for ordinary vehicle financing depending on the lender and transaction.
Compare the actual APR and loan terms rather than assuming an EV automatically qualifies for a special rate.
Driveway Finance vs Leasing
Financing and leasing are different vehicle-acquisition structures.
Do not assume that a Driveway Finance auto loan operates like a lease.
Auto loan
- You borrow money to purchase the vehicle.
- You make scheduled payments.
- The lender holds a lien while the loan is outstanding.
- Once the debt is satisfied and lien requirements are completed, you own the vehicle free of that loan.
Lease
- You pay for the contractual use of the vehicle.
- Mileage and condition limits can apply.
- A residual value can affect end-of-term options.
- You do not automatically own the vehicle simply because the lease term ends.
Compare any actual lease and purchase offer separately.
Driveway Finance for New and Used Cars
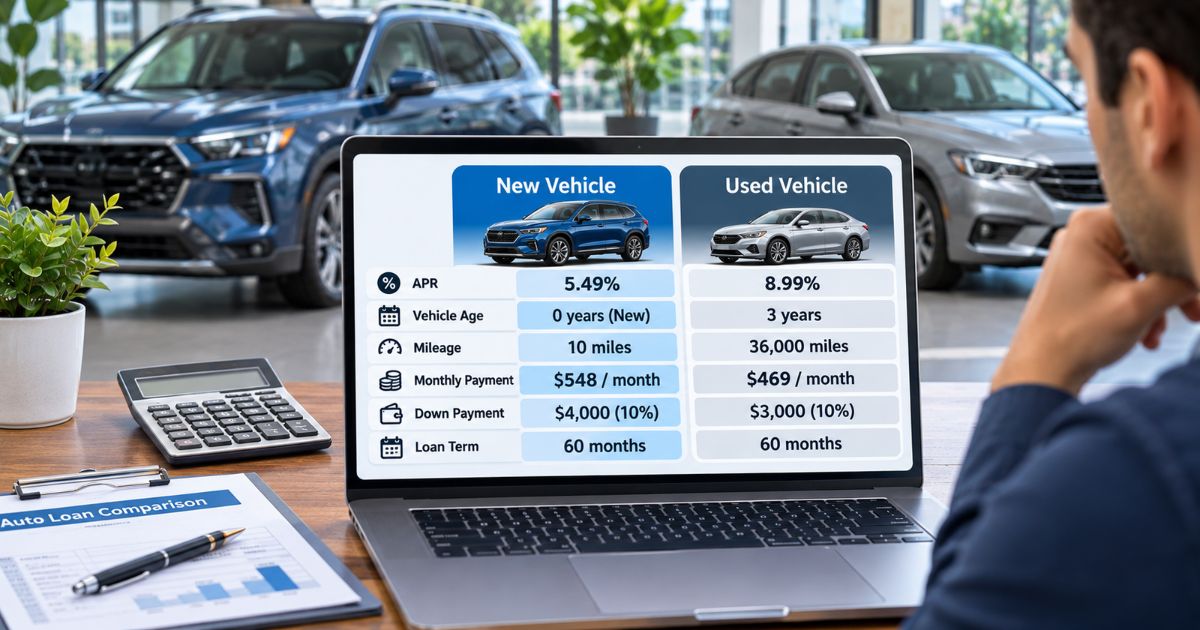
Driveway sells both new and used vehicles, and auto financing can vary according to the vehicle selected.
New vehicles
New-car financing can sometimes receive lower average market rates, particularly when manufacturer programs are available.
Used vehicles
Used vehicles frequently carry higher average rates because age, mileage, collateral value, and other factors can affect lender risk.
See our new vs used car interest rate guide for a detailed comparison.
First-Time Buyers and Driveway Financing
First-time buyers can submit applications through Driveway like other eligible consumers.
However, limited credit history can affect lender underwriting.
Prepare before applying
Consider:
- checking your credit reports;
- building a realistic monthly budget;
- saving a down payment;
- obtaining an insurance quote;
- and comparing financing options.
Our first-time auto loan guide explains these steps in more detail.
Borrower Responsibilities
After accepting a Driveway Finance loan or another vehicle finance offer, the borrower becomes responsible for following the signed contract.
Make payments on time
Late or missed payments can result in fees, negative credit reporting where applicable, collection activity, and potentially repossession after default according to the contract and state law.
Maintain required insurance
Vehicle lenders generally require specified insurance coverage while their lien remains on the vehicle.
Review your actual agreement for the coverage requirements.
Keep contact information updated
An outdated address, email, or phone number can cause you to miss account communications.
Review statements
Check:
- payment posting;
- balance;
- fees;
- due date;
- and account notices.
What Happens If You Cannot Make a Payment?
Contact Driveway Finance Corporation as soon as possible if you are concerned about missing a payment.
Do not assume a hardship option or payment extension will automatically be granted.
Why early contact matters
Waiting until several payments are missed can reduce the options available.
Ask what account-specific assistance, if any, is currently available.
Repossession risk
Default can ultimately lead to vehicle repossession according to applicable state law and the loan contract.
A repossession may not eliminate all remaining debt if the vehicle is sold for less than the amount owed plus permitted costs.
For broader information, see our subprime auto loans guide.
Driveway Finance Customer Service
Driveway Finance Corporation currently publishes customer support for existing loans.
The official contact information currently lists:
- Phone: 855-723-2669
- Business hours: Monday through Friday
- Weekend support for DFC loans: closed
Hours can change, so verify them through the official Driveway contact page before calling.
Security and My Driveway Account Access
Driveway currently states that My Driveway uses Single Sign-On and Multi-Factor Authentication technology for secure loan management.
Use the official website
Do not sign into a financial account through an unexpected email, text message, or unofficial webpage.
Use a unique password
A financial account password should not be reused on social-media, shopping, or email accounts.
Protect authentication codes
Do not share one-time security codes with unknown callers or messages.
Monitor your account
Check for:
- unexpected profile changes;
- unrecognized transactions;
- unusual payment activity;
- and suspicious login communications.
Driveway Finance vs Bank or Credit Union Financing
Before accepting a Driveway Finance offer, compare it with other sources.
| Feature | Driveway / DFC | Bank or Credit Union |
|---|---|---|
| Application | Online / integrated purchase process | Direct lender application |
| Vehicle Shopping Integration | Yes | Usually separate |
| Prequalification | Available through Driveway | Depends on lender |
| Rates | Application-specific | Application-specific |
| Best Option | Depends on the actual APR, term and total cost | |
Why comparison matters
One lender may offer:
- a lower APR;
- a shorter affordable term;
- lower fees;
- or a better total repayment amount.
Compare our affordable auto loans guide, top auto finance guide, and best finance deals guide.
Questions to Ask Before Accepting Driveway Financing
- Who is the actual lender?
- What is the vehicle’s out-the-door price?
- What is my APR?
- What is the finance charge?
- How much am I financing?
- What down payment is required?
- How long is the term?
- What is the monthly payment?
- What is the total of payments?
- Are optional products included?
- Can I pay off the loan early?
- How do I obtain a payoff quote?
- How are payments made?
- Who services the loan?
- What happens if a payment is late?
- Does the final contract match the offer I selected?
Related Best Finance Live Guides
- Auto Finance Calculator
- Best Auto Finance Deals
- Affordable Auto Loans
- What Is a Good APR for a Car Loan?
- New vs Used Car Interest Rates
- First-Time Auto Loan
- Subprime Auto Loans
- Refinance Auto Loan
- Car Finance Options
- Top Auto Finance Options
- 96-Month Auto Loan
- Paying Off a Car Loan Early
- How to Sell a Financed Car
- In-House Car Financing
- Finance Charges Explained
- How Credit Scores Are Calculated
- How Long to Raise Your Credit Score
- Highest Credit Score Guide
- Master Your Money
- CarMax Auto Finance
- CarMax Auto Finance Login
- Exeter Finance
- Capital One Auto Finance
- California Auto Finance
- Fusion Auto Finance
- Ford Financing
- Nissan Auto Finance
- Hyundai Finance Log In
- Charter One Auto Finance
- Big Motoring World Finance
- Complete Personal Finance Guide
- Top Financial Tips
Conclusion
Driveway Finance can provide a convenient way to arrange and manage vehicle financing, particularly for shoppers buying through Driveway or Lithia-affiliated dealerships.
Driveway Finance Corporation is a real indirect auto lender, while the Driveway shopping platform can also present personalized financing offers from lending partners.
Prequalification can help estimate affordability without affecting your credit score, while the full application determines the actual offers available to you.
Existing DFC customers can use My Driveway for loan-management features including payments, recurring payments, balance tracking, payoff quotes, vehicle information, and account settings.
Before accepting any offer, compare APR, amount financed, term, monthly payment, finance charge, optional products, and total cost. Convenience is valuable, but the best loan is ultimately the one that provides competitive terms and fits comfortably within your budget.