Buying a used car is only part of the decision. How you finance it can affect your monthly payment, total borrowing cost, and overall budget for years. CarMax Auto Finance is one financing source available to eligible CarMax shoppers, but it should still be compared with other available auto loan options before you sign a contract.
CarMax also works with multiple finance sources, so the financing available to a shopper may not necessarily come only from CarMax Auto Finance. Understanding pre-qualification, APR, down payments, loan terms, payments, and payoff procedures can help you make a more informed decision.
This guide explains eight practical steps for evaluating CarMax financing and managing a CarMax Auto Finance account after purchasing a vehicle.
Key Takeaways
- CarMax provides access to multiple finance sources, including CarMax Auto Finance.
- CarMax pre-qualification uses a soft credit inquiry and does not affect your credit score.
- Pre-qualification is not a final financing approval; final terms require a credit application.
- Compare APR, loan term, amount financed, monthly payment, and total cost—not just the monthly payment.
- A larger down payment can reduce the amount you need to finance, but the right amount depends on your finances.
- CarMax Auto Finance currently does not refinance its own contracts.
- Customers may refinance through another lender, subject to that lender’s requirements.
- Existing CarMax Auto Finance customers should use their actual payoff amount—not simply the principal balance—when paying off or refinancing a loan.
What Is CarMax Auto Finance?

CarMax Auto Finance, often abbreviated as CAF, is one of the finance sources available to customers purchasing vehicles through CarMax. CarMax also works with other finance sources, which means buyers may have access to financing beyond CAF.
This distinction is important. Buying a vehicle from CarMax does not necessarily mean that CarMax Auto Finance will be the lender or finance company associated with your final contract.
Before deciding how to finance any vehicle, consider the purchase price, down payment, APR, loan length, taxes and fees, and total amount you expect to repay. Our Auto Finance Center provides additional guidance on the overall vehicle-financing process.
1. Set Your Used-Car Budget Before Applying
Start with a realistic vehicle budget rather than asking how much a lender may be willing to finance. The maximum financing available to you is not necessarily the amount that fits comfortably into your finances.
Your budget should account for more than the advertised vehicle price. Depending on the purchase and your location, your total cost may include taxes, registration, applicable fees, insurance, fuel, maintenance, and financing costs.
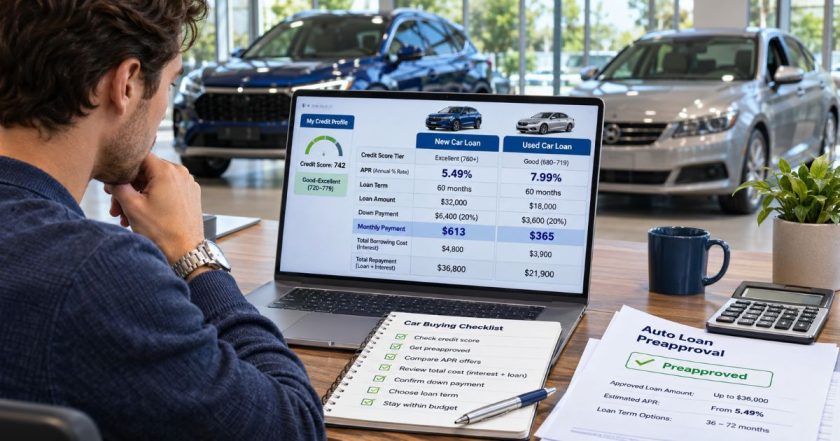
Consider both the monthly payment and the total amount you will repay. A longer loan term can make a payment appear more affordable while potentially increasing the amount of finance charges paid over time.
You can use an auto finance calculator to test different vehicle prices, down payments, APRs, and loan terms before shopping.
Do Not Build Your Budget Around the Monthly Payment Alone
A monthly payment is useful, but it does not tell you the complete cost of borrowing. Two loans can have similar payments while having different APRs, terms, or amounts financed.
Before signing, review the APR, finance charge, amount financed, total of payments, and other disclosures contained in your agreement. If you need a deeper explanation of borrowing costs, see our guide to the finance charge on a loan.
2. Use CarMax Pre-Qualification to Explore Potential Terms
CarMax allows shoppers to request pre-qualification before completing a final credit application. According to CarMax, its pre-qualification process uses a soft credit inquiry, so requesting it does not affect your credit score.
Pre-qualification can show personalized information such as a potential APR, monthly payment, down payment, and financing amount. CarMax says its pre-qualification terms are available for 30 days.
However, pre-qualification should not be confused with final approval. When you decide to move forward with a specific vehicle, a credit application is required for final financing terms, and that application involves a hard credit inquiry that may affect your credit score.
Information You May Need
CarMax says its pre-qualification request may ask for information such as:
- Personal identifying information
- Address and housing information
- Employment status
- Income information
- Social Security number
Pre-qualification can be useful for establishing a preliminary budget, but your final financing terms may differ. First-time borrowers can also review our first-time auto loan guide before submitting a final application.
3. Understand What Can Affect Your Financing Offer
There is no single CarMax financing APR that applies to every buyer. Auto loan terms can vary according to the applicant, vehicle, amount financed, and other underwriting factors.
Factors that may affect an auto financing offer can include:
- Credit history and credit score
- Income and employment information
- Existing debts and financial obligations
- Vehicle price and characteristics
- Down payment or trade-in equity
- Amount financed
- Loan term
- Current lending conditions
A stronger credit profile can improve your chances of receiving more favorable financing, but lenders consider more than a credit score alone.
If affordability is your main concern, our guide to affordable auto loans explains additional factors to evaluate when comparing borrowing costs.
4. Compare APR, Term and Total Loan Cost

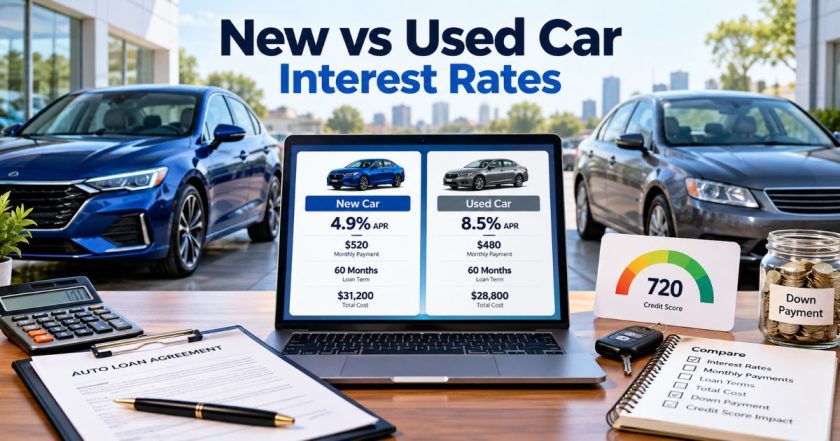
Once you have potential financing terms, compare them carefully. The lowest monthly payment is not automatically the lowest-cost loan.
Pay particular attention to:
- APR: a standardized measure of borrowing cost that can help you compare credit offers.
- Amount financed: the amount of credit being provided.
- Loan term: how long you are scheduled to make payments.
- Monthly payment: the scheduled amount due each month.
- Finance charge: the dollar cost of credit disclosed in the agreement.
- Total of payments: what you will have paid after making all scheduled payments under the contract.
The Consumer Financial Protection Bureau explains that APR and interest rate are not the same thing. APR is particularly useful when comparing loans because required loan charges can affect the cost of credit.
For a broader comparison of financing sources, see our car finance options guide.
Shorter vs. Longer Loan Terms
A shorter term generally means fewer months of borrowing but can require a higher monthly payment. A longer term can lower the scheduled monthly payment but may keep you in debt longer and can increase borrowing costs, depending on the APR and other terms.
Rather than automatically selecting the longest available term, compare several combinations of APR, term, down payment, and total repayment cost.
5. Compare CarMax Financing With Outside Lenders
Convenience should not replace comparison shopping. Before accepting a financing offer, consider checking available terms from banks, credit unions, or other legitimate auto lenders.
The CFPB recommends shopping around because financing offers can differ between lenders. An outside preapproval can also give you a useful benchmark when evaluating financing available through a dealership.
Compare equivalent information across offers:
| Factor | What to Compare |
|---|---|
| APR | Compare APR with APR, not APR with a basic interest rate. |
| Term | Check how many months you will be making payments. |
| Amount Financed | Confirm exactly how much you are borrowing. |
| Monthly Payment | Make sure the payment fits your ongoing budget. |
| Total Cost | Review the finance charge and total of payments. |
| Down Payment | Compare how different upfront amounts change the loan. |
Our top auto finance guide explains additional points to consider when comparing lenders and financing structures.
6. Decide on a Down Payment and Handle Your Trade-In Carefully

A down payment reduces the amount you need to finance. In general, financing a smaller amount can reduce your monthly payment and borrowing cost, assuming the other loan terms remain the same.
There is no single down-payment percentage that is right for every buyer. The appropriate amount depends on your cash reserves, vehicle price, trade-in position, financing terms, and other financial priorities.
Understand Trade-In Equity
If you trade in a vehicle, compare its value with any outstanding payoff amount.
Positive equity means the vehicle’s trade value exceeds what you owe. Negative equity means you owe more than the vehicle is worth.
If negative equity is included in a new financing arrangement, it can increase the amount you need to finance. This makes it especially important to review the final amount financed instead of focusing only on the new monthly payment.
If you are considering selling instead of trading, read our guide on how to sell a financed car.
7. Review the Contract Before You Sign
Pre-qualification results are not a substitute for reviewing your final retail installment contract. Before accepting financing, make sure the numbers in the agreement match what you expect.
Check:
- Vehicle purchase price
- Down payment
- Trade-in credit and any payoff
- Amount financed
- APR
- Finance charge
- Number of payments
- Monthly payment
- Total of payments
- Taxes and applicable fees
- Any optional products included in the transaction
Ask questions about anything you do not understand before signing. Do not assume that a lower monthly payment means you received a better overall deal.
Comparing the final numbers with other auto finance deals can help you evaluate whether the financing remains competitive for your situation.
8. Manage CarMax Auto Finance Payments and Payoff Correctly

If your final contract is with CarMax Auto Finance, managing the account properly becomes important after the purchase.
CarMax says customers can set up a MyCarMax account to manage their CarMax Auto Finance account and make online payments. The CarMax app can also be used for payments after the account is properly registered.
How CarMax Auto Finance Calculates Finance Charges
According to CarMax Auto Finance, its retail installment contracts use simple interest. Finance charges accrue daily based on the outstanding principal balance, APR, and number of days since the previous payment.
This means payment timing can affect the amount of finance charges that accrue. CarMax explains that late or smaller-than-scheduled payments may result in more finance charges, while earlier or larger payments may result in less, depending on the account and contract.
CarMax Auto Finance Payoff
If you want to pay the account off, obtain a current payoff amount rather than assuming the principal balance shown on a statement is the exact payoff figure.
CarMax says customers can obtain an up-to-date payoff amount through their account or by contacting CarMax Auto Finance customer service.
This is also important if you plan to sell a financed vehicle, because the lien generally must be addressed as part of completing the sale.
Can You Refinance CarMax Auto Finance?
CarMax Auto Finance currently does not offer refinancing of its own contracts. This corrects a common misconception about CarMax financing.
However, CarMax states that a customer may refinance the vehicle through another financial institution. According to CarMax Auto Finance, there is no penalty for paying off a CAF account early.
CarMax also notes that refinancing through another lender may depend on title and registration processing, which can vary by state and local DMV procedures.
If you are considering refinancing, compare the new APR, remaining term, fees, monthly payment, and total remaining cost before replacing the existing loan.
CarMax Auto Finance vs. Other Financing Options
CarMax financing may be convenient because financing can be explored while shopping its vehicle inventory, but convenience should be only one part of your decision.
Here is a simple way to think about your choices:
| Financing Source | Potential Advantage | What to Check |
|---|---|---|
| CarMax financing | Integrated with the CarMax shopping process | APR, lender, term, down payment and final cost |
| Bank | May offer direct preapproval | Eligibility, APR, term and vehicle requirements |
| Credit union | May provide competitive member financing | Membership and loan requirements |
| Online auto lender | May provide a digital application process | Rates, fees, lender reputation and final terms |
No financing source is automatically best for every borrower. Compare actual offers available to you.
Used-car shoppers should also review our used car loan guide before making a final financing decision.
Common CarMax Financing Mistakes to Avoid
Focusing Only on Monthly Payment
A lower payment may result from extending the repayment period. Always compare APR, term, amount financed, finance charge, and total payments.
Treating Pre-Qualification as Guaranteed Approval
CarMax pre-qualification provides estimated personalized terms, but final financing requires a credit application and final approval.
Not Comparing Another Lender
Even when a CarMax financing offer appears affordable, obtaining another quote can give you a useful point of comparison.
Financing More Car Than Your Budget Supports
Approval for a particular amount does not mean borrowing that amount is financially comfortable. Consider insurance, maintenance, fuel, and your other obligations.
Ignoring Negative Equity
Rolling an unpaid balance from a trade-in into another transaction can increase the amount financed and make it harder to build positive equity in the replacement vehicle.
Assuming CarMax Will Refinance the Loan Later
CarMax Auto Finance currently does not offer refinancing. If refinancing becomes appropriate, you would need to explore another lender.
Good borrowing decisions should fit into your broader financial plan. Our personal finance guide covers budgeting, debt management, saving, and other fundamentals.
Frequently Asked Questions About CarMax Auto Finance
Does CarMax offer financing?
Yes. CarMax offers access to several finance sources, including CarMax Auto Finance. The lender or finance source available to an individual shopper can depend on the application and financing decision.
Does CarMax pre-qualification affect your credit score?
CarMax states that its pre-qualification process uses a soft credit inquiry and does not affect your credit score. Moving forward with a final credit application involves a hard inquiry that may affect your score.
How long is a CarMax pre-qualification valid?
CarMax currently states that personalized pre-qualification terms are available for 30 days. Final terms still require a credit application.
What credit score is required for CarMax financing?
CarMax does not present one universal minimum credit score on its current pre-qualification information. Financing decisions and terms can depend on the applicant’s overall credit and financial profile as well as the transaction.
Can I use my own bank or credit union when buying from CarMax?
Buyers can consider outside financing. Comparing an outside bank or credit union offer with financing available through CarMax can help you evaluate APR, term, and total cost.
Does CarMax Auto Finance offer refinancing?
No. CarMax Auto Finance currently states that it does not offer refinancing. You may be able to refinance through another financial institution, subject to that lender’s requirements.
Is there a penalty for paying CarMax Auto Finance off early?
CarMax Auto Finance states that there is no penalty for paying off the account early. Obtain a current payoff amount before making the final payment.
How do I find my CarMax Auto Finance payoff amount?
CarMax says an up-to-date payoff amount can be obtained by signing in to the account online or contacting CarMax Auto Finance customer service.
Can I make CarMax Auto Finance payments online?
Yes. CarMax says eligible customers can register their CarMax Auto Finance account through MyCarMax and make online payments. Payments can also be made through the CarMax app after the account is set up.
Does CarMax Auto Finance use simple interest?
CarMax Auto Finance states that its retail installment contracts are simple-interest contracts, with finance charges accruing daily based on APR, outstanding principal, and the time between payments.
Official Resources
- CarMax Financing and Pre-Qualification
- CarMax Auto Finance
- CarMax Auto Finance FAQs
- Consumer Financial Protection Bureau: Interest Rate vs. APR
- Consumer Financial Protection Bureau: Ways to Finance a Vehicle
Final Thoughts on CarMax Auto Finance
CarMax Auto Finance can provide a convenient financing path for eligible used-car buyers, particularly because CarMax allows shoppers to explore personalized financing terms before completing a final application. But convenience alone should not determine which loan you accept.
Set your budget first, review your credit, use pre-qualification carefully, compare APR and total borrowing costs, and check at least one competing financing option when practical. If you ultimately finance through CAF, understand how payments, daily finance charges, and payoff amounts work.
Most importantly, choose a vehicle and financing structure that fits your broader financial goals rather than stretching your budget to match the maximum amount available. For more guidance, review our strategies for financial success and car finance options resources.