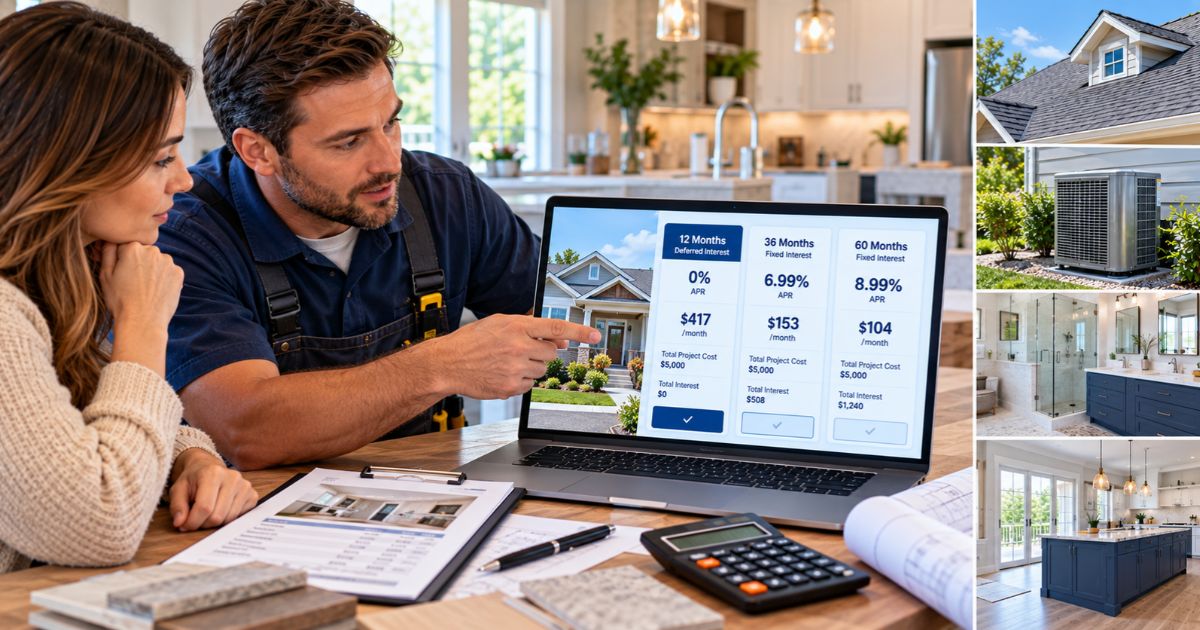
GreenSky Financing helps homeowners access consumer credit for eligible home improvement projects through participating contractors and financial institutions. The platform can be used for projects ranging from HVAC replacement and roofing to kitchens, bathrooms, windows, pools and other residential improvements.
One important point is that GreenSky itself is not the lender. Loans offered through the GreenSky program are made by participating federally insured banks and other eligible financial institutions, while GreenSky provides technology, origination support and servicing functions.
This updated guide explains how GreenSky Financing works, how applications and credit checks are handled, what fees may apply, how contractor transactions work, how promotional plans differ and what homeowners should compare before accepting financing.
For broader borrowing guidance, also see our personal loan rates guide, finance charge guide, and credit score guide.
Key Takeaways
- GreenSky administers a consumer loan program but is not itself the lender.
- Participating banks and financial institutions make credit decisions and set loan terms.
- Home improvement financing is commonly offered through participating merchants and contractors.
- A credit report may be obtained when you apply.
- Some approved loans may include an origination fee.
- Promotional financing can include deferred-interest structures, which require careful payoff planning.
- The final loan agreement and Truth in Lending disclosure control your actual APR, fees and repayment terms.
1. What Is GreenSky Financing?
GreenSky Financing is a consumer finance program commonly used for home improvement purchases and services offered by participating merchants and contractors.
GreenSky describes itself as a financial technology company that manages and supports the consumer loan program on behalf of participating lenders.
The actual loans are issued by participating federally insured federal or state-chartered financial institutions.
That distinction is important because your loan agreement should identify the actual lender responsible for extending the credit.
Current program information can be reviewed on the official GreenSky website.
Who services the loan?
GreenSky Servicing, LLC services program loans on behalf of participating lenders.
Your billing statement should identify the current lender associated with your account.
2. How Does GreenSky Financing Work?
A typical GreenSky transaction begins through a participating home improvement contractor or merchant.
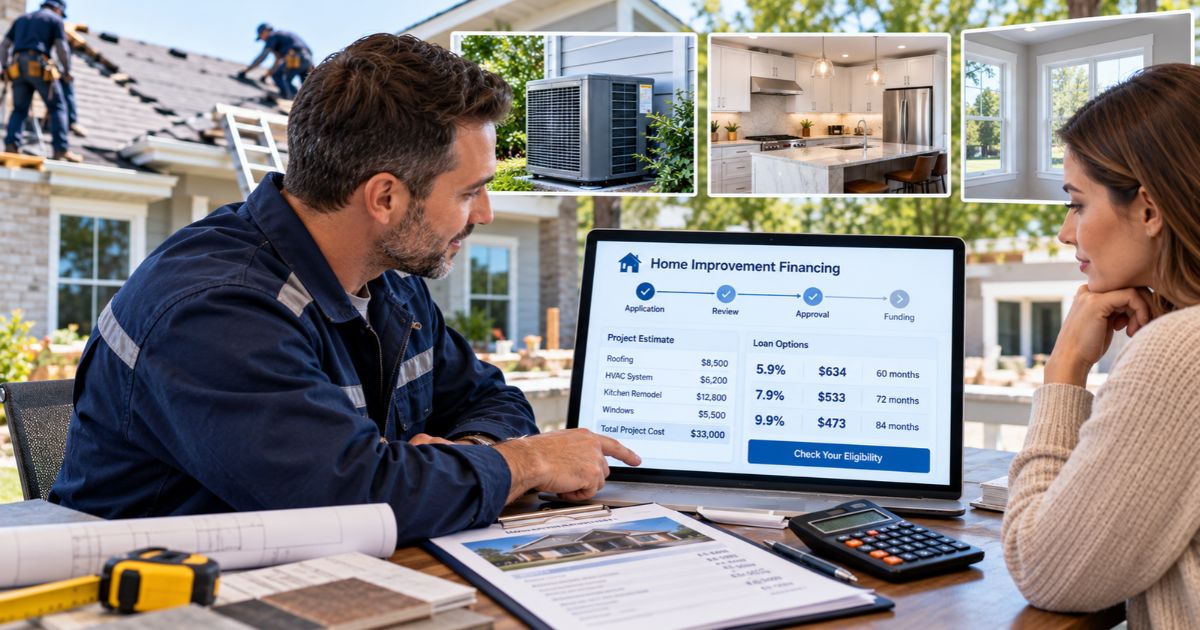
Step 1: Discuss project financing
A contractor may present available payment plans for your renovation, repair or installation.
Examples of projects commonly financed through home improvement credit include:
- HVAC systems;
- roof replacement;
- windows and doors;
- kitchen renovations;
- bathroom projects;
- flooring;
- solar or energy upgrades;
- pools;
- and other qualifying home services.
Step 2: Submit the application
The application collects information needed for lenders to evaluate the request.
GreenSky’s current disclosures state that applicants authorize the program to obtain a consumer credit report in connection with the application and other permitted account purposes.
Step 3: Review the credit offer
If approved, the borrower receives specific loan terms such as:
- approved credit amount;
- APR;
- repayment period;
- applicable fees;
- and other account terms.
Step 4: Accept the agreement
Approved borrowers generally accept an Installment Loan Agreement electronically.
Always read the Truth in Lending disclosures before completing the process.
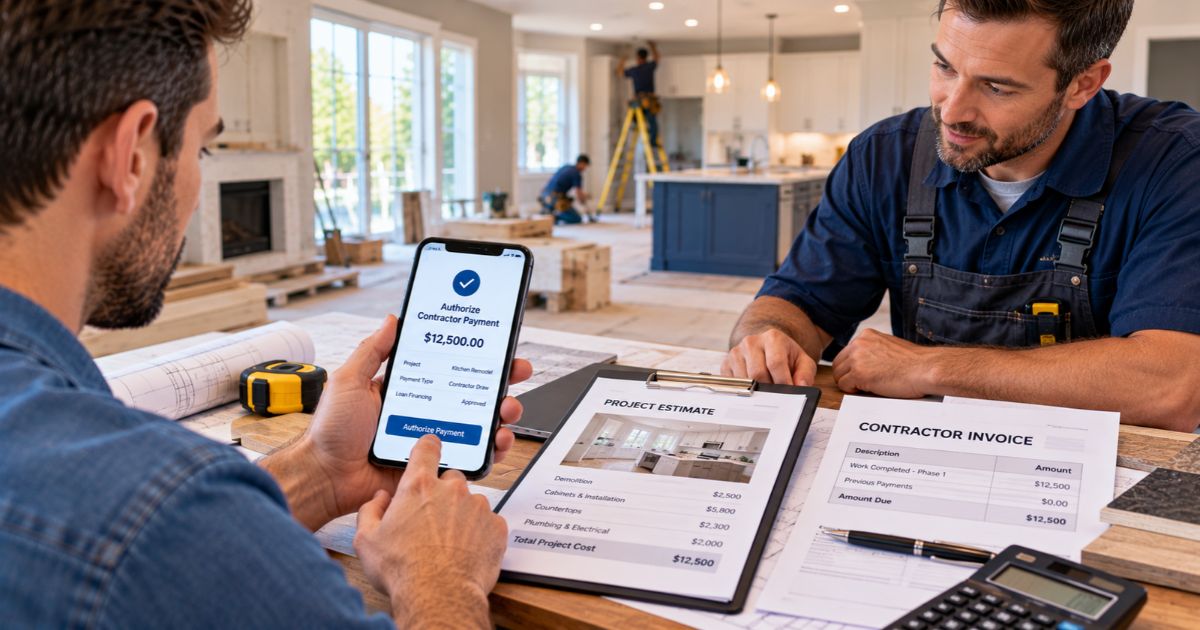
Step 5: Authorize contractor transactions
GreenSky’s merchant guidance says customers receive a text or email requesting authorization before a merchant transaction is processed.
This allows the borrower to approve charges associated with the project.
3. GreenSky Is Not the Actual Lender
One of the most important facts about GreenSky Financing is that GreenSky, LLC and GreenSky Servicing, LLC do not make the loans themselves.
The program is administered for participating banks and other financial institutions.
Why does the lender matter?
The lender is responsible for the actual extension of credit.
Your agreement should identify:
- the lender;
- amount financed;
- APR;
- finance charge;
- payment schedule;
- fees;
- and other contractual terms.
Can the lender change later?
GreenSky’s current customer FAQ notes that some program loans may be transferred from one participating lender to another.
Your current billing statement should show the lender associated with the account at that time.
4. Credit Checks and Prequalification
Homeowners should understand the difference between checking potential eligibility and submitting a full credit application.
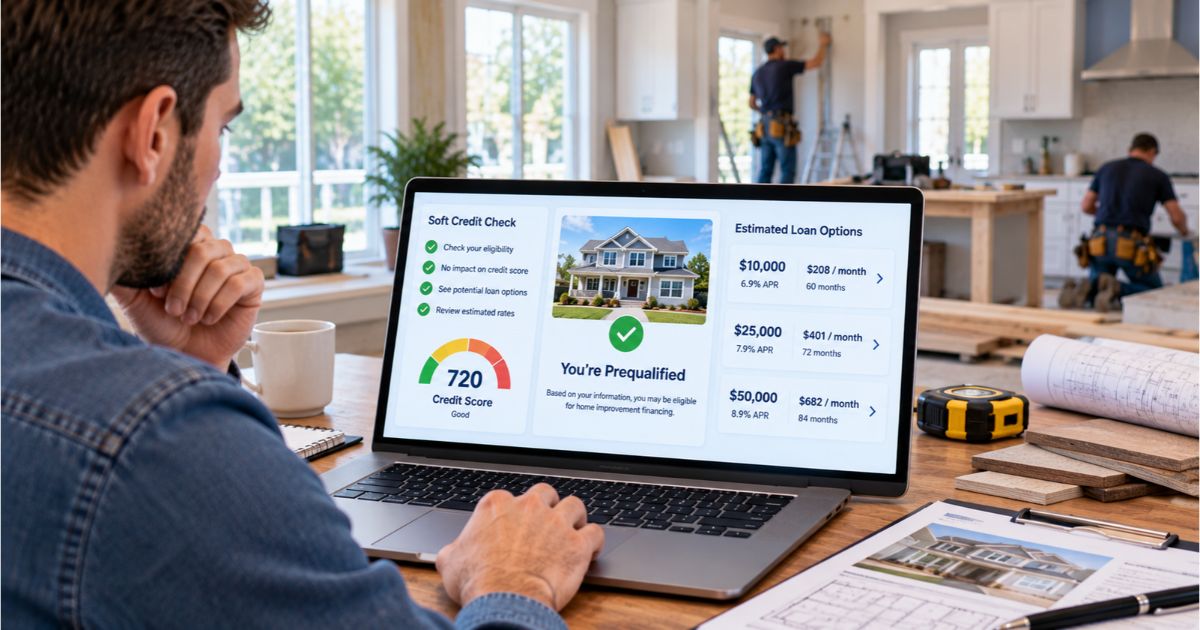
A credit report may be obtained
The current GreenSky application disclosures state that applicants authorize the program to obtain a consumer credit report for the application.
Therefore, the old claim that applying for GreenSky credit has “no impact on your credit score” should not be made universally.
Prequalification
GreenSky materials also describe a prequalification process that can allow a consumer to see a potential offer before continuing to a full loan application.
A prequalified offer is not necessarily the same thing as final credit approval.
Final terms depend on underwriting
The participating lender ultimately determines:
- whether the borrower qualifies;
- credit amount;
- APR;
- repayment period;
- and other loan terms.
To better understand credit inquiries and score factors, see our credit score calculation guide.
5. GreenSky Interest Rates and APR
GreenSky Financing does not have one universal interest rate that applies to every homeowner.
Rates depend on the specific credit plan, participating lender, applicant qualifications and project financing structure.
Promotional rates may be available
GreenSky currently tells participating merchants that certain credit plans can have promotional rates as low as 0%, subject to credit approval and plan terms.
However, that does not mean every borrower will receive 0% financing.
APR matters
APR reflects the annualized cost of credit and can incorporate interest plus applicable finance charges.
Compare:
- stated interest rate;
- APR;
- loan term;
- monthly payment;
- finance charge;
- and total repayment.
See our loan rates guide for additional comparison principles.
6. Deferred-Interest Financing Requires Care
Some GreenSky plans may use deferred-interest promotions.
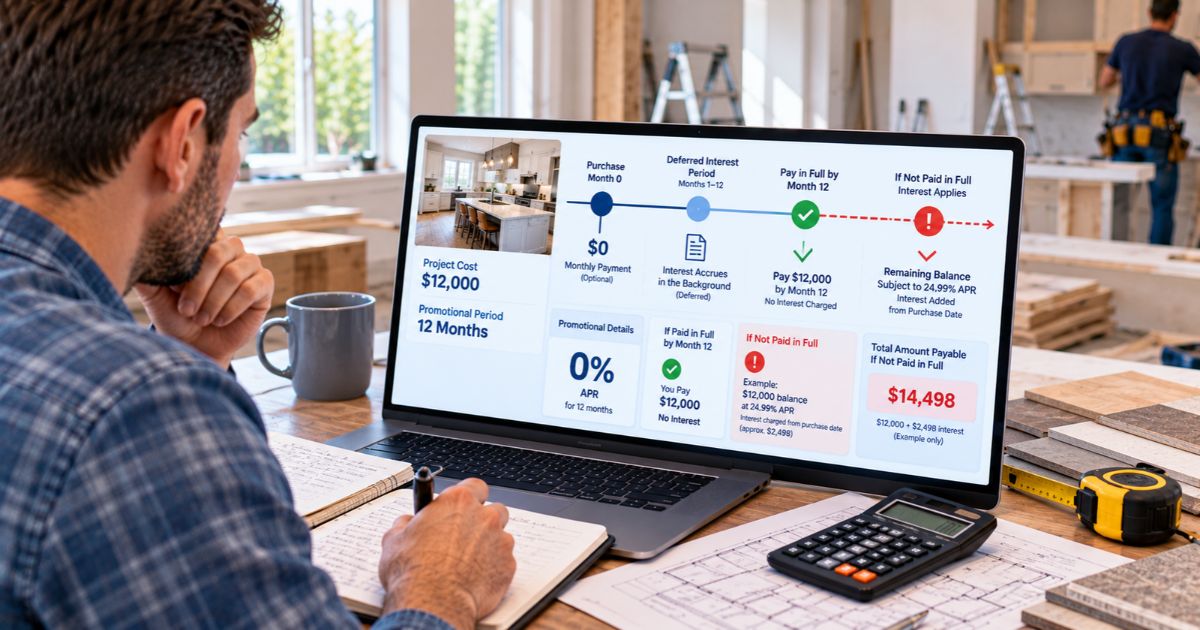
These arrangements deserve special attention because the repayment rules can be different from a simple 0% installment loan.
How deferred interest can work
GreenSky’s current disclosures explain that on certain deferred-interest products, interest is calculated from the purchase date.
The accumulated finance charges are waived only if the entire qualifying purchase balance is paid in full before the end of the promotional period.
Why this matters
If the required balance is not completely paid before the promotional deadline, accrued interest can become payable according to the agreement.
Do not assume that making only the minimum required payment will automatically eliminate the balance before the promotion expires.
Build your own payoff plan
Take the amount that must be repaid before the promotional deadline and divide it by the number of available months.
Then compare that target with the required minimum payment.
If the minimum is lower, you may need to voluntarily pay more each month to avoid remaining balance at the end of the promotion.
7. Fees That May Apply
The old article stated broadly that GreenSky had “no hidden fees.” A more accurate approach is to review the actual disclosure because fees can vary by loan.
Origination fee
GreenSky’s current disclosures state that an approved loan may include a non-refundable origination fee of up to $89.
For swimming-pool loans, the disclosed maximum can be as high as $1,000.
If an origination fee applies, it should appear in the Truth in Lending disclosure and loan agreement and be reflected in the estimated APR and finance charge.
Other charges
Your particular agreement may include terms addressing:
- late payments;
- returned payments;
- interest;
- finance charges;
- and other account obligations.
Do not rely on a generic article to determine the fees on your individual contract.
Check the final documents
Before accepting a loan, review:
- APR;
- finance charge;
- amount financed;
- total of payments;
- payment schedule;
- origination fee;
- and promotional conditions.
Our finance charge explanation can help you understand these figures.
Home Improvement Projects Commonly Financed
GreenSky Financing is closely associated with home improvement merchant financing.
Potential project categories can include:
Kitchen renovation
Cabinets, countertops, flooring, lighting and major appliances can make a kitchen project expensive.
Bathroom remodeling
Bathroom upgrades can involve plumbing, tile, fixtures, showers and cabinetry.
Roof replacement
A roof can be a major household expense, particularly when replacement becomes urgent.
HVAC replacement
Heating and cooling systems can require significant upfront spending.
Windows and doors
Energy-efficient replacements can improve comfort and may reduce heating or cooling losses depending on the home.
Solar and energy improvements
Some contractors use home improvement financing to help customers fund solar, insulation and other energy-related upgrades.
Swimming pools
Pool projects can involve large contract amounts. GreenSky’s disclosures even contain separate origination-fee language for eligible swimming-pool loans.
How Contractors Use GreenSky
The GreenSky platform is designed partly around a merchant and contractor network.
Offering payment choices
Participating contractors can present eligible customers with financing plans instead of requiring the entire project price upfront.
Contractors pay program transaction fees
GreenSky’s current merchant FAQ states that participating merchants pay a fee for transactions processed through the program.
Customer authorization
The merchant cannot simply charge the loan account without customer approval.
According to GreenSky’s merchant guidance, the customer receives a text message or email authorizing the transaction.
Contractor quality is a separate issue
A contractor participating in a finance network should not automatically be assumed to be the best contractor for your project.
Homeowners should independently review:
- licenses where required;
- insurance;
- references;
- reviews;
- written estimates;
- warranties;
- and project scope.
GreenSky Financing vs Credit Cards
A home improvement installment loan and a credit card are different financial products.
| Feature | Home Improvement Loan | Credit Card |
|---|---|---|
| Credit Structure | Usually installment credit | Revolving credit |
| Project Use | Commonly tied to participating merchant transaction | Can generally be used across eligible merchants |
| Payment Structure | Defined by loan agreement | Varies with revolving balance |
| Promotions | Can include deferred-interest or other promotional plans | May include introductory APR promotions |
| APR | Depends on approved plan | Depends on card agreement |
Which is cheaper?
Neither product is automatically cheaper.
The old claim that GreenSky is always less expensive than credit cards should be avoided.
Compare the actual APR, promotion, repayment period and fees available to you.
GreenSky Financing vs Home Equity Financing
Homeowners may also consider a home equity loan or HELOC for renovation costs.
Potential home equity advantage
Secured borrowing can sometimes offer competitive rates because the lender has collateral.
Important risk
Home equity borrowing uses your home as collateral.
Failure to repay can therefore create substantially different consequences from ordinary unsecured credit.
Closing costs and timing
Home equity products may also involve appraisal, closing costs or a longer approval process.
Compare all costs rather than rate alone.
Are All GreenSky Loans Unsecured?
No universal claim should be made that every GreenSky loan is unsecured.
Current program disclosures specifically state that applicants may be considered for products including a fixture secured loan.
Therefore, check your individual agreement to determine whether collateral or a security interest applies.
How Much Can You Borrow?
The previous version of this article listed broad fixed dollar ranges as though they applied to every borrower.
A safer approach is to rely on the amount offered in your actual prequalification or approved credit decision.
The available amount can depend on:
- requested project amount;
- credit profile;
- participating lender;
- specific plan;
- and underwriting criteria.
Borrow only what the project needs
Approval for a large credit amount does not mean you should automatically spend it.
Build a written project budget first.
Include:
- materials;
- labor;
- permits;
- taxes;
- contingencies;
- and any project-related fees.
Do Not Treat Approval as Project Due Diligence
A lender’s approval indicates that the lender is willing to extend credit subject to its terms.
It does not establish that:
- the contractor’s quote is competitive;
- the renovation will increase property value;
- the project will save enough energy to cover the loan;
- or the project itself is financially wise.
Evaluate the renovation separately from the financing decision.
Energy-Efficient Home Improvements
Homeowners frequently use renovation credit for energy-related projects.
Examples include:
- HVAC replacement;
- insulation;
- high-efficiency windows;
- solar systems;
- water heaters;
- and energy-efficient appliances.
Avoid guaranteed savings claims
Energy improvements can potentially reduce utility use, but savings depend on climate, home condition, utility prices, system efficiency and household behavior.
Calculate expected savings conservatively rather than assuming the project will “pay for itself.”
Large Renovation Projects
GreenSky Financing may also be used for larger renovation transactions offered by participating merchants.
Examples can include:
- major kitchen remodeling;
- multiple-bath renovations;
- room additions;
- whole-home window replacement;
- pool construction;
- roof replacement;
- and large HVAC projects.
Get multiple contractor quotes
For expensive projects, compare several written bids where practical.
The lowest estimate is not automatically the best, but multiple bids can help reveal whether one proposal is unusually expensive.
Managing and Repaying a GreenSky Loan
Approved borrowers can manage eligible accounts through GreenSky’s customer servicing system.
Customer portal
The GreenSky customer portal provides resources for:
- account information;
- payments;
- statements;
- loan documents;
- payoff information;
- and servicing questions.
Current account assistance is available through the official GreenSky customer FAQ.
Automatic payment
If your servicing options allow automatic payment, confirm the amount and withdrawal date.
Automatic payments can help avoid missed due dates, but you should still review each statement.
Payoff
Request the current payoff amount rather than assuming the balance on an older statement equals the amount required to close the account.
Can You Pay a GreenSky Loan Off Early?
Do not rely on a generic article statement saying every program loan has no prepayment penalty.
Instead, review the prepayment terms in your specific Installment Loan Agreement.
If you are using a deferred-interest promotion, paying the qualifying balance in full before the promotional deadline may be especially important.
Questions to Ask Before Accepting GreenSky Financing
- Who is my actual lender?
- What is my approved credit amount?
- What is the interest rate?
- What is the APR?
- Does an origination fee apply?
- What is the finance charge?
- How long is the repayment period?
- What is the required monthly payment?
- Is this a deferred-interest promotion?
- When does the promotional period end?
- What balance must be paid by that date?
- Is the loan secured or unsecured?
- What happens after a late payment?
- What are the early-payoff terms?
- How does the contractor request payment?
- How do I dispute an incorrect transaction?
- What is the total expected borrowing cost?
Common GreenSky Financing Mistakes
Assuming GreenSky is the lender
The program is administered by GreenSky, while participating financial institutions make the loans.
Treating promotional financing as automatically free
Deferred-interest plans can produce interest charges if the required balance is not paid in full before the promotional deadline.
Looking only at monthly payment
A manageable monthly payment can still accompany a high total borrowing cost.
Assuming no fees apply
Some approved loans can have an origination fee.
Assuming there is no credit check
Current application disclosures authorize the obtaining of a consumer credit report.
Borrowing the maximum available
Base the loan amount on the actual project budget rather than the maximum approved limit.
Skipping contractor due diligence
Finance availability should not substitute for checking a contractor’s qualifications and project terms.
Related Best Finance Live Guides
- How to Get a Personal Loan
- Personal Loan Rates
- Personal Loan With No Origination Fee
- Personal Loans for Bad Credit
- Secured Personal Loans
- Secured vs Unsecured Personal Loans
- Finance Charges Explained
- How Credit Scores Are Calculated
- Highest Credit Score Guide
- Master Your Money
- Complete Personal Finance Guide
- Top Financial Tips
- Business Loans Guide
- Business Loan Interest Rates
- Business Loan Payment Calculator
- First Time Business Loan
- Unsecured Small Business Loans
- Average Credit Card Debt
- Best Finance Live Guide
- Personal Finance Course
Conclusion
GreenSky Financing can provide a convenient way to fund qualifying home improvement projects through participating contractors and financial institutions.
However, GreenSky itself is not the lender. Participating financial institutions make the credit decision and establish the actual APR, loan amount and repayment terms.
Homeowners should pay particular attention to promotional structures, especially deferred-interest plans. If the required purchase balance is not paid in full before the promotional period ends, accrued interest can become payable according to the agreement.
Also review any origination fee, repayment period, APR, finance charge and security provisions before accepting the loan.
Finally, evaluate the home improvement project separately from the credit offer. Compare contractor quotes, verify the contractor’s credentials and make sure the monthly payment fits comfortably within your household budget.
Frequently Asked Questions
What is GreenSky Financing?
Is GreenSky a lender?
Does GreenSky check credit?
Does GreenSky charge an origination fee?
Frequently Asked Questions
What is GreenSky Financing?
GreenSky Financing is a consumer loan program administered through GreenSky’s technology and servicing platform. Participating financial institutions make the actual loans.
Is GreenSky a lender?
No. Current GreenSky disclosures state that GreenSky, LLC and GreenSky Servicing, LLC are not lenders. Participating federally insured financial institutions provide the credit.
Does GreenSky check credit?
GreenSky’s current application disclosures state that applicants authorize a consumer credit report to be obtained in connection with the loan application and other permitted account purposes.
Does GreenSky charge an origination fee?
Some approved loans may include an origination fee. Current disclosures state that the fee can be up to $89, or up to $1,000 for swimming-pool loans, when applicable.
What is deferred-interest financing?
With certain deferred-interest plans, interest accrues from the purchase date but is waived if the entire qualifying purchase balance is paid in full before the promotional period expires. Review your specific agreement carefully.
Can GreenSky be used for home renovations?
Yes. The GreenSky consumer loan program is widely used through participating home improvement merchants and contractors for eligible projects and services.
Does GreenSky offer 0% financing?
Certain participating plans may offer promotional rates as low as 0%, subject to credit approval and specific program terms. Not every borrower or project will qualify.
Are all GreenSky loans unsecured?
No universal claim should be made. Current disclosures indicate that applicants may be considered for products including fixture-secured loans.
How do contractors get paid?
Participating merchants submit eligible transactions, and GreenSky’s merchant guidance says customers receive a text or email to authorize the transaction before payment processing.
What should I compare before accepting the loan?
Compare the APR, interest rate, origination fee, finance charge, repayment period, monthly payment, promotional conditions, total borrowing cost and contractor price before signing.