Understanding does prequalification affect credit score is important before sharing personal information or requesting financing. A lender may provide an initial estimate without a hard credit check, but a formal application can trigger a different review that may temporarily affect your credit profile.
Prequalification can help borrowers compare potential interest rates, loan amounts, repayment terms, and eligibility requirements. It does not guarantee final approval or a particular annual percentage rate.
This comprehensive guide explains soft versus hard inquiries, the difference between prequalification and preapproval, mortgage and auto loan rate-shopping rules, and seven practical tips for protecting your credit while comparing lenders.
For additional guidance, review our credit score calculation guide, credit improvement timeline, and 650 credit score personal loan guide.
Key Takeaways
- Soft credit inquiries do not lower your credit score.
- Many lenders use soft inquiries for initial prequalification, but this is not universal.
- Hard inquiries generally occur when lenders evaluate formal credit applications.
- A single hard inquiry often has a relatively small scoring effect.
- Prequalification and preapproval are not standardized terms across lenders.
- Certain mortgage, auto, and student loan inquiries may receive special rate-shopping treatment.
- Prequalification is not a guarantee of final credit approval.
- Borrowers should compare APR, fees, terms, and total borrowing costs.
1. Does Prequalification Affect Credit Score?
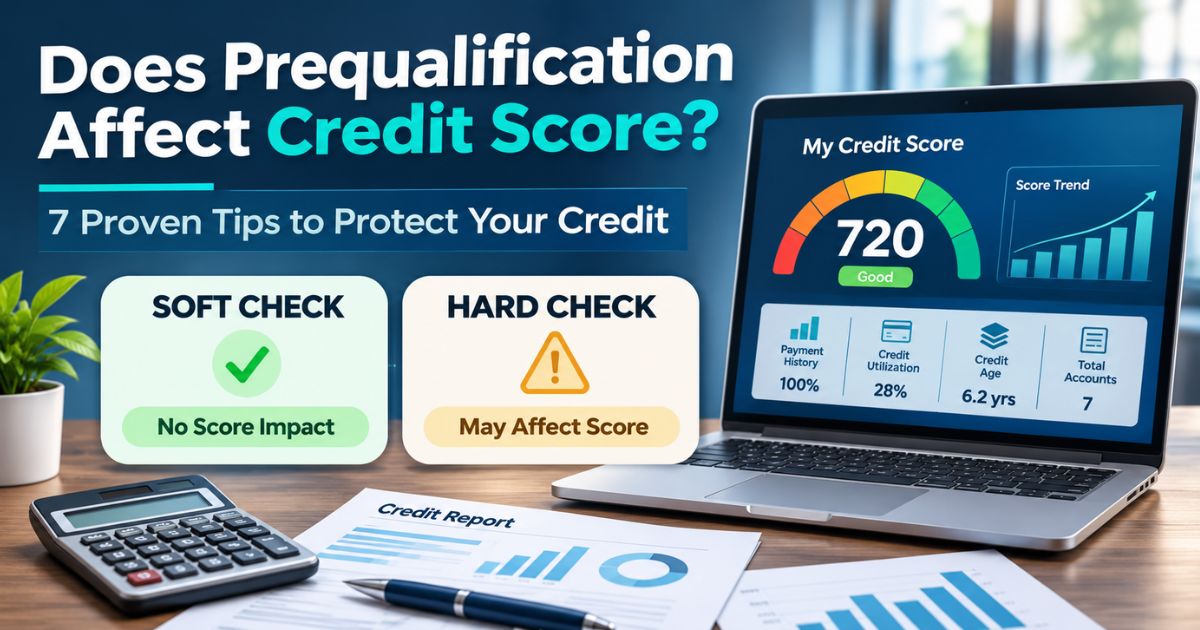
The most useful answer to does prequalification affect credit score is that a genuine soft-inquiry prequalification does not affect your score. The important distinction is whether the lender performs a soft or hard credit check.
How prequalification generally works
Prequalification is often an initial evaluation that estimates whether a borrower might qualify for a financial product.
The lender may request:
- Basic personal information.
- Estimated annual income.
- Employment information.
- Housing expenses.
- Approximate monthly debt obligations.
- Requested loan amount.
- Credit authorization where applicable.
Some lenders use a soft credit inquiry to supplement this information.
Why soft checks do not lower scores
Soft inquiries are not counted as new-credit application inquiries in commonly used consumer credit scoring models.
Examples include reviewing your own report, certain account reviews, and many preliminary eligibility checks.
When a hard inquiry may occur
If you proceed to a formal credit application, the lender may perform a hard inquiry to assess your creditworthiness.
Depending on the lender, this may occur during the application or another stage of underwriting.
Why lender disclosures matter
Before clicking an application button, review the language describing credit authorization.
If you are asking does prequalification affect credit score with a particular company, its stated inquiry procedure matters more than the word prequalification alone.
The Consumer Financial Protection Bureau’s credit inquiry guidance explains the distinction between soft and hard credit inquiries and how they affect consumers.
2. Understand Soft Credit Inquiries
A soft credit inquiry is a review of credit information that does not affect the consumer’s credit score.
Borrowers checking does prequalification affect credit score should understand which activities typically generate soft inquiries.
Common examples of soft inquiries
- Checking your own credit report.
- Credit monitoring account reviews.
- Some prequalified credit-card offers.
- Existing-account reviews by creditors.
- Certain lender eligibility estimates.
- Some insurance-related credit reviews.
Can you check your own credit report?
Yes. Reviewing your personal credit report does not lower your credit score.
You can examine information reported by Equifax, Experian, and TransUnion to identify errors, unfamiliar accounts, and outdated personal information.
Who can see soft inquiries?
Soft inquiries can appear on the version of your credit report available to you, but they are generally not included in reports viewed by prospective creditors.
This differs from hard inquiries, which may be visible when lenders review your credit file.
How often can you use soft-inquiry prequalification?
Soft inquiries themselves do not lower credit scores, so there is no scoring penalty simply for having several legitimate soft checks.
However, each lender may have limits on how frequently you can request offers. Sharing sensitive information with unnecessary websites can also create privacy concerns.
Soft inquiries do not guarantee approval
A lender might provide an initial rate estimate using limited information, then decline the formal application after further verification.
This does not mean the soft inquiry damaged your credit. It means the underwriting decision considered additional information.
Soft credit inquiry vs hard credit inquiry
| Feature | Soft Inquiry | Hard Inquiry |
|---|---|---|
| Score Impact | No direct impact | May temporarily lower score |
| Typical Purpose | Monitoring or initial screening | New credit application |
| Visible to New Lenders | Generally no | Generally yes |
| Credit Report Record | May appear on consumer report | Usually appears on report |
| Common Example | Soft-pull prequalification | Formal credit application |
For related information, read our highest credit score guide and how long credit improvement takes.
3. How Hard Credit Inquiries Affect Your Score
A hard inquiry generally occurs when a lender reviews your credit file as part of an application for new credit.
When researching does prequalification affect credit score, it is important to distinguish the initial estimate from the subsequent formal application.
What happens during a hard inquiry?
The lender requests credit information to help evaluate the applicant’s existing obligations, repayment history, and general credit risk.
The inquiry becomes part of the individual’s credit report.
How many points can a hard inquiry cost?
The effect differs by individual and scoring model.
For many people, one hard inquiry has a relatively small impact. However, the change can vary based on the overall credit file.
No lender can accurately promise the same number of points for every applicant.
How long do hard inquiries stay on reports?
Hard inquiries generally remain on U.S. credit reports for up to two years.
FICO scoring models generally consider eligible hard inquiries from the preceding 12 months rather than the full two-year reporting period.
Hard inquiries vs opening new accounts
These events are different.
A hard inquiry reflects the lender’s request to evaluate credit.
Opening a new account adds a credit obligation that may affect account age, amounts owed, and other scoring factors.
Will several applications always cause severe damage?
Not necessarily. Credit scoring models consider the type, timing, and context of inquiries.
However, applying for multiple unrelated credit products may affect scores differently from rate shopping for one qualifying loan type.
Do not confuse inquiries with credit utilization
Credit utilization compares revolving account balances with available credit limits.
High credit-card balances may affect scores independently of hard inquiry activity.
For related guidance, read our fair-credit personal loan guide, personal loan comparison guide, and credit card debt guide.
4. Check Lender Inquiry Rules Before Applying
The safest way to determine does prequalification affect credit score with a particular lender is to inspect its credit-check disclosures before submitting information.
Read the credit authorization notice
Look for statements indicating that checking eligibility will not affect your credit score.
A lender may also explain that a hard credit inquiry will occur when you submit the full application.
Check the specific product
Even within one financial institution, inquiry practices can differ between:
- Personal loans.
- Auto loans.
- Credit cards.
- Mortgages.
- Refinancing applications.
- Credit limit increase requests.
Ask the lender before proceeding
If the disclosure is unclear, contact customer support and request clarification.
Ask these questions:
- Will this step create a soft or hard inquiry?
- Will another credit check occur during underwriting?
- At what point does the process become a formal application?
- How long will the estimated offer remain valid?
- Is the stated APR conditional on additional verification?
Understand application authorization
Credit report access is subject to permissible-purpose and other legal requirements.
Do not assume every inquiry requires a separately signed form, but review the authorization included in an online or written application.
Verify the lender’s website
Use the organization’s legitimate website or verified contact details.
Avoid entering sensitive information into unfamiliar lead-generation forms without understanding how it will be used and shared.
Compare offers carefully
For auto financing, our best auto finance deals guide, affordable auto loans guide, and auto loan calculator provide additional borrowing context.
5. Prequalification vs Preapproval vs Final Approval
Understanding does prequalification affect credit score also requires understanding the three stages of the lending process.
The terms prequalification and preapproval are not used consistently by every lender.
What is prequalification?
Prequalification commonly provides an early estimate of borrowing eligibility based on limited or preliminary information.
Depending on the product, it may use self-reported financial details and a soft credit inquiry.
What is preapproval?
Preapproval can involve a more detailed review of a borrower’s credit information, income, and financial obligations.
However, some financial institutions use the term preapproval for initial screening offers that have not undergone full verification.
What is final approval?
Final approval is the lender’s decision after the required underwriting and verification conditions have been satisfied.
In a mortgage transaction, final loan approval may depend on property appraisal, title, verified employment, insurance, and other closing requirements.
Comparison of lending stages
| Stage | Typical Purpose | Credit Inquiry | Guarantee? |
|---|---|---|---|
| Prequalification | Early estimate | Often soft | No |
| Preapproval | More detailed eligibility review | Soft or hard | Usually conditional |
| Final Approval | Completed underwriting decision | May involve hard review | Subject to final terms |
Why terminology alone is unreliable
One lender might advertise a preapproval based on a soft inquiry, while another requires a hard pull before issuing a detailed mortgage preapproval letter.
Always evaluate the actual credit inquiry and underwriting process.
Preapproval is not guaranteed funding
Even after preapproval, changes in income, debt, credit history, or collateral valuation can affect the final lending decision.
For borrowers planning a major purchase, see our first-time auto loan guide and car finance options guide.
6. Understand Mortgage and Auto Loan Rate-Shopping Rules
Rate shopping can help borrowers compare interest rates and financing terms without unnecessarily accepting the first offer.
When people ask does prequalification affect credit score, they should also understand the special credit scoring treatment applicable to certain types of formal loan inquiries.
Mortgage rate shopping
Mortgage lenders often perform hard inquiries during preapproval.
However, multiple qualifying mortgage inquiries within an applicable shopping period may be counted as a single inquiry for scoring purposes.
Auto loan rate shopping
Similar treatment can apply when consumers compare auto loan offers from several financial institutions.
This does not mean every credit check disappears from the credit report. Individual inquiries may still be listed even when a scoring model groups qualifying inquiries.
Student loan rate shopping
Certain student loan inquiries can also qualify for special rate-shopping treatment.
Eligibility depends on the inquiry classification and credit scoring model.
FICO rate-shopping windows
Older FICO models generally use a 14-day rate-shopping window, while newer versions can use 45 days for qualifying mortgage, auto, and student loan inquiries.
Some FICO versions also temporarily disregard qualifying recent rate-shopping inquiries during an initial period.
The official myFICO rate-shopping explanation describes these rules and the differences between scoring versions.
Does this apply to every personal loan?
No. Do not assume personal loan or credit-card applications receive the same special inquiry treatment as qualifying mortgage, auto, or student loan shopping.
Keep comparisons focused
Research lenders first, then complete the necessary formal applications within a reasonably short time where the rate-shopping rules are relevant.
This may also help you compare offers made under similar market conditions.
Compare complete financing costs
For vehicle loans, review our new versus used car rates guide, good auto loan APR guide, and average car payments guide.
7. Follow Seven Proven Tips to Protect Your Credit
If you are wondering does prequalification affect credit score before applying for financing, following a structured process can reduce unnecessary uncertainty.
Tip 1: Review your credit report first
Check your credit report for errors, unfamiliar accounts, and inaccurate balances before submitting major credit applications.
Correcting legitimate errors can help lenders review accurate information.
Tip 2: Identify the loan purpose
Decide whether you need a personal loan, auto loan, mortgage, or another credit product.
Different loan types have different underwriting and inquiry rules.
Tip 3: Use clearly disclosed soft-inquiry tools
Where available, choose prequalification options that explicitly identify the initial review as a soft inquiry.
Tip 4: Compare APR and fees
Do not rely only on an advertised interest rate or monthly payment.
Compare annual percentage rate, origination fees, term, and total repayment.
Tip 5: Avoid unnecessary formal applications
Submit formal applications when you are ready to pursue realistic offers, while taking advantage of applicable rate-shopping protections.
Tip 6: Keep important documents
Save prequalification estimates, lender disclosures, application confirmations, and final offers.
Documented terms make it easier to compare changes during underwriting.
Tip 7: Monitor your report afterward
Review your credit report for unfamiliar hard inquiries and newly opened accounts.
If something appears incorrect, contact the relevant creditor or reporting company and follow the appropriate dispute procedure.
These steps help consumers evaluate does prequalification affect credit score without assuming every lender follows the same application process.
What Lenders Review Besides Your Credit Score
A credit score is one factor lenders may use when evaluating loan eligibility.
Even if prequalification uses a soft inquiry, a lender may consider other information that affects the estimated offer.
Income and employment
Lenders may review income sources and employment or self-employment history to assess repayment ability.
Debt-to-income ratio
Your debt-to-income ratio compares monthly debt obligations with gross monthly income.
For example, $1,200 in monthly debt payments divided by $4,000 in gross monthly income produces a 30% debt-to-income ratio.
Payment history
A history of on-time payments can support a borrower’s credit profile.
Late payments, defaults, or collection accounts may affect lender decisions.
Credit utilization
Credit utilization measures revolving balances relative to credit limits.
Borrowers with high revolving balances may receive different terms from otherwise similar applicants.
Loan amount and repayment term
A larger loan request creates a larger debt obligation.
Lenders may evaluate whether the expected payment fits the applicant’s available income.
Collateral and down payment
For secured loans, lenders may evaluate the asset pledged as collateral.
Auto lenders may review vehicle age, mileage, value, and down payment, while mortgage lenders examine property-related factors.
For related financial planning, see our car down payment guide, negative equity guide, and long-term auto loan guide.
How to Compare Prequalification Offers
After understanding does prequalification affect credit score, use the information from potential lenders to evaluate the total cost of borrowing.
Compare APR
APR reflects the annualized cost of credit, including applicable finance charges. It is usually more informative than the interest rate alone when comparing similar loan offers.
Review origination fees
Some personal loans include origination fees that reduce the amount deposited into your account or otherwise increase borrowing costs.
Compare repayment periods
A longer repayment term may lower the required monthly payment but can increase total interest.
Review conditional pricing
Prequalification offers may change after income verification, additional underwriting, or another credit review.
Check offer expiration dates
Initial rate estimates may remain available only for a limited period.
Keep copies of estimates and review new disclosures before accepting updated terms.
Example of comparing offers
| Factor | Offer A | Offer B |
|---|---|---|
| Loan Amount | $10,000 | $10,000 |
| APR | 12% | 14% |
| Term | 36 months | 36 months |
| Origination Fee | $0 | $300 |
| Initial Inquiry | Soft | Soft |
These offers are fictional examples and do not represent available lender products.
If all other relevant terms were comparable, Offer A would generally be less expensive because of its lower APR and absence of an origination fee.
Read our no-origination-fee personal loan guide, finance charges explanation, and first-time business loan guide for related borrowing concepts.
Prequalification for Different Financial Products
The answer to does prequalification affect credit score varies with lender procedures, not simply the financial product’s name.
Personal loans
Many personal loan providers offer preliminary eligibility checks using soft inquiries.
A completed application may trigger a hard inquiry and further verification.
Auto loans
Some auto lenders offer soft-inquiry prequalification tools, while formal financing requests may involve hard checks.
Borrowers comparing several formal auto loan applications may qualify for special rate-shopping scoring treatment.
Credit cards
Prescreened or prequalified credit-card offers may rely on soft inquiries.
Accepting an offer and completing a credit-card application often involves a hard inquiry.
Mortgage loans
Mortgage preapproval may require more detailed credit and financial verification.
Preapproval letters typically do not guarantee the lender will fund a transaction regardless of subsequent developments.
Refinancing
Refinancing replaces existing debt with another credit obligation.
A lender may review credit during the refinancing application, even when the borrower has an established payment history.
Explore our auto refinancing guide, early car loan payoff guide, and auto financing options.
Common Prequalification Mistakes to Avoid
Assuming every prequalification is a soft pull
Always review the lender’s specific credit-check policy.
Believing preapproval guarantees funding
Final eligibility often depends on verified information and underwriting conditions.
Applying without comparing APR
A low advertised payment can conceal a longer term or higher overall borrowing cost.
Ignoring origination fees
Fees can change the effective cost and the amount of funds actually received.
Sharing information with unverified websites
Unnecessary submissions can create privacy concerns, especially through third-party marketing websites.
Confusing soft inquiries with credit accounts
A soft inquiry does not directly affect credit scoring, but opening a new credit account may influence several scoring factors.
Assuming all applications receive rate-shopping protection
Special inquiry grouping is limited to qualifying loan categories and applicable scoring models.
Ignoring errors on credit reports
Review credit reporting information periodically and challenge genuine inaccuracies.
Credit Monitoring After Prequalification
Even after answering does prequalification affect credit score, borrowers should understand how to monitor subsequent credit activity.
Review your inquiry history
Check the names of creditors that accessed your reports and the type of inquiry recorded.
Investigate unfamiliar hard inquiries
If you find an inquiry you do not recognize, contact the creditor and the relevant credit bureau for clarification.
Dispute inaccurate information
When an inquiry or account is reported inaccurately, follow the applicable credit reporting dispute process.
Submitting a dispute does not guarantee removal of an accurately reported inquiry.
Monitor newly opened accounts
Look for unfamiliar accounts or unexpected changes to existing balances and credit limits.
Maintain consistent repayment habits
Paying obligations on time and managing revolving balances responsibly generally matters more over time than worrying about a single legitimate inquiry.
Related Best Finance Live Guides
Explore these resources for additional information about borrowing, credit scores, auto financing, and financial management.
- How Credit Scores Are Calculated
- How Long to Raise Your Credit Score
- Highest Credit Score
- 650 Credit Score Personal Loan
- Personal Loan Without Origination Fees
- What Is a Finance Charge?
- Average Credit Card Debt
- Personal Finance Guide
- Master Your Money
- Top Financial Tips
- First-Time Auto Loan
- Best Auto Finance Deals
- Affordable Auto Loans
- Good APR for a Car Loan
- Auto Finance Calculator
- New vs Used Car Interest Rates
- Average Car Payment 2026
- How Much Down Payment for a Car?
- Subprime Auto Loans
- Refinancing Auto Loans
Conclusion
So, does prequalification affect credit score? In most cases, an initial prequalification using a soft inquiry does not lower your credit score. However, not every lender follows the same procedure, and a formal application may trigger a hard inquiry.
Prequalification can help you compare estimated loan rates and eligibility requirements, but it does not guarantee final approval.
Before applying, confirm the type of inquiry, compare APR and repayment costs, and read the lender’s disclosures.
For mortgages, auto loans, and student loans, special rate-shopping provisions may help reduce the scoring impact of multiple qualifying hard inquiries made within a relevant period.
Ultimately, understanding does prequalification affect credit score allows you to shop for financing more confidently while making responsible credit decisions.