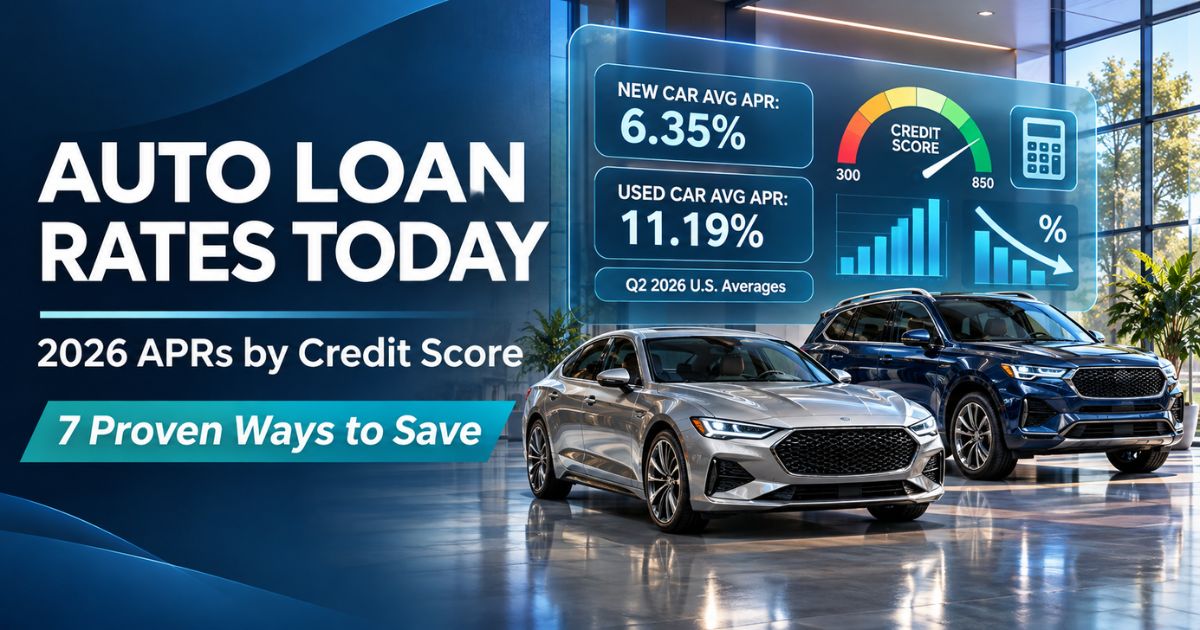
In the United States, average new-car loan rates were 6.35%, while used-car loans averaged 11.19% during the second quarter of 2026, according to Experian. These figures represent completed financing transactions rather than guaranteed rates for individual borrowers.
When comparing auto loan rates today, remember that a lender’s advertised annual percentage rate may differ substantially from your final offer. Credit history, income, existing debt, collateral value, and financing terms all influence borrowing costs.
This guide explains verified 2026 APR averages by credit score, new versus used vehicle financing, monthly payment calculations, lender comparisons, and seven practical ways to reduce interest expenses.
For additional financing information, explore our good car loan APR guide, auto finance calculator, and average car payment comparison.
Key Takeaways
- Experian reported a 6.35% average new-car APR and 11.19% average used-car APR in Q2 2026.
- Average APRs differ significantly between credit score tiers.
- Excellent-credit borrowers generally receive more competitive offers.
- Used-vehicle financing commonly carries higher rates than new-vehicle financing.
- Down payments reduce the principal amount and may improve financing eligibility.
- Longer repayment periods generally increase total interest costs.
- Comparing multiple lenders can help identify competitive financing.
- Advertised APRs and historical averages are not guaranteed personal offers.
Auto Loan Rates Today: Average APRs by Credit Score
Understanding auto loan rates today begins with reviewing reliable lending data. Average loan rates reflect borrowing conditions across different credit profiles and vehicle categories.
Experian’s Q2 2026 State of the Automotive Finance Market data provides a useful benchmark for comparing financing costs.
Verified average auto loan APRs for 2026
| Credit Score Range | New Car APR | Used Car APR |
|---|---|---|
| Super Prime (781–850) | 4.41% | 6.29% |
| Prime (661–780) | 6.15% | 8.81% |
| Near Prime (601–660) | 9.71% | 13.93% |
| Subprime (501–600) | 13.52% | 19.10% |
| Deep Subprime (300–500) | 16.11% | 21.62% |
Source: Experian’s average auto loan interest rates report, published September 10, 2026, using Q2 2026 financing data and VantageScore 4.0 credit score categories.
These figures are historical national averages, not live November 2026 quotes. Individual lenders may use different credit scoring models and pricing criteria.
What the averages tell borrowers
Drivers with stronger credit histories generally obtain lower APRs because lenders associate those profiles with lower repayment risk.
For example, the average new-car rate for super-prime borrowers was 4.41%, compared with 16.11% for deep-subprime borrowers.
That difference can produce a substantial variation in the total cost of financing the same vehicle.
Why averages change over time
Auto financing rates respond to broader market conditions, including lender funding costs, competition, consumer credit performance, and economic expectations.
As a result, auto loan rates today may not match quarterly averages published several months earlier.
Use the figures as benchmarks and compare current written offers before making a financing decision.
How Credit Scores Affect Auto Loan APR
Credit history is one of several factors lenders evaluate when determining financing eligibility and interest rates.
Super-prime borrowers
Consumers with scores from 781 to 850 in Experian’s reported VantageScore categories generally received the lowest average rates.
A strong credit profile may also improve eligibility for promotional manufacturer financing, subject to the lender’s requirements.
Prime borrowers
Prime borrowers typically have favorable credit histories and may qualify for competitive bank, credit union, or dealer-arranged financing offers.
However, rates can still vary substantially between institutions.
Near-prime borrowers
Borrowers in the 601–660 range may encounter higher financing costs.
Income stability, debt obligations, vehicle value, and down payment size can become particularly important during underwriting.
Subprime borrowers
Consumers with weaker credit histories generally face higher APRs and potentially more restrictive loan conditions.
Some lenders may require larger down payments or approve smaller amounts.
Deep-subprime borrowers
Applicants with significant credit challenges may face particularly expensive financing.
Consider improving credit, purchasing a less expensive vehicle, or increasing savings before accepting an unaffordable offer.
Different lenders use different scoring models
Experian’s published categories use VantageScore 4.0. Individual auto lenders may evaluate other VantageScore versions, base FICO Scores, specialized FICO Auto Scores, or internal risk models.
Therefore, your score from a credit monitoring application may not match the score used for underwriting.
Before comparing auto loan rates today, understand which scoring model your prospective lender uses when possible.
For more information, review our credit score factors guide and credit score improvement guide.
New Car Financing vs Used Vehicle Interest Rates
New and used vehicle loans often have different pricing structures.
Experian’s Q2 2026 report found that used-car financing carried a significantly higher average APR than new-car financing.
Why new-car rates may be lower
New vehicles sometimes qualify for manufacturer-supported promotional financing.
Lenders may also view some new vehicles as more predictable collateral because their age, mileage, warranty status, and purchase value are easier to establish.
Why used-car interest rates may be higher
Used vehicles differ in age, condition, mileage, and resale value.
These characteristics can influence the risk a lender associates with the collateral.
Some financial institutions also restrict financing for vehicles exceeding certain mileage or age limits.
Manufacturer financing programs
Automakers sometimes offer promotional APRs for selected new vehicles and qualifying applicants.
Eligibility may depend on credit score, model, location, term length, and the date of purchase.
Bank and credit union financing
Banks and credit unions may finance new or used vehicles under their own underwriting criteria.
Some institutions offer relationship discounts or different rates for qualified members.
No lender category consistently guarantees the lowest APR for every applicant.
Compare the full transaction cost
Even if new-car financing offers a lower interest rate, the higher purchase price may result in a larger required payment.
A lower-priced used vehicle with a higher APR could still cost less overall.
When researching auto loan rates today, evaluate the purchase price and financing expense together.
Read our new versus used car rates guide and private-party financing guide.
What Determines Your Auto Loan Interest Rate?
Financial institutions evaluate multiple factors beyond the advertised APR.
Credit history
Payment records, outstanding balances, recent credit activity, and negative accounts can influence underwriting decisions.
Debt-to-income ratio
Debt-to-income ratio compares qualifying monthly debt payments with gross monthly income.
A higher ratio may indicate that the borrower has less room in the budget for another payment.
Down payment amount
A larger down payment reduces the amount borrowed and may reduce the lender’s exposure.
However, the exact effect on APR depends on the lender and transaction.
Loan-to-value ratio
Loan-to-value ratio compares the financing amount with the lender’s assessed vehicle value.
A high LTV may increase financial risk, particularly when the vehicle depreciates.
Loan term length
Repayment terms influence monthly affordability and total interest costs.
Longer terms may also come with different rates or eligibility restrictions.
Vehicle characteristics
The vehicle’s age, mileage, condition, title status, and purchase source can affect loan eligibility and pricing.
Dealer-arranged financing
A dealership may submit the buyer’s application to outside financing sources and present approved offers.
In some arrangements, a dealer may receive compensation through a markup above the lender’s underlying approval rate.
Therefore, auto loan rates today should be compared across direct lenders and dealership offers whenever practical.
How Loan Terms Change Monthly Payments
Many consumers focus on obtaining the smallest monthly installment.
However, borrowing costs depend on both the interest rate and the number of months required to repay the loan.
Example: Financing a $30,000 vehicle
Assume a $30,000 financed balance with fixed-rate monthly amortization and no additional fees.
| APR | Loan Term | Monthly Payment | Total Interest |
|---|---|---|---|
| 6.5% | 60 Months | $586.98 | $5,219.07 |
| 6.5% | 72 Months | $504.30 | $6,309.45 |
| 8.0% | 60 Months | $608.29 | $6,497.51 |
| 10.0% | 60 Months | $637.41 | $8,244.68 |
These figures are hypothetical, calculated using standard monthly amortization and rounded to cents. They are not actual lender quotations.
What happens when the APR increases?
On the same $30,000 loan over 60 months, the example at 10% APR costs substantially more than the example at 6.5% APR.
A higher rate increases both the monthly installment and cumulative interest.
What happens when the term increases?
Extending the repayment period from 60 to 72 months at 6.5% lowers the scheduled payment but increases total interest.
The buyer remains responsible for payments for an additional year.
Understand negative equity
Negative equity occurs when the outstanding balance exceeds the vehicle’s market value.
Longer terms and small down payments may increase the risk of remaining upside down on a loan.
Use payment calculators carefully
Include the amount financed, estimated interest rate, loan duration, taxes, fees, and trade-in adjustments.
When evaluating auto loan rates today, compare total repayment amounts rather than selecting a loan solely by monthly payment.
Explore our long-term auto loan guide, negative equity guide, and car down payment guide.
How to Get Preapproved for a Car Loan
Preapproval can help establish your financing budget before negotiating with a dealership or private seller.
Review your credit reports
Check for inaccurate balances, unfamiliar accounts, and reporting errors.
Correcting legitimate errors before applying may help lenders review an accurate credit profile.
Prepare financial documents
Depending on the lender, you may need:
- Government-issued identification.
- Proof of income.
- Residential address.
- Employment information.
- Current debt details.
- Requested financing amount.
- Vehicle information.
Compare several lenders
Consider banks, credit unions, and eligible online auto lenders.
Ask about APR, repayment terms, fees, down payment requirements, and vehicle restrictions.
Understand soft and hard inquiries
Some institutions offer initial prequalification using soft credit inquiries.
Formal applications may require hard inquiries that can temporarily affect credit scores.
For certain auto loan inquiries, credit scoring models may group qualifying applications made within applicable rate-shopping windows.
Compare direct financing with dealer offers
Receiving an independent financing offer gives you a benchmark when negotiating at a dealership.
Dealers may be able to present competitive offers, including manufacturer promotional programs.
Compare auto loan rates today using consistent loan amounts and similar repayment terms.
Read our credit prequalification guide and first-time auto loan guide.
How to Compare Banks, Credit Unions, and Dealership Financing
Different financing sources may offer different rates, fees, eligibility standards, and loan structures.
Traditional banks
Banks may provide direct financing and convenient account management.
Existing customers may qualify for certain relationship benefits, depending on the institution.
Credit unions
Credit unions provide member-based financial services and may offer competitive vehicle financing.
Membership qualifications and loan policies vary.
Dealer-arranged financing
Dealerships may submit applications to multiple financing sources.
This offers convenience but does not guarantee the lowest available rate.
Manufacturer financing
Some vehicle manufacturers advertise promotional APRs for selected models.
Offers may be limited to certain borrowers, terms, vehicles, and promotional periods.
Compare the complete loan offer
| Loan Feature | What to Review |
|---|---|
| APR | Annualized borrowing cost |
| Loan Amount | Total principal financed |
| Monthly Payment | Required installment |
| Repayment Term | Total number of months |
| Finance Charge | Cost of credit disclosed in the contract |
| Optional Add-ons | Additional products and their prices |
The Consumer Financial Protection Bureau’s auto loan comparison guide recommends reviewing APR, interest rate, loan amount, term, and monthly payment rather than focusing on one number.
7 Proven Ways to Find a Better Auto Loan Rate
1. Check your credit before applying
Review your credit profile early and dispute genuine reporting errors.
Improving payment habits and reducing revolving balances may strengthen your credit standing over time.
2. Compare multiple lenders
Request financing offers from suitable banks, credit unions, and dealerships.
Comparing written offers can help identify a more competitive APR.
3. Increase your down payment when affordable
A larger contribution reduces principal and may improve the loan-to-value ratio.
However, maintain enough emergency savings for unexpected expenses.
4. Choose a reasonable repayment term
A shorter term often reduces cumulative interest but requires larger monthly payments.
Choose a schedule that fits essential household expenses.
5. Negotiate the vehicle price separately
Agree on the full out-the-door price before evaluating financing arrangements.
This helps prevent monthly payment discussions from hiding a more expensive purchase.
6. Avoid unnecessary financed products
Review extended service contracts, protection packages, and other optional products carefully.
Financing these items increases the outstanding balance and may increase interest costs.
7. Consider waiting or buying a less expensive vehicle
If available offers are unaffordable, delaying the purchase may allow time to improve credit or save more money.
A less expensive vehicle may reduce borrowing needs even when the APR remains unchanged.
These seven steps help consumers evaluate auto loan rates today without relying on misleading guarantees or payment-focused sales tactics.
Common Auto Loan Mistakes to Avoid
Focusing only on monthly installments
A low payment can result from a longer loan term rather than a favorable financing rate.
Assuming advertised rates apply to everyone
The lowest promotional APR may require excellent credit, a particular vehicle, or specific financing conditions.
Ignoring dealership add-ons
Optional products can increase the amount financed and total repayment cost.
Overlooking negative equity
Rolling unpaid balances from a previous vehicle into another loan increases borrowing costs.
Skipping preapproval
Without independent financing estimates, buyers may have fewer reference points for negotiating a competitive offer.
Ignoring the full purchase price
Taxes, registration, documentation fees, and other charges can increase the total amount financed.
Failing to read the agreement
Confirm the APR, finance charge, amount financed, total payments, due dates, and optional products before signing.
Understanding auto loan rates today should lead to better decisions about the full purchase, not only the advertised interest rate.
Auto Loan Rates Today: Final Buyer Checklist
- Check recent published rate benchmarks.
- Review your credit profile.
- Set a realistic transportation budget.
- Compare new and used vehicle options.
- Request the out-the-door price.
- Calculate taxes and registration expenses.
- Decide on an affordable down payment.
- Compare bank and credit union offers.
- Review dealer-arranged financing.
- Check applicable manufacturer promotions.
- Compare APR and finance charges.
- Review loan term length.
- Calculate total interest.
- Evaluate negative-equity risk.
- Read all financing disclosures.
- Keep copies of signed documents.
Related Best Finance Live Guides
- What Is a Good APR for a Car Loan?
- Auto Finance Calculator
- Average Car Payment 2026
- New vs Used Car Interest Rates
- How Much Down Payment for a Car?
- How to Lower Car Payment
- Auto Loan Refinancing
- Private Party Car Loans
- First-Time Auto Loan Guide
- Negative Equity Car Loans
- 96-Month Auto Loan Guide
- Subprime Auto Loans
- Paying Off a Car Loan Early
- Best Auto Finance Deals
Conclusion
Comparing auto loan rates today is an important step toward choosing affordable vehicle financing.
Experian’s Q2 2026 averages demonstrate how strongly credit profiles and vehicle types influence borrowing costs. However, these averages should not be confused with guaranteed offers available from individual lenders.
Review your credit history, compare several financing sources, choose a reasonable loan term, and calculate the full cost of borrowing.
Also consider how vehicle price, down payment, insurance, maintenance, and depreciation affect your budget.
Ultimately, researching auto loan rates today should help you select a financing arrangement that balances affordable monthly installments with responsible long-term repayment.