AGCO Finance provides financing solutions for agricultural equipment through a dealer-focused model designed around the needs of farming businesses. In the United States, financing can be arranged for eligible equipment purchases or leases, while approval, rates, payment schedules, and other terms depend on the applicant and transaction.
For a farmer comparing farm equipment financing, the monthly payment is only one part of the decision. Equipment price, amount financed, trade-in value, repayment timing, insurance, optional services, and total financing cost all matter.
This guide explains how the financing program works, what to expect from an AGCO Finance application, how new and used machinery may be financed, and what to compare before signing an agreement.
Editorial disclosure: Best Finance Live is an independent educational website and is not affiliated with, endorsed by, or acting on behalf of AGCO Corporation, AGCO Finance LLC, DLL, Rabobank, Fendt, or Massey Ferguson.
For broader background on commercial borrowing, see our business loans guide and business finance overview.
Key Takeaways
- The financing provider specializes in agricultural equipment and related dealer-based solutions.
- Current U.S. information emphasizes tailored payment terms that can reflect farm cash flow.
- Financing may be structured around owning equipment or using it through a lease-style arrangement.
- Applications remain subject to credit review, approval, terms, and conditions.
- There is no single public financing rate that applies to every farmer, machine, or promotion.
- Used equipment requires careful review of value, remaining useful life, repairs, and financing term.
- Brand-specific promotions may be available, but offers can change.
- Compare the total contractual obligation instead of choosing only by the payment amount.
1. What Is AGCO Finance?
AGCO Finance is the worldwide financing provider associated with AGCO agricultural equipment. Its current U.S. website lists support for brands including Fendt, Massey Ferguson, PTx, and AGCO Parts & Service.
The company works with local dealers and describes its approach as tailored financing designed around agricultural market conditions and business cash flow.
Visit the official U.S. financing website.
Who owns the financing business?
The company’s official history states that the business was founded in 1990 through a partnership between AGCO and DLL. It is now wholly owned by DLL while maintaining a dedicated financing relationship with AGCO.
DLL is the finance subsidiary of Rabobank.
Read the official company background.
Understanding the lender, ownership structure, and contract terms is an important part of business financial management.
2. How AGCO Equipment Financing Works
AGCO equipment financing is commonly coordinated through an authorized dealer. The dealer and financing specialists can help structure a proposal around the equipment, amount being financed, and the customer’s business situation.
The current U.S. solutions page states that financing can cover equipment, parts, and services through local dealers.
Review current U.S. financing solutions.
What may be included in the financing discussion?
Depending on the transaction, a farmer may need to compare:
- equipment cash price;
- trade-in value;
- down payment or upfront contribution;
- amount financed;
- interest or financing rate;
- fees;
- payment frequency;
- repayment term;
- insurance or protection products;
- maintenance or service products; and
- ownership or return conditions.
Our business loan interest rates guide explains why rate, term, fees, and amount financed should be compared together.
3. AGCO Equipment Loan vs Equipment Leasing
An AGCO equipment loan and an equipment leasing arrangement do not create the same ownership path. Broader financing materials describe the basic choice as financing to own or financing to use, subject to local availability.
Financing to own
With an ownership-focused structure, the business makes payments under the agreement and owns the equipment when the applicable financing obligations have been satisfied.
Before signing, confirm:
- when ownership transfers;
- whether the equipment secures the obligation;
- payment amount;
- payment frequency;
- contract term;
- interest or financing cost;
- fees;
- early-payoff provisions; and
- default terms.
Financing to use
A lease-style arrangement may allow a farm to use equipment for a defined period without following the same ownership path as a conventional loan.
End-of-term choices and obligations depend on the product and contract.
Do not assume leasing automatically creates the lowest total cost. Compare scheduled payments, residual or purchase options, usage conditions, return obligations, fees, and tax considerations.
For broader borrowing principles, see our financial success strategies and finance charge guide.
4. New and Used Farm Equipment Financing
Farm machinery financing should be evaluated differently for new and pre-owned equipment because the purchase price is only one part of the decision.
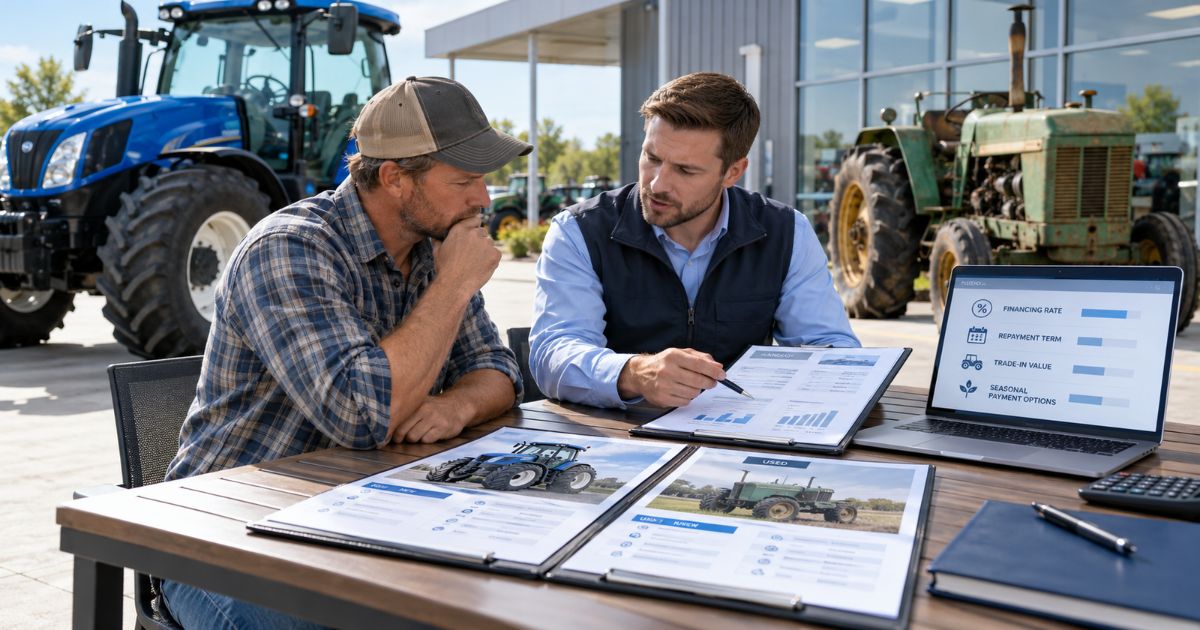
New agricultural equipment
New machinery may provide access to current technology, warranty coverage, dealer support, and manufacturer promotions.
However, an attractive promotional rate does not automatically make a more expensive machine the best financial choice.
Used farm equipment financing
Used farm equipment financing can reduce the purchase price, but the buyer should also consider:
- equipment age;
- operating hours;
- maintenance history;
- repair requirements;
- remaining useful life;
- resale value;
- insurance cost; and
- whether the financing term is reasonable for the expected life of the machine.
The U.S. website provides access to pre-owned equipment resources, but exact financing eligibility and contract terms should be confirmed for the individual machine.
Our business lending guide explains why asset value and debt should be considered together.
5. AGCO Finance Rates and Promotional Offers
There is no universal AGCO Finance rate that applies to every farmer or equipment purchase.
Actual financing cost may depend on factors such as:
- equipment model;
- new or used status;
- amount financed;
- repayment term;
- applicant financial profile;
- dealer participation;
- current promotion; and
- other underwriting considerations.
Promotional rates can change
Brand-specific programs can offer reduced promotional rates on selected machines.
For example, the official Fendt U.S. financing page currently publishes model-specific offers and states that they remain subject to credit review, approval, dealer participation, and change without notice.
Check current Fendt financing offers.
Compare more than the advertised rate
When reviewing a proposal, record:
- equipment cash price;
- trade-in credit;
- amount financed;
- financing rate;
- fees;
- term;
- payment frequency;
- balloon or final payment, if applicable;
- total required payments; and
- end-of-contract obligations.
A promotional rate may be useful, but the equipment price and contract structure still matter. Our business loan rate guide and finance charge guide can help with comparisons.
6. Flexible Payments and Seasonal Farm Cash Flow
Agricultural businesses often receive income unevenly throughout the year. Commodity prices, harvest timing, weather conditions, livestock cycles, and input expenses can affect when cash is available.
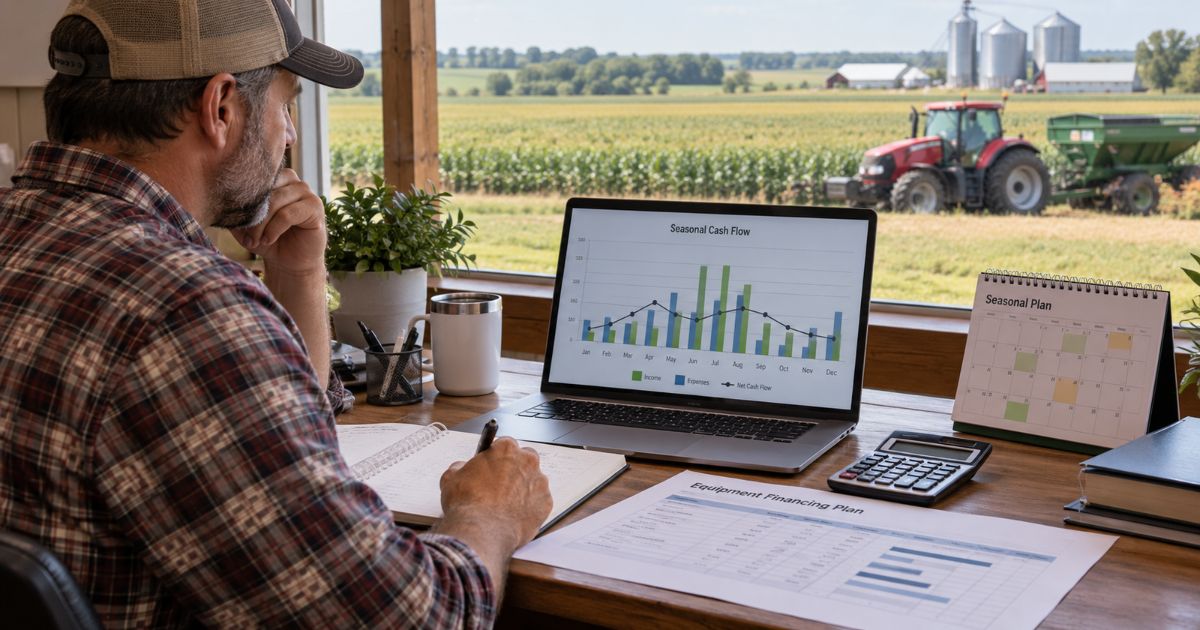
The U.S. website emphasizes tailored financing conditions that can align payments with business cash flow. Broader company materials also describe seasonal, deferred, and balloon-payment structures, while noting that products depend on local availability.
Build payment schedules around realistic cash flow
Before accepting agricultural equipment financing, test the payment schedule against more than one cash-flow scenario.
Your forecast may need to include:
- expected crop or livestock revenue;
- commodity-price changes;
- fuel expenses;
- seed and other inputs;
- labor;
- repairs;
- existing equipment debt;
- insurance;
- tax obligations; and
- working-capital requirements.
A seasonal payment structure should remain manageable even when revenue is lower than expected.
Our business finance strategies and finance tips for entrepreneurs cover cash-flow planning in greater detail.
7. How the AGCO Finance Application Works
The official U.S. AGCO Finance application can be started online for eligible equipment purchases or leases.
Open the official U.S. credit application.
Applications remain subject to approval
The application page states that applications are subject to further credit review, approval, and other terms and conditions.
Submitting an application therefore does not guarantee financing.
Information requested can vary
The online application begins with details including applicant type, equipment use, country, and desired financing amount.
Additional financial or business information may be requested as the process continues.
The U.S. privacy statement explains that credit decisions can involve evaluation of credentials, creditworthiness, payment history, and financial status.
Review the official U.S. privacy statement.
There is no universal 24–48 hour final-approval promise
The U.S. site describes fast credit decisions, but it does not publish a guarantee that every applicant receives final approval within a fixed 24- or 48-hour period.
Processing time can vary according to the applicant, financing amount, business structure, documents, equipment, dealer, and underwriting review.
Documentation requirements can differ
Do not assume that every applicant must provide exactly the same number of tax returns, financial statements, or other records.
Ask the participating dealer or financing representative what documents are needed for your specific application.
For general application preparation, review our entrepreneur finance guide.
8. Parts, Service, Insurance, and Aftersales Financing
The financing relationship can extend beyond the initial machine purchase.
The current U.S. solutions page states that equipment, parts, and services can be financed through participating dealers.
AGCO Plus+
AGCO Plus+ is presented as a flexible payment solution for qualifying aftersales purchases.
Eligibility, rates, account terms, and participating dealers should be confirmed before using the product.
Physical damage insurance
The U.S. site also describes physical damage insurance for financed new and used equipment.
It states that premiums can be incorporated into loan payments, while actual insurance coverage remains subject to the policy’s terms, conditions, and exclusions.
Review current equipment, service, and protection options.
Insurance and service expenses should be included in the full equipment budget. See our financial planning guide for a broader approach.
9. Compare AGCO Finance With Other Farm Financing
Dealer convenience can be valuable, but AGCO Finance should still be compared with other realistic funding sources when alternatives are available.
Possible financing alternatives may include:
- commercial banks;
- agricultural lenders;
- Farm Credit institutions;
- equipment-finance companies;
- other manufacturer financing programs; and
- business lenders.
Use a side-by-side comparison
| Financing Detail | Dealer or Manufacturer Offer | Alternative Offer |
|---|---|---|
| Equipment Cash Price | _____ | _____ |
| Trade-In / Upfront Amount | _____ | _____ |
| Amount Financed | _____ | _____ |
| Financing Rate | _____ | _____ |
| Fees | _____ | _____ |
| Term | _____ | _____ |
| Payment Frequency | _____ | _____ |
| Balloon / Final Payment | _____ | _____ |
| Total Required Payments | _____ | _____ |
| Ownership / Return Terms | _____ | _____ |
For additional comparisons, use our business loans guide and business loan interest rates guide.
Fendt Financing
Fendt financing is one example of brand-specific manufacturer financing connected with the broader agricultural dealer network.
The official Fendt U.S. page publishes promotional financing on selected models and states that offers are subject to credit review, approval, participating dealers, and change without notice.
Because offers can change, use the current official page and dealer quote rather than relying on an older promotional rate from a third-party article.
Our financial tips guide can help you compare an attractive promotional rate with the wider equipment cost.
Massey Ferguson Financing
Massey Ferguson financing may also be available through the broader equipment-financing relationship because Massey Ferguson is listed among the supported AGCO brands on the current U.S. site.
Confirm eligible models, dealer participation, current promotions, payment structure, and final contract terms before making a purchase decision.
Questions to Ask Before Signing Farm Equipment Financing
Before accepting farm equipment financing, ask:
- What is the equipment cash price?
- What trade-in value is being credited?
- How much am I financing?
- What financing rate applies?
- What fees apply?
- How frequently are payments due?
- How long is the contract?
- Are payments seasonal or deferred?
- Is there a balloon or final payment?
- Is the agreement a loan, lease, or another structure?
- When does ownership transfer?
- What insurance is required?
- Which service products are optional?
- What are the early-payoff or early-termination terms?
- What happens after a late or missed payment?
- What are the end-of-contract obligations?
Use our business financial management guide to test the proposed payment against operating cash flow.
Common Farm Equipment Financing Mistakes to Avoid
Assuming a promotional rate applies to every machine
Promotions can be limited by equipment model, term, borrower eligibility, participating dealer, and offer period.
Choosing only by payment size
A smaller scheduled payment can result from a longer term, deferred structure, or larger final obligation.
Using optimistic cash-flow assumptions
A repayment structure should remain manageable if commodity prices decline, production changes, or operating expenses rise.
Assuming approval is automatic
The official online application remains subject to further credit review and approval.
Assuming every decision arrives within 24 to 48 hours
The company promotes fast credit decisions but does not publish a universal final-approval timeframe for every application.
Assuming there is never an early repayment charge
Review the actual financing contract. Early-payoff and early-termination provisions can depend on the product and agreement.
Skipping outside comparisons
Even when dealer financing is convenient, compare another appropriate lender when practical.
Our financial strategy guide provides a useful framework for evaluating major borrowing decisions.
Customer Service and Account Support
Existing customers should use official U.S. account and contact resources for current payment instructions and customer-service details.
The current U.S. credit-application page lists (888) 989-8525 for application questions.
Verify current application contact information.
For account-specific instructions, use the official account-access resources provided by the financing company rather than sending payment information through an unverified link.
Frequently Asked Questions
What is AGCO Finance?
AGCO Finance is an agricultural equipment-financing provider associated with AGCO brands and local dealers. It offers tailored financing solutions for eligible equipment and related agricultural needs.
How do I Get AGCO Finance?
People searching for Get AGCO Finance can begin by contacting an authorized participating dealer or using the official U.S. online credit application where appropriate. Financing remains subject to underwriting and approval.
Can I apply online?
Yes. A U.S. online credit application is available. Depending on the applicant type or transaction, dealer involvement may still be necessary.
Can I finance used farm equipment?
Pre-owned machinery may be eligible for financing, but equipment value, age, condition, program requirements, and financing term should be confirmed with the dealer.
Does the company offer equipment leasing?
Financing materials describe both ownership-focused and use-focused structures. Exact lease availability and end-of-term conditions depend on the local product and contract.
Are seasonal payments available?
The company emphasizes tailored payment terms, and broader materials describe seasonal payment structures. Availability should be confirmed for the specific transaction.
What interest rate will I receive?
There is no single rate for every borrower. Financing cost may depend on equipment, term, applicant profile, promotion, dealer participation, and underwriting.
How fast is financing approval?
The U.S. site promotes fast credit decisions but does not guarantee that every application will receive final approval within a specific number of hours.
Is there a prepayment penalty?
The available source information does not support a universal yes-or-no answer. Review the actual contract for early-payoff or early-termination provisions.
Does AGCO Finance support Fendt and Massey Ferguson?
Yes. The current U.S. website lists both Fendt and Massey Ferguson among the AGCO brands it supports.
Conclusion
AGCO Finance can provide a convenient way to arrange agricultural equipment financing through local dealers, with financing designed around eligible machinery and the operating realities of farming businesses.
The strongest financing choice is not necessarily the one with the smallest payment or lowest advertised promotional rate. Compare the equipment cash price, amount financed, financing rate, fees, contract term, payment schedule, insurance, optional services, ownership structure, and total contractual obligation.
Current official information supports tailored financing, dealer-based access, equipment and aftersales solutions, and flexible structures. It does not support describing every transaction as guaranteed low-interest financing, automatic approval, or a fixed 24-to-48-hour final decision.
Before signing, use the current official dealer quote and contract, compare another financing source when practical, and make sure the payment structure remains workable under realistic farm cash-flow conditions.
Continue with our business loans guide and business finance guide for broader commercial financing information.