A finance charge on a loan is an important number to understand before borrowing money. In consumer credit, the finance charge generally represents the dollar cost of credit and can include interest plus certain other charges imposed as an incident to or condition of extending credit.
However, not every fee connected with a purchase or loan is automatically a finance charge. The treatment of a particular charge depends on the type of transaction and the rules that apply.
This guide explains seven key facts about finance charges, including what they can include, how they differ from interest and APR, where to find them in loan disclosures, and how to compare borrowing costs.
Finance Charge on a Loan: Quick Definition
Under the federal Truth in Lending framework, a finance charge on a loan is generally the cost of consumer credit expressed as a dollar amount.
Interest is normally part of the finance charge. Certain other charges may also be included when they are imposed directly or indirectly by the creditor as an incident to or condition of extending credit.
By contrast, a charge that would also be payable in a comparable cash transaction generally is not treated as a finance charge merely because the purchase was financed.
Understanding this distinction helps you evaluate the actual cost of borrowing rather than assuming every dollar associated with a transaction is a credit cost.
If you are building your overall financial knowledge, our personal finance guide covers budgeting, debt, credit, saving, and financial planning.
1. A Finance Charge Is More Than Just the Interest Rate
The first important distinction is between a finance charge and an interest rate.
An interest rate is generally the percentage rate used to calculate interest on borrowed money. A finance charge, by contrast, is expressed as a dollar amount and can include interest plus certain additional credit-related charges.
| Term | What It Generally Shows |
|---|---|
| Interest Rate | The percentage rate charged on borrowed funds |
| Finance Charge | The dollar cost of consumer credit under applicable disclosure rules |
| APR | The cost of credit expressed as an annual rate |
| Amount Financed | The amount of credit provided to you or on your behalf under the disclosure rules |
| Total of Payments | The total amount scheduled to be paid after making all payments as scheduled |
These figures answer different questions, so you should not use the terms interchangeably.
Finance Charge vs Interest
Suppose a loan requires $1,200 in interest and also includes a $200 fee that qualifies as a finance charge under applicable rules.
The interest cost is $1,200, while the disclosed finance charge could be $1,400.
This is a simplified illustration. Whether a particular fee must be included depends on the nature of the charge and the applicable disclosure requirements.
For additional borrowing-cost concepts, see our guide to financial success strategies.
2. What Can Be Included in a Finance Charge?
Understanding what can be included in a finance charge on a loan is important because interest is only one possible component. Regulation Z identifies other types of charges that may qualify depending on the transaction.
Potential examples can include:
- interest and time-price differential;
- certain service, transaction, activity, or carrying charges;
- certain loan or origination fees;
- certain credit-related insurance premiums when applicable requirements for exclusion are not satisfied;
- certain other charges imposed as an incident to or condition of credit.
The exact treatment matters because a fee being connected with a loan does not automatically make it part of the disclosed finance charge.
Not Every Fee Is a Finance Charge
One of the biggest misconceptions is that every cost appearing in a financed transaction belongs in the finance charge.
For example, CFPB Truth in Lending guidance explains that charges payable in a comparable cash transaction are generally not finance charges. In an auto purchase, examples can include taxes, title fees, license fees, or registration fees when they are also imposed in comparable cash transactions.
This distinction is particularly useful when comparing auto financing, where the total transaction can contain both credit costs and ordinary vehicle-purchase costs.
3. How to Calculate a Finance Charge on a Loan
There is no single simple formula that accurately calculates the disclosed finance charge for every type of consumer credit transaction.
Loan structure, payment timing, interest calculation method, qualifying fees, and other terms can affect the result.
Simple Interest Example
For a basic one-year simple-interest illustration:
Interest = Principal × Interest Rate × Time
If you borrow $10,000 at a 5% annual simple interest rate for one year:
$10,000 × 0.05 × 1 = $500
The interest in this simplified example is $500.
If no additional qualifying finance charges apply, the finance charge may correspond to that interest amount. If other charges that qualify as finance charges apply, the disclosed finance charge can be different.
Why Real Installment Loans Are More Complicated
Many installment loans require periodic payments that reduce the outstanding principal over time. Interest may therefore be calculated using the remaining balance rather than the original principal for the entire term.
Payment timing also matters. That is why simply multiplying the original principal by a rate and the number of years may not reproduce the disclosures for every real loan.
For vehicle financing, an auto finance calculator can help you understand how loan amount, rate, and term affect estimated payments and interest.
4. Finance Charge vs APR: What Is the Difference?
The finance charge and Annual Percentage Rate (APR) both help consumers understand borrowing costs, but they express those costs differently.
The finance charge is expressed as a dollar amount. APR measures the cost of credit as an annual rate and takes into account the amount and timing of credit and payments under the applicable calculation rules.
| Finance Charge | APR |
|---|---|
| Expressed in dollars | Expressed as an annual percentage rate |
| Represents qualifying credit costs | Standardizes credit cost into an annual rate |
| Useful for seeing dollar borrowing cost | Useful when comparing similar credit offers |
APR should not simply be described as “the finance charge converted into a percentage.” The calculation also accounts for factors such as the amount financed and timing of payments.
Why APR Is Useful for Loan Shopping
Suppose two lenders advertise similar interest rates but one imposes additional charges that affect the APR.
The APR can make the difference in credit cost easier to identify, although you should still review the finance charge, amount financed, payment schedule, loan term, and total of payments.
For vehicle borrowing, our auto finance deals guide explains additional factors worth comparing.
5. Finance Charges on Different Types of Credit
The concept applies across many forms of consumer credit, but the exact disclosures and costs differ by product.
Auto Loans
For a closed-end auto loan, Truth in Lending disclosures can show important figures such as:
- APR;
- finance charge;
- amount financed;
- total of payments;
- payment schedule.
The finance charge should not simply be confused with the vehicle’s taxes, registration charges, or every dealer fee.
If you are shopping for your first vehicle, our first time auto loan guide explains how to compare APRs, terms, payments, and lenders.
You can also compare current financing concepts in our top auto finance guide.
Personal Loans
A personal loan may involve interest and an origination fee or other charges. Whether a particular fee is included in the disclosed finance charge depends on applicable Truth in Lending rules and the transaction.
When comparing personal loans, review the APR alongside the amount you actually receive, payment schedule, loan term, and total cost.
Mortgage Loans
Mortgage transactions can involve interest, points, origination charges, appraisal costs, title-related charges, mortgage insurance, taxes, and other costs.
Do not assume every closing cost is a finance charge. Mortgage disclosure rules distinguish between different categories of costs.
Credit Cards
Credit cards are open-end credit rather than ordinary closed-end installment loans. Finance charges can include interest calculated according to the card agreement and certain transaction or other credit-related charges.
Grace periods, balance-calculation methods, cash advances, and other account terms can affect costs.
6. Where Can You Find the Finance Charge?
For covered closed-end consumer credit, Truth in Lending disclosures are designed to present key credit-cost information before you become obligated.
In an auto loan, for example, look for a disclosure box containing figures such as:
| Disclosure | What to Check |
|---|---|
| Annual Percentage Rate | Annualized cost of credit |
| Finance Charge | Dollar cost of credit |
| Amount Financed | Credit provided to you or on your behalf |
| Total of Payments | Scheduled total after all payments |
| Payment Schedule | Number, amount, and timing of payments |
Do not sign simply because the monthly payment appears affordable. Check whether the APR, amount financed, and term match what you expected.
This is especially important with 0 APR car financing, where advertised promotional terms can have eligibility and vehicle restrictions.
7. How to Potentially Reduce Your Borrowing Costs
You cannot simply remove a required finance charge after agreeing to a loan, but you can take steps before borrowing that may reduce your overall cost.
Compare Multiple Loan Offers
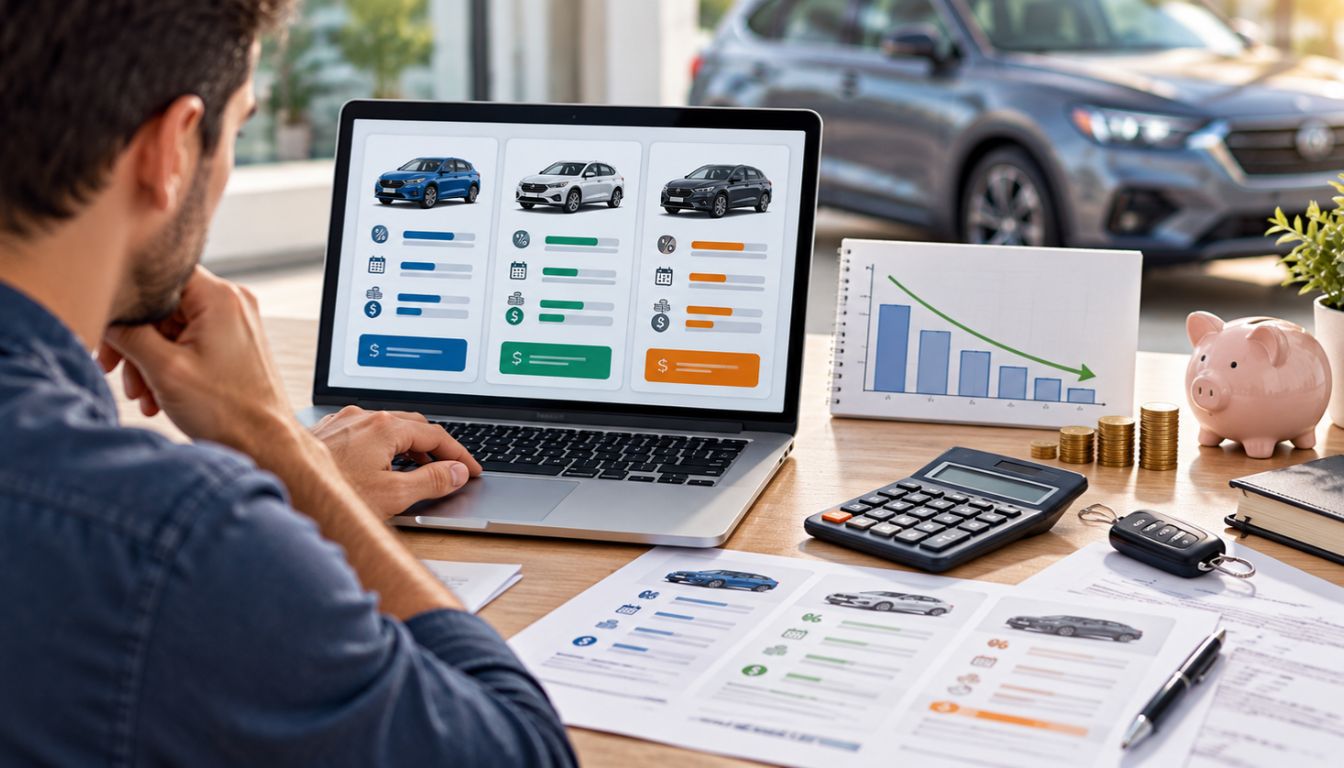
Compare lenders using similar loan amounts and terms.
Review:
- interest rate;
- APR;
- finance charge;
- amount financed;
- loan term;
- monthly payment;
- total of payments;
- applicable fees and conditions.
For auto borrowers, comparing affordable auto loan options can help illustrate how different rates and terms affect borrowing costs.
Improve Your Credit Profile Before Applying
Credit history and credit scores can affect the terms lenders offer, although underwriting standards vary.
Paying bills on time, reviewing credit reports for errors, reducing excessive debt where practical, and avoiding unnecessary new credit applications may help strengthen your credit profile over time.
Borrow Less When Practical
A larger down payment on a vehicle or choosing a less expensive purchase can reduce the amount you need to finance.
Borrowing less generally means less principal on which interest can accrue, although you should also maintain appropriate emergency savings.
Compare Loan Terms
A longer term can lower the monthly payment but may increase total interest because you remain in debt longer.
Do not choose a term solely because it creates the lowest payment.
Our used-car financing guide provides a practical example of comparing vehicle loan terms.
Understand Prepayment Terms
Making additional principal payments can reduce interest on some loans, but the effect depends on the contract and how payments are applied.
Before making extra payments, check:
- whether a prepayment penalty applies;
- how additional payments are credited;
- whether the loan uses simple interest or another structure;
- whether there are special payoff procedures.
Finance Charge vs Interest vs APR Example
Consider this simplified hypothetical loan:
| Item | Example |
|---|---|
| Loan Principal | $10,000 |
| Interest Cost | $1,000 |
| Qualifying Additional Finance Charge | $200 |
| Illustrative Finance Charge | $1,200 |
In this simplified example, the finance charge is $1,200 because it includes $1,000 of interest plus a hypothetical $200 charge that qualifies for inclusion.
The APR cannot be determined accurately from these figures alone without the additional information required by the applicable APR calculation, including the amount financed and timing of payments.
This is why APR and finance charge should not be treated as interchangeable versions of exactly the same number.
Does a Longer Loan Increase the Finance Charge?
Often, a longer repayment period can increase total interest because the outstanding balance remains unpaid for more time.
But the exact finance charge depends on the rate, amount financed, payment schedule, qualifying fees, and other loan terms.
For example, extending an auto loan from 48 months to 72 months may lower the required monthly payment while potentially increasing total interest paid.
That tradeoff is important when evaluating vehicle financing or deciding whether you can realistically afford a purchase.
Are Late Fees Part of the Finance Charge?
Do not automatically treat every late fee as part of the disclosed finance charge.
Regulation Z contains exclusions for certain charges arising from actual unanticipated late payment, delinquency, default, or similar occurrences.
This is one reason the old idea that “all fees connected with a loan are finance charges” is inaccurate.
Are Taxes Part of the Finance Charge?
Not necessarily. Taxes and government charges that apply in comparable cash transactions generally are not finance charges merely because the purchase is financed.
For example, vehicle sales tax, title, license, or registration costs can be part of the amount involved in purchasing a car without necessarily becoming a finance charge.
Is Insurance Part of the Finance Charge?
Insurance treatment depends on the type of coverage, whether it is required, how it is offered, and whether applicable conditions for exclusion are satisfied.
Therefore, it is inaccurate to say that all insurance premiums are always included—or always excluded—from the finance charge.
Review the disclosure and ask the creditor to explain any optional or required credit-related products before signing.
Finance Charges and Auto Loans
Auto financing is one of the most common places consumers encounter the term finance charge on a loan.
Before signing an auto contract, compare the finance charge with the APR, amount financed, total of payments, and payment schedule.
If you are deciding between lender types, understanding these disclosures also makes it easier to evaluate direct bank financing against dealer-arranged financing.
If affordability later becomes a problem, do not assume returning the vehicle cancels these obligations. Our guide on returning a financed car explains the potential alternatives and consequences.
If instead you plan to dispose of the vehicle while a loan remains outstanding, see how to sell a financed car.
Common Finance Charge Mistakes to Avoid
Assuming Finance Charge Means Interest Only
Interest is a major component, but certain additional charges can also qualify.
Assuming Every Fee Is a Finance Charge
Some costs are excluded, including certain charges that would also apply in a comparable cash transaction.
Comparing Only Monthly Payments
A longer term can make a loan look cheaper each month while increasing the overall cost.
Confusing APR With the Interest Rate
APR and the contract interest rate can differ because APR measures credit cost according to standardized disclosure rules.
Assuming APR Is Simply Finance Charge Divided by Loan Amount
APR calculations account for the amount and timing of credit and payments. The calculation can therefore be more complex than a simple division.
Ignoring the Amount Financed
The amount financed helps show how much credit is actually being provided under the disclosure framework. Compare it with the transaction documents and any upfront charges.
How to Compare Two Loan Offers
When comparing lenders, review the finance charge on a loan alongside the APR, interest rate, term, and total of payments.
When evaluating competing loans, use a side-by-side comparison:
| Factor | Loan A | Loan B |
|---|---|---|
| Interest Rate | Compare | Compare |
| APR | Compare | Compare |
| Finance Charge | Compare | Compare |
| Amount Financed | Compare | Compare |
| Loan Term | Compare | Compare |
| Monthly Payment | Compare | Compare |
| Total of Payments | Compare | Compare |
Try to compare offers using the same amount borrowed and similar repayment terms. Otherwise, a lower monthly payment may simply reflect a longer term rather than a less expensive loan.
Entrepreneurs evaluating borrowing for business purposes can also review our business loans guide, although commercial credit can be subject to different rules than consumer credit.
Truth in Lending Act and Finance Charges
The federal Truth in Lending Act and Regulation Z establish standardized consumer-credit disclosures designed to help borrowers understand and compare credit costs.
These disclosures make the finance charge on a loan easier to identify and compare before you become obligated on covered consumer credit.
For covered closed-end transactions, these disclosures can include the finance charge and APR along with other important terms.
The rules are detailed, and whether a particular fee is included or excluded can depend on the transaction and applicable provisions.
For that reason, consumers should rely on their actual loan disclosures rather than trying to classify every charge based solely on its name.
Official Consumer Resources
- Consumer Financial Protection Bureau: Truth in Lending Regulation Z
- Consumer Financial Protection Bureau: Regulation Z Finance Charge Rules
- Consumer Financial Protection Bureau: Interest Rate vs APR
- Consumer Financial Protection Bureau: Auto Loan Truth in Lending Disclosures
Frequently Asked Questions
What is a finance charge on a loan?
A finance charge on a loan generally represents the dollar cost of consumer credit under Truth in Lending rules. It includes interest and can include certain additional charges imposed as an incident to or condition of extending credit.
Is a finance charge the same as interest?
No. Interest is generally one component of the finance charge. Certain additional credit-related charges can also be included depending on the transaction and applicable rules.
What is the difference between finance charge and APR?
The finance charge expresses qualifying credit costs as a dollar amount. APR expresses the cost of credit as an annual rate based on standardized calculation rules involving the amount and timing of credit and payments.
Does the finance charge include every loan fee?
No. Some charges qualify as finance charges and others are excluded. A charge payable in a comparable cash transaction generally is not a finance charge merely because the transaction is financed.
Are late fees finance charges?
Certain charges resulting from actual unanticipated late payment, delinquency, default, or similar occurrences can be excluded from the finance charge under Regulation Z. Review your agreement and disclosures for the specific fee.
Is sales tax included in an auto loan finance charge?
Sales tax is not automatically a finance charge. Charges such as taxes, title, license, or registration fees that also apply to comparable cash transactions generally are not treated as finance charges solely because they are financed.
Can I reduce the finance charge on a loan?
You may be able to reduce overall borrowing costs by qualifying for better terms, borrowing less, choosing an appropriate shorter term, comparing lenders, or making additional principal payments when your contract permits and doing so makes financial sense.
Where do I find the finance charge on an auto loan?
Look at your Truth in Lending disclosures. For a covered closed-end auto loan, important figures typically include APR, finance charge, amount financed, total of payments, and the payment schedule.
Why is my finance charge higher on a longer loan?
A longer loan can keep principal outstanding for more time, allowing more interest to accrue. The exact result depends on the loan amount, rate, fees, payment schedule, and other terms.
Is a finance charge always bad?
A finance charge is a measure of borrowing cost rather than a judgment about whether borrowing is good or bad. The important question is whether the credit is affordable and whether its total cost is competitive for your circumstances.
Key Takeaways
- A finance charge on a loan generally represents the dollar cost of consumer credit.
- Interest is normally part of the finance charge, but certain additional charges can also qualify.
- Not every fee associated with a purchase or loan is automatically a finance charge.
- Charges that also apply in comparable cash transactions are generally excluded from the finance charge.
- Finance charge and APR are related but are not the same measurement.
- APR expresses credit cost as an annual rate.
- Longer loan terms can lower monthly payments while potentially increasing total interest.
- Review APR, finance charge, amount financed, total of payments, and payment schedule together.
- Truth in Lending disclosures help consumers compare covered credit transactions.
- Always review the actual loan documents before accepting financing.
Final Thoughts
Understanding the finance charge on a loan makes it easier to see what borrowing actually costs. Instead of focusing only on the interest rate or monthly payment, review the finance charge alongside APR, amount financed, loan term, payment schedule, and total of payments.
Most importantly, remember that not every cost in a financed transaction is automatically a finance charge. Truth in Lending rules determine which charges are included and excluded for disclosure purposes.
Before accepting credit, compare multiple offers using similar loan amounts and terms. A few minutes spent reviewing the disclosures can reveal meaningful differences in borrowing costs.
Continue with our guides to personal finance, first time auto loans, auto finance deals, 0 APR car financing, and auto finance fundamentals for more borrowing guidance.