Heights Finance is a consumer lender offering secured and unsecured personal installment loans through online applications and branch locations in several U.S. states. Borrowers may use personal loans for purposes such as debt consolidation, vehicle purchases or repairs, medical expenses, home projects, moving costs, and other personal needs.
Before applying, it is important to understand that loan approval, available amount, interest rate, fees, repayment term, and collateral requirements can vary by state and applicant.
This guide explains nine important facts about Heights Finance, including its loan products, application requirements, costs, payment options, credit insurance, MyAccount features, and questions to ask before borrowing.
Editorial disclosure: Best Finance Live is an independent educational website and is not affiliated with, endorsed by, or acting on behalf of Heights Finance.
Key Takeaways
- Heights Finance currently focuses on personal installment loans rather than offering a broad range of banking products.
- Both secured and unsecured personal loans may be available.
- Loan rates and terms vary by state and individual applicant.
- A secured loan may require collateral such as an eligible vehicle or other property.
- Credit insurance may be offered, but availability and coverage depend on the loan and policy.
- MyAccount can be used for payments, balances, AutoPay, and eStatements.
- Payment options and possible convenience fees can vary by state.
- Compare APR, fees, amount financed, and total repayment with other lenders before accepting an offer.
- Approval and funding are subject to eligibility, credit review, underwriting, and state requirements.
1. What Is Heights Finance?
Heights Finance is a financial-services company that specializes in personal installment lending.
Its official website currently states that its family of brands includes Heights Finance, Covington Credit, Quick Credit, and Southern Finance. The company operates through branch locations as well as online application and account-management options.
Visit the official Heights Finance company information page.
What is a personal installment loan?
A personal installment loan provides a borrower with a lump sum of money that is generally repaid in scheduled installments over an agreed period.
The Consumer Financial Protection Bureau explains that personal installment loans may be used for purposes such as major purchases, unexpected expenses, or debt consolidation. Terms may depend on credit history, income, debt, amount borrowed, loan length, state law, and other underwriting factors.
Read the CFPB explanation of personal installment loans.
For a broader explanation of borrowing costs, see our personal loan rates guide.
2. What Types of Loans Does Heights Finance Offer?
The current Heights Finance website emphasizes secured and unsecured personal installment loans.
Unsecured personal loans
An unsecured loan does not require the borrower to pledge a specific asset as collateral.
Eligibility and available terms still depend on the lender’s underwriting process.
Secured personal loans
A secured loan involves collateral. Heights Finance states that collateral may include certain household goods or titled property such as a car, boat, or motorcycle, depending on applicable requirements.
If you are considering secured borrowing, understand the consequences of default before pledging an asset.
Our secured personal loan guide explains collateral risk in more detail.
What can the loan be used for?
The official lender site identifies several potential personal-loan uses, including:
- auto purchase or repair;
- debt consolidation;
- medical expenses;
- home projects and repairs;
- moving expenses;
- travel;
- furniture;
- unexpected expenses; and
- other eligible personal needs.
This is different from saying the company offers a dedicated auto-loan product. Its current public materials primarily describe these as personal installment loans.
For dedicated vehicle-financing education, use our Auto Finance Center.
3. How Does the Heights Finance Application Process Work?
Heights Finance allows prospective borrowers to begin an application online, over the phone, or at an eligible branch, according to its current FAQ.
Approval is not guaranteed.
Documents you may need
The official lender FAQ identifies common application documents including:
- a driver’s license or other government-issued photo ID;
- proof of income; and
- proof of residence.
Additional documentation or collateral may be required depending on the loan, state, and applicant.
Does Heights Finance require good credit?
The company states that credit is one factor but that decisions are based on multiple factors.
That should not be interpreted as guaranteed approval for borrowers with poor or limited credit.
Applicants are still subject to eligibility, credit review, underwriting, applicable laws, and lender requirements.
Readers comparing credit options can also review our personal finance complete guide.
4. Heights Finance Rates, APR, Terms, and Fees
There is no single universal Heights Finance interest rate that applies to every borrower.
The company’s current FAQ states that loan rates and terms vary by state and applicant.
That makes it important to review the actual disclosures provided for your specific offer.
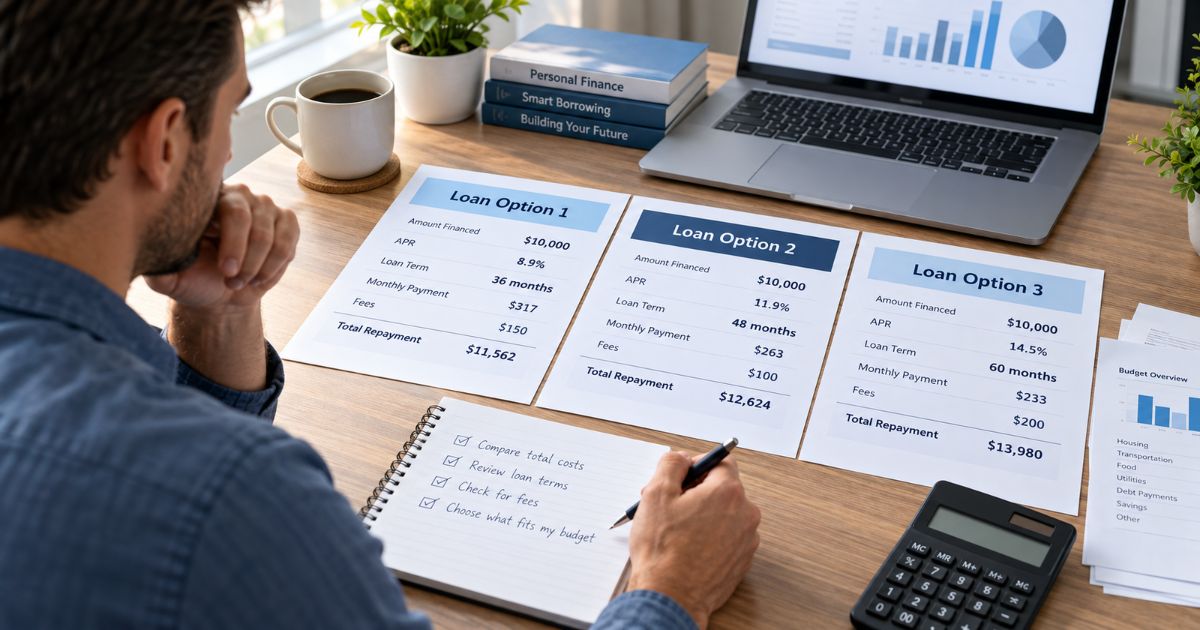
Interest rate versus APR
The interest rate represents the charge for borrowing the principal, while APR provides a broader annualized measure that incorporates the interest rate and applicable loan fees.
The CFPB recommends comparing APR and other loan costs rather than evaluating an offer by monthly payment alone.
See the CFPB explanation of APR versus interest rate.
Our guide explaining finance charges on loans provides additional background.
Check for additional fees
The CFPB notes that personal installment loans can include costs such as:
- origination fees;
- documentation fees;
- late fees;
- credit insurance premiums where applicable; and
- other disclosed charges.
Review CFPB guidance on personal-loan fees.
Compare the total repayment
Before accepting a loan, record:
- amount borrowed;
- amount actually received;
- APR;
- interest rate;
- loan term;
- payment amount;
- payment frequency;
- finance charge;
- fees; and
- total scheduled repayment.
Our top financial tips explain why total cost matters more than focusing only on a single payment figure.
5. Does Heights Finance Offer Credit Insurance?
Yes. The current Heights Finance website describes several credit-insurance products for eligible customers.
Available coverage can vary and should be reviewed using the actual policy documents.
Examples shown on the lender’s website
The company currently describes products including:
- credit involuntary unemployment insurance;
- credit property insurance;
- credit auto insurance;
- credit life insurance; and
- credit disability insurance.
See the official Heights Finance credit-insurance information.
Do not assume insurance is required
Whether a particular insurance product is available, optional, required, or appropriate depends on the loan, state, policy, and applicable rules.
Before purchasing coverage, review:
- premium;
- coverage;
- exclusions;
- waiting periods;
- benefit limits;
- cancellation rules; and
- whether the premium affects the amount financed.
Do not buy an add-on simply because it is presented alongside the loan.
6. Heights Finance MyAccount and Online Payments
Heights Finance provides an online MyAccount system for existing customers.
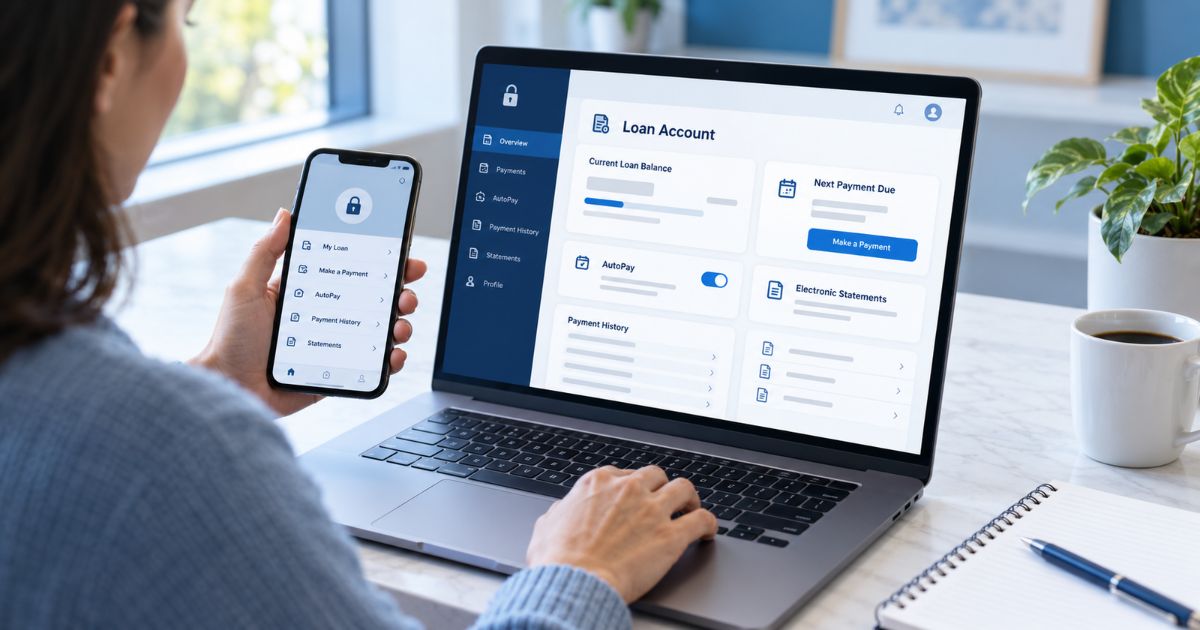
According to its current instructions, MyAccount can be used to:
- view account information;
- check a balance;
- make online payments;
- set up recurring payments;
- manage AutoPay; and
- enroll in eStatements.
View the official MyAccount instructions.
What information may be needed to register?
The official instructions currently list items including:
- account number;
- name;
- date of birth;
- email address; and
- ZIP code.
Use the official site for account access
Because account portals involve personal and financial information, access the lender through its verified website rather than unfamiliar links received through unsolicited messages.
Never share passwords, PINs, or verification codes with unverified callers or websites.
7. What Heights Finance Payment Options Are Available?
The current official site lists several ways to make a Heights Finance payment, although availability varies by state.
Options can include:
- AutoPay;
- online payments;
- payments through the mobile app;
- branch payments using eligible methods; and
- debit-card payments where available.
Check current Heights Finance payment options.
Payment-related fees may vary
The company’s payment page specifically notes that certain alternate payment methods can involve convenience or transaction fees in some states.
Always check the payment page and your loan documentation for the current rules that apply to your account.
Can a Heights Finance loan be paid off early?
The company’s current FAQ states that customers can pay off an account early and should contact their local branch to obtain the current payoff amount.
Do not simply send the balance shown on a normal statement when attempting to close an account. Request the lender’s current payoff figure.
8. What Happens If You Have Trouble Making a Payment?
If you anticipate difficulty making a payment, contact the lender as early as possible.
The current public Heights Finance material does not support assuming that every borrower automatically has a guaranteed deferment or forbearance right.
Available assistance depends on the account, contract, state, and lender policy.
The CFPB similarly advises personal-installment-loan borrowers who cannot make a payment to contact their lender promptly and ask what options are available. Possible arrangements can vary by lender.
Ask specific questions
If you are experiencing financial difficulty, ask:
- Is a payment arrangement available?
- Will interest continue to accrue?
- Will additional fees apply?
- How will the account be reported?
- Will the loan term change?
- Do I need to sign a modified agreement?
Get material changes in writing.
For broader budgeting guidance, see our financial success strategies.
9. How to Decide Whether a Heights Finance Loan Fits Your Budget
Do not choose a Heights Finance loan, or any other personal loan, solely because an application is approved.
Approval does not mean the payment is necessarily comfortable within your overall financial situation.
Compare multiple lenders when practical
The CFPB recommends shopping around because rates, fees, and terms can differ among personal-loan providers.
Compare equivalent offers based on:
| Item | Offer A | Offer B | Offer C |
|---|---|---|---|
| Amount Borrowed | _____ | _____ | _____ |
| APR | _____ | _____ | _____ |
| Term | _____ | _____ | _____ |
| Payment | _____ | _____ | _____ |
| Fees | _____ | _____ | _____ |
| Collateral | _____ | _____ | _____ |
| Total Repayment | _____ | _____ | _____ |
Ask whether the purpose justifies the cost
Borrowing for an essential expense may involve a different decision from borrowing for a discretionary purchase.
Consider whether another option could solve the same problem with less borrowing.
Our personal finance guide can help you evaluate the wider effect on your budget.
Heights Finance: Secured vs Unsecured Loans
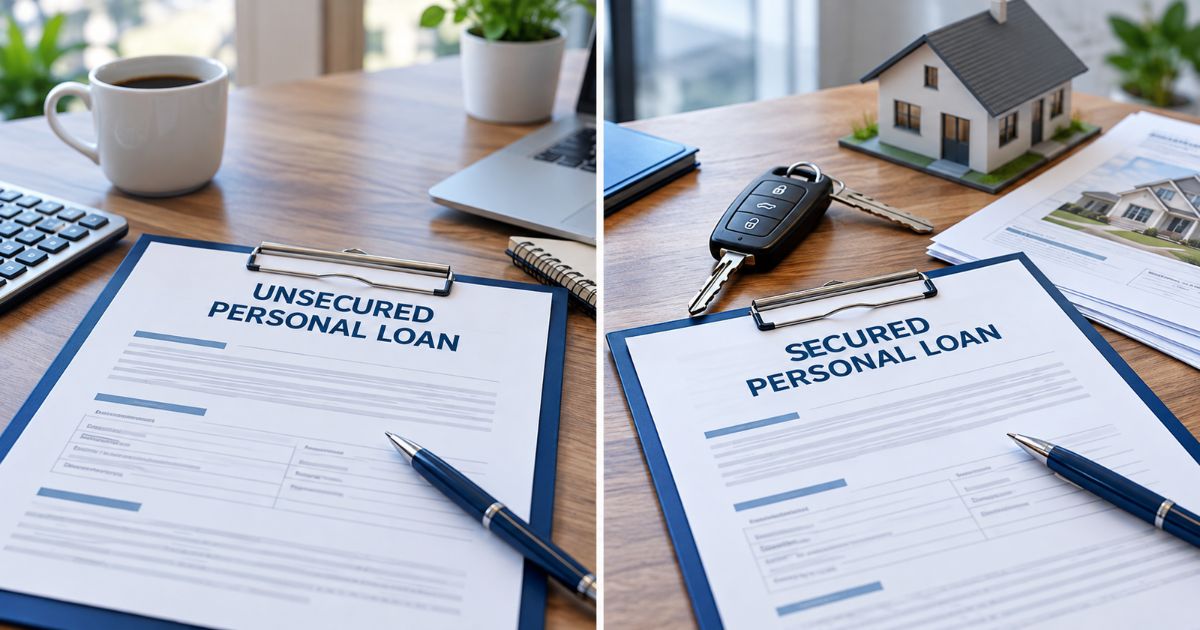
| Feature | Unsecured Personal Loan | Secured Personal Loan |
|---|---|---|
| Collateral | No specific pledged asset | Eligible collateral may be required |
| Asset Risk | No pledged asset tied directly to the loan | Pledged property may be at risk after default |
| Approval | Subject to underwriting | Subject to underwriting and collateral requirements |
| Terms | Depend on applicant and state | Depend on applicant, collateral, and state |
Read our complete secured loan comparison before putting property at risk.
Questions to Ask Before Accepting a Heights Finance Loan
Before signing a Heights Finance agreement, consider asking:
- What is the APR?
- What interest rate applies?
- What fees will I pay?
- How much money will I actually receive?
- What is the loan term?
- What is my payment amount and frequency?
- What is the total amount I will repay?
- Is this loan secured?
- What property is being pledged?
- Is credit insurance included or optional?
- What happens if I make a late payment?
- Can I pay the loan off early?
- How do I request an official payoff amount?
- Does this payment method involve a convenience fee?
- What happens if I experience a temporary financial hardship?
Our guide to comparing personal loan rates provides another checklist for evaluating borrowing costs.
Current Heights Finance Services: What Is Actually Verified?
The current official website supports the following core offerings and account features:
- secured personal installment loans;
- unsecured personal installment loans;
- loans for eligible personal purposes, including debt consolidation and vehicle purchase or repair;
- credit insurance where available;
- online and branch applications;
- MyAccount;
- online payments;
- AutoPay;
- eStatements; and
- a mobile app.
By contrast, the current public site does not provide support for describing Heights Finance as a traditional bank offering a general consumer credit-card line, broad revolving lines of credit, retirement planning, or individualized investment-advisory services.
This distinction matters because financial product information should reflect what the provider currently offers rather than older or unverified descriptions.
Frequently Asked Questions
What does Heights Finance offer?
Heights Finance currently promotes secured and unsecured personal installment loans, along with credit insurance for eligible customers and online account-management tools.
Does Heights Finance offer auto loans?
Its current website describes personal loans that may be used for auto purchase or repair. That should not automatically be described as a separate traditional auto-loan product.
Does Heights Finance check credit?
The company’s disclosures state that loans are subject to a credit check, eligibility, underwriting, approval, state regulations, rates, terms, and conditions.
How much can I borrow from Heights Finance?
Available loan amounts vary by location, applicant, secured or unsecured structure, and lender requirements. Check the company’s current state-specific information or obtain a personalized offer rather than relying on a universal amount.
What interest rate does Heights Finance charge?
There is no universal rate. The official FAQ states that rates and terms vary by state and applicant.
Can I make a Heights Finance payment online?
Yes. The current payment page and MyAccount instructions describe online payments through MyAccount and the company’s payment system, subject to available payment methods.
Can I set up AutoPay?
The official MyAccount instructions state that customers can set up recurring payments and AutoPay through their account.
Can I pay my Heights Finance loan off early?
The current FAQ says customers can pay accounts off early and should contact their branch for the current payoff amount.
Does Heights Finance offer credit insurance?
Yes, the company currently describes several credit-insurance options. Availability and policy terms vary, so review the relevant policy and loan disclosures before purchasing coverage.
Is approval guaranteed?
No. The company’s own disclosures state that loans are subject to eligibility, credit check, underwriting, approval, state regulations, rates, terms, and conditions.
Conclusion
Heights Finance currently focuses primarily on secured and unsecured personal installment lending, with online and branch application options, payment tools, MyAccount, and certain credit-insurance products.
Borrowers should not assume that approval, a particular rate, loan amount, repayment option, or insurance product is available to everyone. Terms vary according to state, applicant, collateral, underwriting, and the specific loan.
Before borrowing, compare the APR, fees, amount received, repayment term, total cost, and any collateral risk with alternatives from other lenders.
Most importantly, use the current lender disclosures and signed loan documents—not promotional claims—as the final source for your actual obligations.
Continue with our guides to personal loan rates, secured personal loans, finance charges, and financial planning tips.