KIA Optima Finance in 2026 is primarily about financing a used Kia Optima. For U.S. shoppers, the Optima is no longer part of Kia’s current new-vehicle lineup, so buyers will generally encounter it in the used-car market.
That makes financing a little different from shopping for a brand-new vehicle with current manufacturer incentives. Your loan rate, term, down payment, vehicle age, mileage, credit profile, and lender requirements can all affect the cost of financing a used Optima.
This guide explains seven practical ways to approach Kia Optima financing, from setting a budget and comparing lenders to reviewing APR, loan terms, vehicle eligibility, and the final contract.
KIA Optima Finance: Quick Overview
A Kia Optima loan works much like financing other used vehicles. You borrow money from a lender to purchase the car and repay that amount according to the loan agreement.
Depending on your situation, financing may be available through:
- banks;
- credit unions;
- online auto lenders;
- finance companies;
- dealer-arranged financing.
Rather than assuming one source will offer the best deal, compare several offers using similar loan amounts and repayment terms.
Our Auto Finance Center provides a broader introduction to vehicle financing if you want to review the fundamentals first.
Is the Kia Optima Still Available New?
For U.S. buyers, the Kia Optima should generally be approached as a used-car purchase rather than a current new-model purchase. Kia’s current U.S. sedan lineup includes the K5 rather than a new Optima.
This distinction matters for financing. A used Optima will not necessarily qualify for the same manufacturer promotions that might be advertised for current new Kia models.
Be especially careful with older online pages advertising specific Optima lease specials, rebates, or 0% financing. Promotional offers change, and an old promotion should not be treated as a current financing option.
1. Set Your Used Kia Optima Budget Before Applying
The first step in KIA Optima Finance is deciding how much vehicle you can realistically afford.
Do not base this decision only on the maximum amount a lender is willing to approve. Your personal budget should account for both the loan and the ongoing cost of owning an older vehicle.
Calculate the Total Cost of Ownership
Consider:
- vehicle purchase price;
- down payment;
- sales tax and applicable government charges;
- loan payment;
- auto insurance;
- fuel;
- registration;
- routine maintenance;
- tires;
- potential repairs.
Used vehicles can require more maintenance as they age, so leaving room in your budget for repairs can be particularly important.
Get the Out-the-Door Price
If you are buying from a dealership, ask for the vehicle’s out-the-door price in writing before focusing on financing.
This makes it easier to see the vehicle price, taxes, fees, and other charges instead of negotiating only around a monthly payment.
You can then use our auto finance calculator guide to see how the amount borrowed, interest rate, and term can affect estimated payments.
2. Review Your Credit Before Seeking a Kia Optima Loan
Your credit profile can influence the Kia Optima loan rates and terms lenders offer.
Lenders can consider more than a single credit score. Depending on the lender, underwriting can involve factors such as:
- credit history;
- credit scores;
- income;
- existing debts;
- loan amount;
- down payment;
- loan term;
- vehicle age and value.
There Is No Universal Credit Score for Approval
Avoid assuming that a particular score automatically guarantees approval or a specific APR.
Different lenders have different underwriting standards. A borrower can therefore receive different offers from different lenders even when applying for a similar vehicle and loan amount.
Check Your Credit Reports
Before applying, review your credit reports for inaccurate balances, unfamiliar accounts, or other errors.
If you find inaccurate information, use the appropriate dispute process rather than waiting until you are already negotiating financing.
Improve Your Profile Where Practical
Depending on your situation, useful steps can include:
- making bills on time;
- reducing high revolving balances where practical;
- correcting credit-report errors;
- avoiding unnecessary new debt before applying;
- preparing requested income and employment documentation.
If this is your first vehicle loan, our first time auto loan guide covers the application process in more detail.
3. Compare KIA Optima Finance Options From Multiple Lenders
One of the most important parts of KIA Optima Finance is shopping around rather than automatically accepting the first offer.
Consider comparing banks, credit unions, online lenders, finance companies, and dealer-arranged financing.
Direct Financing
With direct financing, you seek financing directly from a bank, credit union, or another lender before or during the vehicle-shopping process.
Getting an outside offer can give you a benchmark when the dealership presents its own financing options.
Dealer-Arranged Financing
Dealer-arranged financing can be convenient because the dealer helps arrange the credit transaction. However, convenience does not necessarily mean the offer has the lowest APR or lowest total cost.
Compare dealer financing against outside offers before deciding.
For more options, review our top auto finance guide and best auto finance deals guide.
Compare Offers on Similar Terms
Try to compare approximately the same:
- amount financed;
- down payment;
- loan term;
- vehicle;
- transaction structure.
Otherwise, one offer may appear cheaper simply because it stretches repayment over a longer period.
4. Understand APR, Interest, and Total Kia Optima Loan Cost
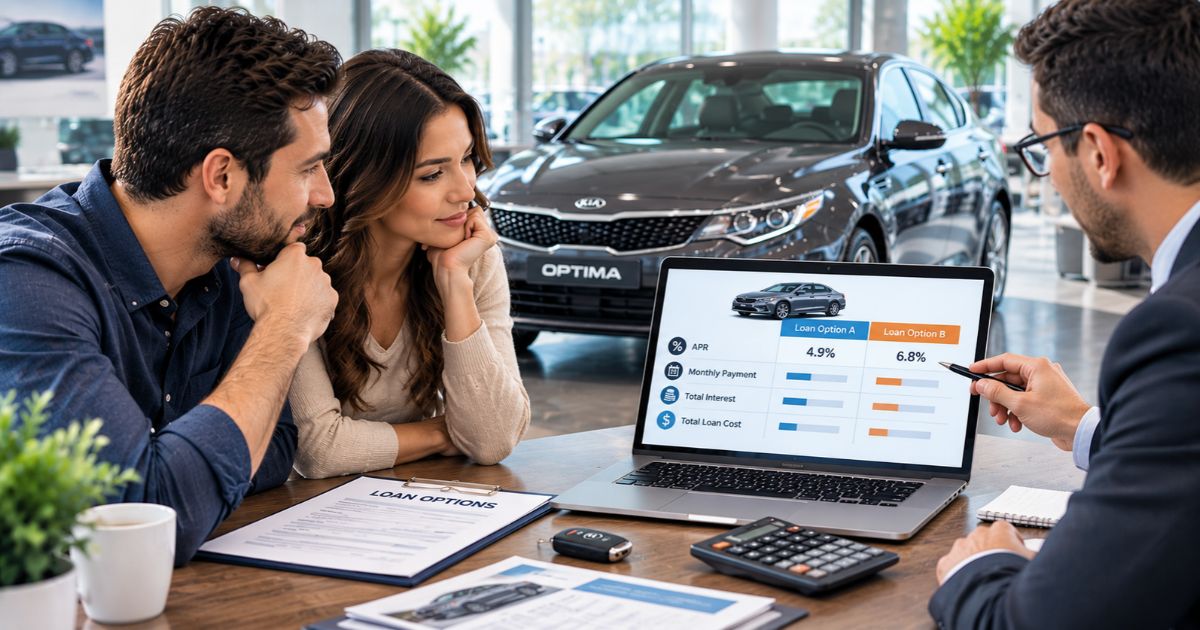
A good Kia Optima auto loan comparison should go beyond the advertised interest rate.
Review several figures together:
| Loan Factor | What to Review |
|---|---|
| Interest Rate | The rate used to calculate interest on borrowed funds |
| APR | A standardized annual measure of credit cost |
| Amount Financed | The amount of credit provided under the transaction |
| Finance Charge | The dollar cost of credit under applicable disclosure rules |
| Loan Term | How long you have to repay the loan |
| Monthly Payment | The scheduled recurring payment |
| Total of Payments | The total scheduled payments under the agreement |
Our guide to finance charges on a loan explains the differences between interest, finance charge, and APR.
Do Not Shop by Monthly Payment Alone
A lower Kia Optima monthly payment can look attractive, but it may simply result from extending the loan over more months.
For example, a longer loan can reduce the required monthly payment while potentially increasing total interest and keeping you in debt longer.
Shorter vs. Longer Loan Terms
| Shorter Term | Longer Term |
|---|---|
| Usually higher monthly payment | Usually lower monthly payment |
| Principal is repaid faster | Principal is repaid more slowly |
| Can reduce total interest | Can increase total interest |
| Less time in debt | More time in debt |
The right term depends on the actual offer and your budget. Compare total cost rather than automatically selecting the shortest or longest option.
5. Get Preapproved Before Shopping for a Used Kia Optima
Getting preapproved can make used Kia Optima financing easier to compare.
Depending on the lender, a preapproval may provide information about:
- potential borrowing limit;
- interest rate or rate range;
- loan term;
- estimated payment;
- vehicle restrictions;
- offer expiration.
Why Preapproval Can Help
A preapproval gives you an outside financing offer before you rely on dealership financing. It can also help establish a realistic vehicle budget.
When you reach the dealership, you can compare the dealer’s financing proposal against the outside offer rather than evaluating the dealer’s offer in isolation.
Preapproval Is Not Final Approval
Do not assume a preapproval guarantees funding for every Kia Optima.
Final financing may remain subject to verification, underwriting, and approval of the particular vehicle and transaction.
6. Make Sure the Used Kia Optima Qualifies for Financing
When you finance a used Kia Optima, the lender evaluates more than the borrower. The vehicle itself can affect eligibility.
Ask About Vehicle Restrictions
Depending on the lender, restrictions may involve:
- model year;
- vehicle age;
- mileage;
- market value;
- title status;
- loan-to-value ratio;
- minimum or maximum loan amount;
- dealer or private-party seller.
There is no universal age or mileage rule for every lender, so verify the requirements of each lender you are considering.
Inspect the Vehicle Before Buying
Financing approval does not tell you whether a particular used Optima is mechanically sound.
Consider reviewing the vehicle history and arranging an independent mechanical inspection before committing to the purchase.
A professional inspection can potentially identify mechanical problems that are not obvious during a short test drive.
Check for Safety Recalls
Use the vehicle’s VIN to check for open safety recalls through the National Highway Traffic Safety Administration.
Because you are purchasing a used vehicle, checking the specific VIN is more useful than assuming every Optima from a particular model year has the same history.
Compare the Price With Similar Vehicles
Consider model year, mileage, trim, equipment, condition, location, and vehicle history when evaluating the asking price.
A lower purchase price or larger down payment can reduce the amount you need to finance.
7. Review the Kia Optima Financing Contract Before Signing
The final step in KIA Optima Finance is carefully reviewing the actual contract and disclosures.
Check the Truth in Lending Information
For covered closed-end auto credit, important disclosures can include:
- Annual Percentage Rate (APR);
- finance charge;
- amount financed;
- total of payments;
- payment schedule.
Make sure these figures match your understanding of the deal before signing.
Check the Vehicle Transaction
Also review:
- agreed vehicle price;
- taxes;
- government fees;
- dealer fees;
- down payment;
- trade-in credit;
- negative equity, if applicable;
- optional products and add-ons.
Evaluate Add-Ons Separately
Dealers may offer service contracts, GAP products, credit-related products, or other add-ons.
Before agreeing, ask:
- How much does it cost?
- Is it optional?
- What does it cover?
- What is excluded?
- Can it be canceled?
- Will the cost be added to the amount financed?
Adding products to the loan can increase both the amount borrowed and the total cost.
Can You Lease a Kia Optima in 2026?
Traditional new-car leasing should not be presented as a standard current Kia Optima financing option in the U.S. because the Optima is no longer a current new Kia model.
You may encounter unusual used-vehicle lease arrangements in the market, but they should be evaluated based on their actual terms rather than assumed to work like a manufacturer-supported new-car lease.
If your goal is simply a lower monthly payment, compare the complete cost and restrictions instead of assuming leasing is automatically cheaper.
What About Kia Optima CPO Financing?
Certified pre-owned availability changes as vehicles age and according to the manufacturer’s current program requirements and dealer inventory.
Do not assume every used Kia Optima qualifies as a current Kia Certified Pre-Owned vehicle or receives a special financing rate.
If a dealer advertises a vehicle as certified, verify:
- which certification program applies;
- inspection requirements;
- warranty coverage;
- vehicle eligibility;
- whether any advertised financing promotion actually applies to that vehicle.
Can You Get 0% Financing on a Kia Optima?
Do not assume current 0% manufacturer financing is available for a used Kia Optima.
Zero-percent offers are promotional programs with specific eligibility requirements, vehicles, terms, and expiration dates. An old advertisement or article does not establish that the offer remains available today.
If you encounter a promotional offer, compare it with other incentives and financing alternatives before deciding.
Our 0 APR car finance guide explains how promotional financing works and what to compare.
Kia Optima Financing With Limited or Poor Credit
A weaker credit profile does not automatically mean you cannot obtain a Kia Optima loan, but available rates and terms may be less favorable.
Instead of accepting the first high-cost offer, consider:
- comparing multiple lenders;
- saving a larger down payment where practical;
- choosing a less expensive vehicle;
- reviewing your credit reports for errors;
- considering a qualified co-signer only after both parties understand the obligation.
Be Careful With a Co-Signer
A co-signer can become legally responsible for the debt if the primary borrower does not pay as agreed. Payment problems can also affect the co-signer’s credit when reported.
This should therefore be treated as a serious financial obligation rather than simply a way to obtain approval.
How a Down Payment Affects Kia Optima Financing
A larger down payment can reduce the amount you need to finance.
| Illustrative Vehicle Price | Down Payment | Amount Before Other Costs |
|---|---|---|
| $15,000 | $1,500 | $13,500 |
| $15,000 | $3,000 | $12,000 |
| $15,000 | $5,000 | $10,000 |
This is a simplified illustration. Taxes, fees, trade-in equity, optional products, and other amounts can change the actual amount financed.
Do not use all of your emergency savings solely to maximize a down payment. Balance the benefits of borrowing less against your need for adequate cash reserves.
Should You Refinance a Kia Optima Loan?
If you already have a Kia Optima auto loan, refinancing may be worth evaluating when your circumstances or available loan terms have changed.
Possible reasons to investigate refinancing include:
- your credit profile has improved;
- you can qualify for a lower APR;
- you want a different repayment structure;
- the expected savings exceed applicable refinancing costs.
Compare Total Cost Before Refinancing
A refinance that lowers your monthly payment is not automatically a better deal.
If the new loan substantially extends the repayment term, you could remain in debt longer and potentially pay more interest.
Compare:
- new APR;
- fees;
- remaining balance;
- new term;
- monthly payment;
- estimated total cost.
Can You Pay Off a Kia Optima Loan Early?
Paying a vehicle loan off early can reduce future interest in some situations, but the actual savings depend on the loan structure and contract.
Before making extra payments or requesting payoff, check:
- whether a prepayment penalty applies;
- how additional payments are credited;
- your current payoff amount;
- whether extra payments are applied to principal;
- whether using the money elsewhere better fits your financial priorities.
Do not assume paying off an installment loan early will automatically increase your credit score. Credit scoring depends on multiple factors and individual credit-file information.
What If You Can No Longer Afford the Payments?
If your Kia Optima monthly payment becomes difficult to afford, contact your lender or servicer as early as possible.
Depending on the lender and circumstances, potential options may include discussing hardship arrangements, refinancing, selling the vehicle, or other solutions.
Do not assume voluntarily returning the vehicle automatically cancels the debt. Repossession can have serious financial and credit consequences, and you may still owe a deficiency after the vehicle is sold.
See our guide on returning a financed car before considering that option.
If selling is more appropriate, read our guide explaining how to sell a financed car.
Common KIA Optima Finance Mistakes to Avoid
Focusing Only on the Monthly Payment
A lower payment can be created by extending the term, which may increase total borrowing costs.
Assuming Old Kia Promotions Still Apply
Old Optima advertisements for rebates, leases, or 0% APR should not be treated as current offers.
Not Comparing Multiple Lenders
Rates and underwriting standards vary. Comparing several offers can reveal meaningful differences.
Ignoring Vehicle Age and Mileage
The borrower may qualify for financing while a particular vehicle fails the lender’s eligibility rules.
Skipping an Independent Inspection
Loan approval does not establish the mechanical condition of a used vehicle.
Accepting Add-Ons Without Reviewing Their Cost
Optional products can increase the amount financed and overall cost.
Assuming a Specific Credit Score Guarantees a Rate
Lenders use different underwriting standards. No single score guarantees the same approval or APR everywhere.
Kia Optima Loan Comparison Checklist
| Factor | Offer A | Offer B |
|---|---|---|
| Vehicle Price | _____ | _____ |
| Down Payment | _____ | _____ |
| Amount Financed | _____ | _____ |
| Interest Rate | _____ | _____ |
| APR | _____ | _____ |
| Loan Term | _____ | _____ |
| Monthly Payment | _____ | _____ |
| Finance Charge | _____ | _____ |
| Total of Payments | _____ | _____ |
| Add-Ons | _____ | _____ |
| Prepayment Terms | _____ | _____ |
| Vehicle Restrictions | _____ | _____ |
Using the same checklist for each lender makes it easier to compare Kia Optima financing options without being distracted by one attractive number.
Official Consumer Resources
- Consumer Financial Protection Bureau: Auto Loans
- Consumer Financial Protection Bureau: Comparing Auto Loan Offers
- Consumer Financial Protection Bureau: How Auto Loan Rates Are Determined
- Federal Trade Commission: Financing or Leasing a Car
- Federal Trade Commission: Buying a Used Car From a Dealer
- NHTSA: Vehicle Recall Lookup
Frequently Asked Questions
Can you still finance a Kia Optima?
Yes. Used Kia Optima vehicles can potentially be financed through banks, credit unions, online lenders, finance companies, or dealer-arranged financing, subject to borrower and vehicle eligibility.
Is the Kia Optima still sold new in the U.S.?
The Optima is no longer part of Kia’s current U.S. new-vehicle lineup. Buyers shopping for an Optima will generally be looking at used vehicles.
What credit score do I need for KIA Optima Finance?
There is no universal minimum credit score that guarantees Kia Optima financing. Requirements and offered rates vary by lender, borrower profile, loan structure, and vehicle.
How can I get a lower Kia Optima loan rate?
Compare multiple lenders, review your credit before applying, correct credit-report errors, reduce high revolving balances where practical, consider an appropriate down payment, and compare offers using similar terms.
Can I get 0% financing on a used Kia Optima?
Do not assume 0% financing is currently available. Promotional financing is tied to specific programs, eligible vehicles, borrower qualifications, terms, and expiration dates. Verify any advertised offer directly before relying on it.
Should I finance a Kia Optima through a bank or dealership?
Either may be appropriate depending on the actual offer. Compare APR, interest rate, amount financed, loan term, monthly payment, finance charge, total payments, and applicable fees before deciding.
Can I refinance my Kia Optima?
Potentially. Eligibility depends on factors such as your current loan, credit profile, vehicle, lender requirements, and available refinancing terms. Compare total costs rather than focusing only on a lower monthly payment.
Should I make a large down payment on a used Kia Optima?
A larger down payment can reduce the amount financed, but the appropriate amount depends on your cash reserves and overall financial situation. Avoid draining emergency savings simply to maximize the down payment.
What should I check before financing a used Kia Optima?
Check the vehicle price, history, mechanical condition, open recalls, age, mileage, title status, lender eligibility, APR, loan term, amount financed, finance charge, total payments, and optional add-ons.
What happens if I cannot afford my Kia Optima loan?
Contact your lender or servicer as soon as possible to discuss available options. Do not assume returning the vehicle eliminates the debt, because repossession can result in credit damage and a remaining deficiency balance.
Key Takeaways
- KIA Optima Finance in 2026 is primarily a used-car financing topic for U.S. buyers.
- Do not rely on old Optima lease, rebate, or 0% APR promotions as current offers.
- Compare multiple lenders rather than choosing financing solely for convenience.
- Review APR, interest rate, amount financed, finance charge, term, monthly payment, and total payments together.
- There is no universal credit score that guarantees approval or a particular rate.
- Confirm that the specific Optima meets the lender’s age, mileage, value, and title requirements.
- Consider an independent inspection before purchasing a used vehicle.
- Evaluate dealer add-ons separately before adding them to your loan.
- A lower monthly payment does not necessarily mean a lower-cost loan.
- Review the final contract carefully before signing.
Final Thoughts
The best KIA Optima Finance strategy is not simply finding the lowest advertised monthly payment. Start with a realistic vehicle budget, review your credit, compare several lenders, and make sure the specific used Optima qualifies for financing.
Then compare APR, interest rate, loan term, amount financed, finance charge, monthly payment, and total payments. Before signing, review the vehicle price and optional products separately so you understand exactly what you are financing.
Because the Optima is now primarily a used-car purchase in the U.S., vehicle condition is also important. Consider the vehicle history, open recalls, mileage, market value, and an independent mechanical inspection alongside the financing decision.
Continue with our guides to auto financing, first time auto loans, auto finance deals, finance charges, and 0 APR car financing for additional guidance.